
Retiring overseas is no longer a niche ambition reserved for the ultra-wealthy or the particularly adventurous. In 2026, more Americans than ever are seriously exploring life beyond US borders, motivated by rising healthcare costs, lifestyle considerations, tax efficiency, and the desire for a higher quality of life.
As a globally experienced financial adviser specialising in wealth management for expat clients, I have seen first-hand how the right retirement location can materially improve both financial security and personal wellbeing. Equally, I have also seen how poor planning, rushed decisions, or misunderstanding cross-border finances can undermine what should be a rewarding chapter of life.
This guide examines the best countries for Americans to retire in 2026, drawing on global retirement indices, cost-of-living data, healthcare standards, visa accessibility, and financial planning considerations that US retirees must not overlook.
What Makes a Country One of the Best for American Retirees?
Before examining individual destinations, it is worth clarifying the key criteria I use when advising clients:
Cost of living relative to USD income
Quality and accessibility of healthcare
Visa and residency stability
Tax treatment of US pensions, Social Security, and investments
Property ownership rules
Currency risk
Established expat communities
Political and economic stability
Importantly, Americans remain subject to US worldwide taxation, regardless of where they retire. Choosing the right country is only half the equation; structuring income, investments, and assets correctly is equally critical.
Asia
(Affordability, healthcare value, and lifestyle arbitrage)
Asia continues to rise sharply in popularity, driven by affordability, improving infrastructure, and increasingly expat-friendly retirement ecosystems. According to U.S. News & World Report, eight of the world’s ten most affordable retirement destinations are now in Asia.
1. Vietnam — A Standout Retirement Destination for 2026
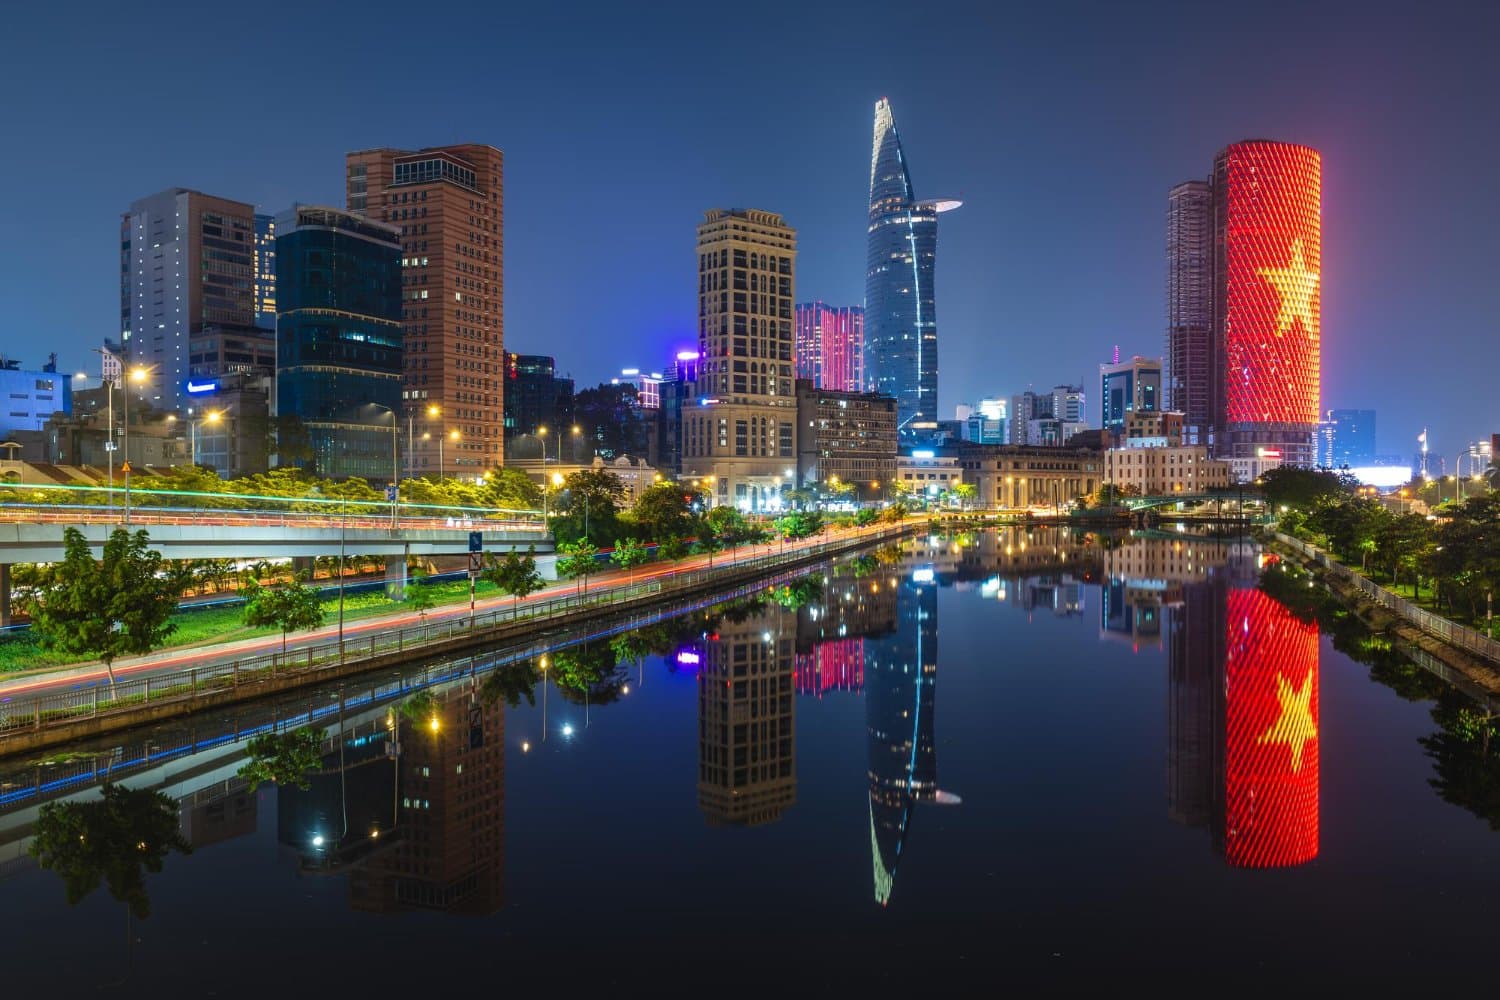
Vietnam stands out in 2026 as one of the best countries for Americans to retire who prioritise value, culture, and a slower pace of life without sacrificing comfort. While it may not yet have the name recognition of Thailand or Malaysia, Vietnam offers one of the most compelling lifestyle-to-cost ratios available anywhere in the world.
To begin with, the cost of living in Vietnam is remarkably low. In popular expat hubs such as Hoi An, Da Nang, and parts of Ho Chi Minh City, a single retiree or couple can live comfortably on $1,000–$1,500 per month.
Typical monthly expenses often look like this:
Modern one-bedroom rental: $400–$600
Utilities and high-speed internet: $50–$80
Local meals: $2–$5 per dish
Western-style dining: $8–$15 per meal
Domestic transport and taxis: $30–$60
As a result, many retirees find they are able to maintain a higher standard of living than they could on the same income in the US, while also reducing financial pressure on their investment portfolios.
Healthcare is another area where Vietnam has improved significantly. While public hospitals are primarily used by locals, private clinics and international hospitals in major cities now offer English-speaking doctors and modern facilities. Routine care is usually paid out of pocket, with costs remaining modest:
GP visit: $20–$40
Specialist consultation: $30–$60
Dental cleaning: $25–$40
For complex procedures, some expats still travel to regional medical hubs such as Bangkok or Singapore, which is both affordable and accessible via short flights.
From a financial planning perspective, Vietnam can be particularly attractive. The country does not currently tax foreign-sourced retirement income for non-residents, meaning Social Security payments, pensions, and investment income may not be taxed locally. However, Americans must still report this income to the IRS, making cross-border planning essential.
Finally, lifestyle plays a major role in Vietnam’s appeal. Daily life is social, food-focused, and community-oriented. Cities like Hoi An offer walkability, historic charm, and strong expat networks, while Da Nang provides a more modern coastal environment with excellent infrastructure.
For retirees willing to embrace a slightly less conventional destination, Vietnam represents outstanding long-term value in 2026.
2. Malaysia (Penang)
Malaysia, and Penang in particular, continues to attract retirees seeking reliability, cultural diversity, and first-class healthcare at a reasonable cost. English is widely spoken, making integration easier for Americans who prefer a smoother transition abroad.
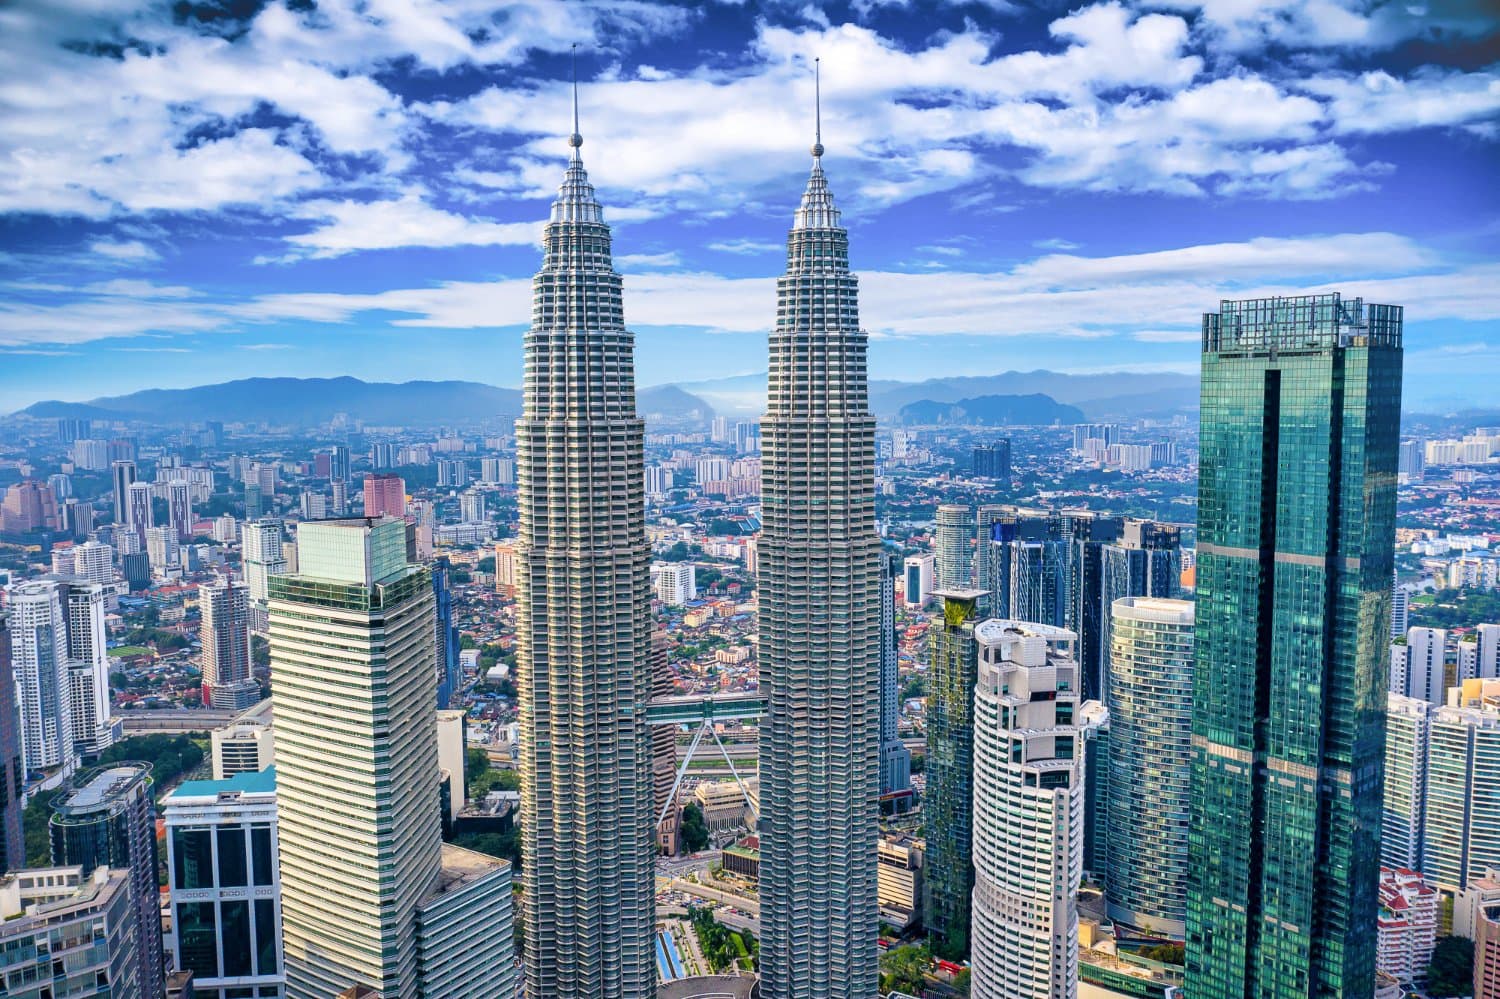
A comfortable lifestyle in Penang typically costs $2,000–$2,300 per month, which often includes:
Spacious modern apartments with pools and security
Affordable domestic help
Frequent dining out
Private healthcare access
Malaysia’s healthcare system is consistently ranked among the best in Southeast Asia. Private hospitals such as Gleneagles and Island Hospital offer internationally trained doctors, short waiting times, and transparent pricing. Many retirees either self-fund routine care or combine it with affordable international insurance.
Property ownership is permitted for foreigners above state-set minimums, and property taxes remain low by US standards. However, visa regulations, including Malaysia My Second Home (MM2H), have changed in recent years, making professional guidance essential before committing.
3. Thailand
Thailand remains one of the most established Asian retirement destinations and continues to deserve its reputation. What sets Thailand apart is choice, retirees can select between bustling cities, beach towns, or cooler northern regions depending on their preferences.
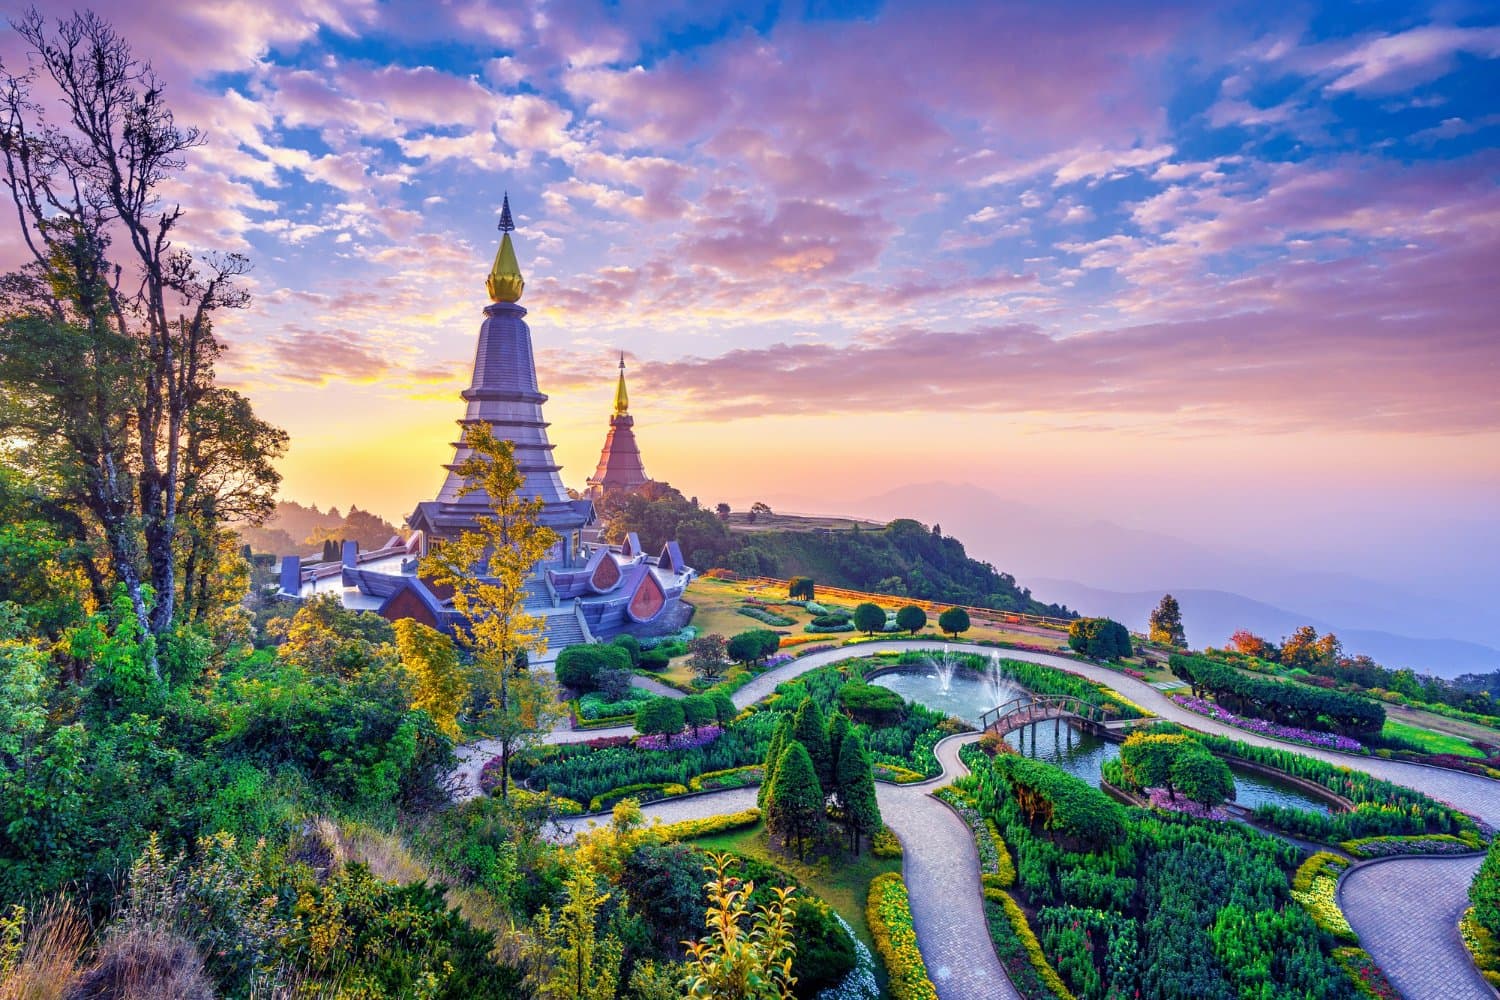
Monthly living costs vary widely but generally fall between $1,200 and $2,500, depending on lifestyle. For example:
Chiang Rai or Chiang Mai suit retirees seeking lower costs and cooler temperatures
Hua Hin, Pattaya, and Phuket cater to coastal living with excellent amenities
Thailand’s healthcare system is a major draw. Private hospitals in Bangkok and regional centres are world-class, with many doctors trained in the US, UK, or Australia. Costs are often one-third to one-half of US prices, making Thailand a global hub for medical tourism.
Thailand also offers several long-stay visa options, including retirement visas and long-term resident programmes, though requirements change regularly and must be monitored closely.
4. Philippines (Dumaguete)
For Americans who value linguistic familiarity, the Philippines offers a unique advantage: English is widely spoken nationwide. This significantly reduces the learning curve and makes daily administration, healthcare, and social integration much easier.
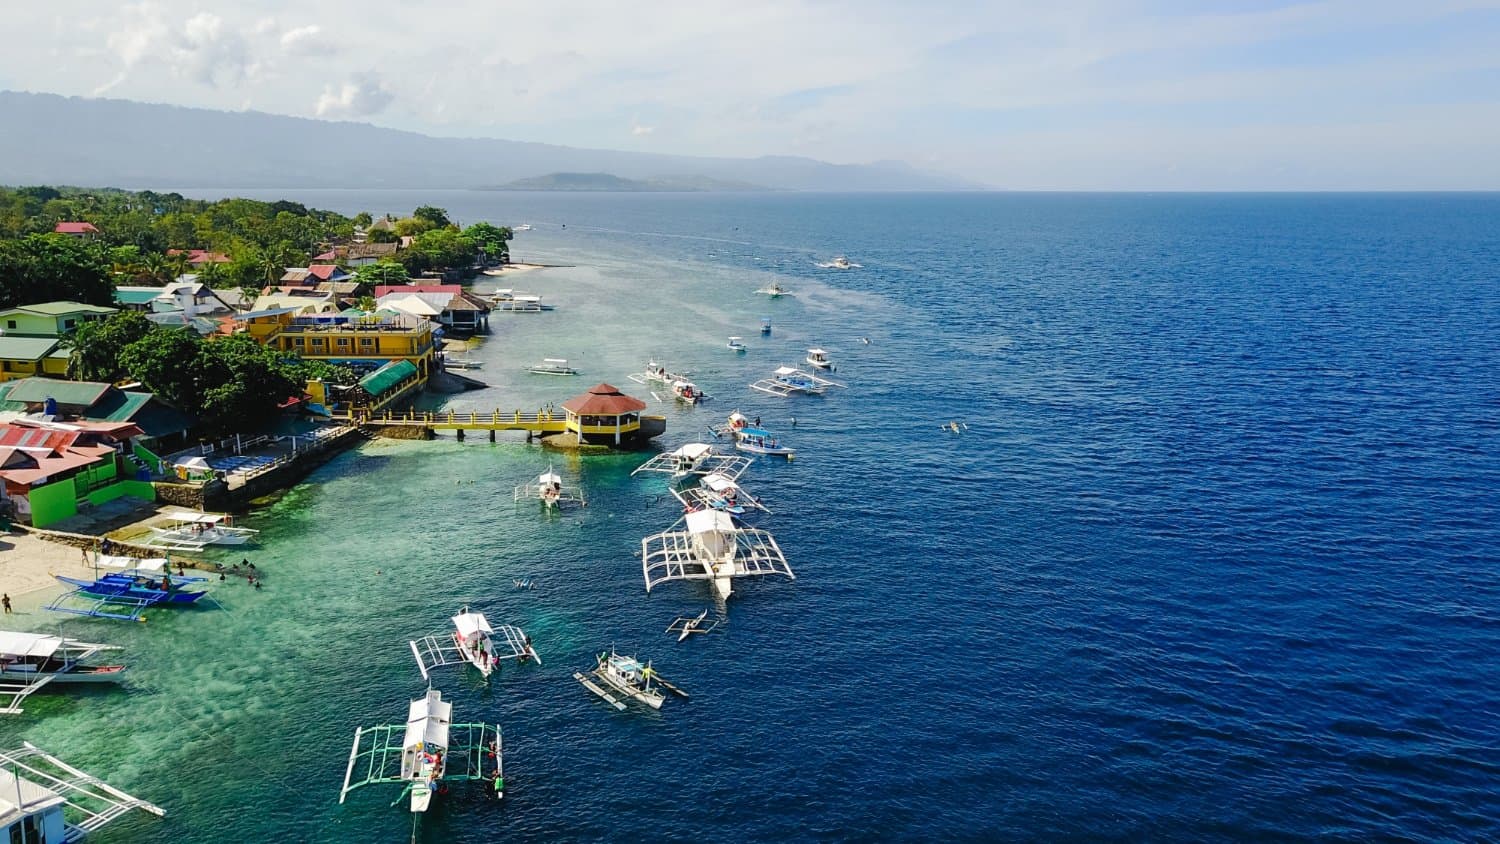
Dumaguete, in particular, has become a recognised retirement hub:
Monthly living costs: $1,000–$1,400
Rent for modern housing: $400–$500
Dining out: $5–$10 per meal
The Philippine government actively promotes retirement through dedicated visa programmes, which allow long-term stays and access to local services. While healthcare quality varies by region, Dumaguete has benefited from targeted investment in medical infrastructure.
The social environment is another strength. The culture is warm, community-driven, and family-oriented, which many retirees find deeply appealing.
Central America and Caribbean
(Proximity to the US and lifestyle balance)
Central America and the Caribbean continue to rank among the best countries for Americans to retire in 2026, particularly for those who want to remain geographically close to the United States while enjoying a lower cost of living and a more relaxed pace of life. Short flight times, familiar time zones, and cultural overlap make this region especially attractive for retirees who wish to stay connected to family without sacrificing lifestyle quality.
From a financial planning perspective, the region offers a mix of USD-linked economies, territorial tax systems, and retiree-focused visa programmes. However, quality of infrastructure, healthcare, and long-term stability varies by country, making informed selection essential.
Below are the strongest Central American and Caribbean retirement destinations for Americans in 2026.
1. Mexico
Mexico remains one of the most popular and versatile retirement destinations for Americans, largely due to its proximity, diversity, and established expat communities. For many retirees, the ability to travel back to the US easily, often in under three hours, provides invaluable peace of mind.
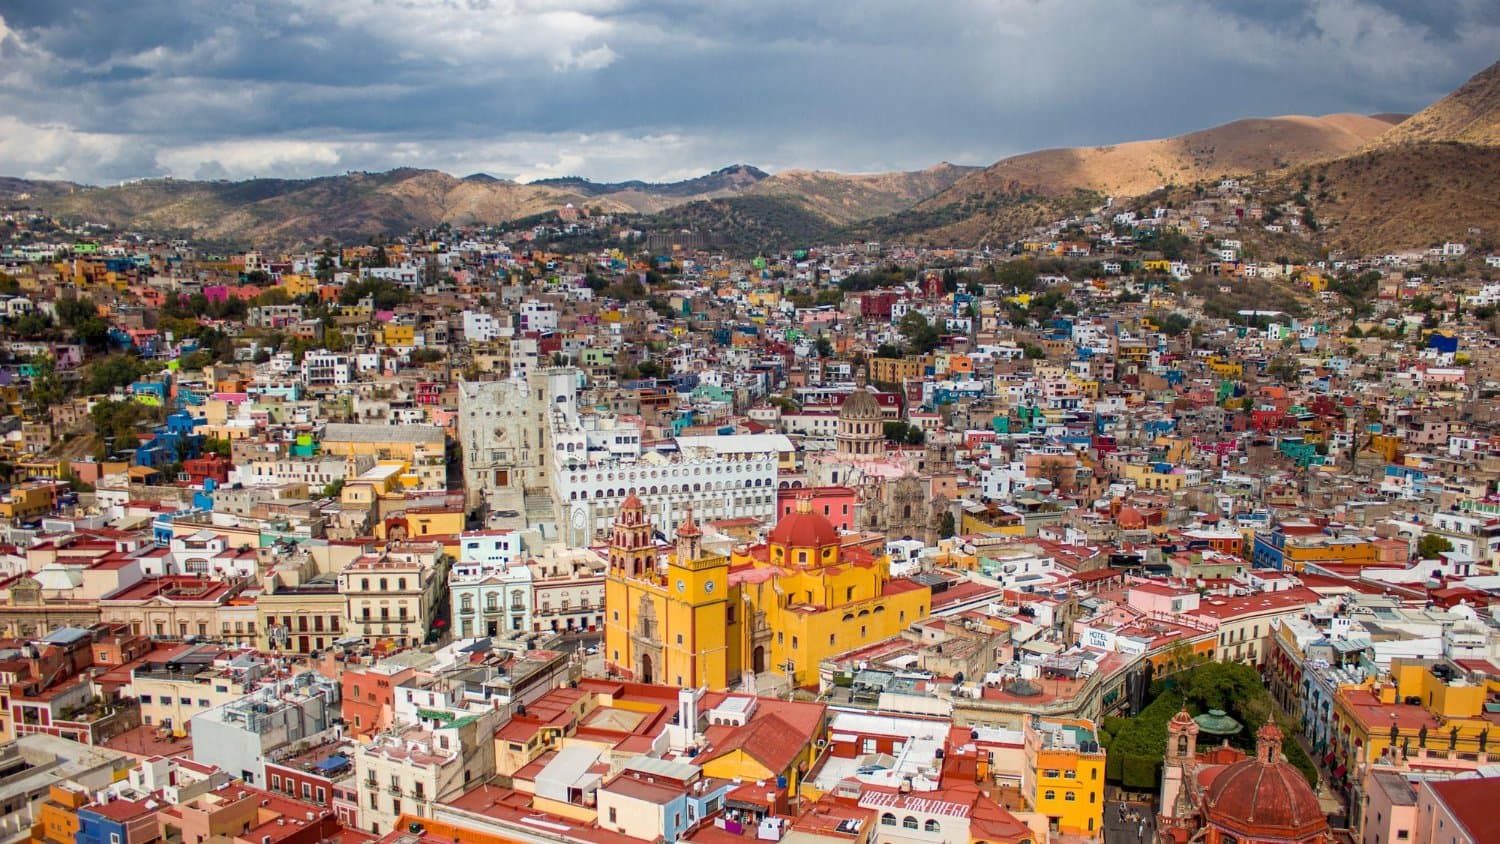
Monthly living costs vary significantly by location but typically range from $1,200 to $3,000, allowing retirees to tailor their lifestyle to their budget. For example:
Smaller inland cities such as San Miguel de Allende or Querétaro offer culture and affordability
Coastal areas like Puerto Vallarta and Playa del Carmen provide beach living with modern amenities
Healthcare is a major advantage. Mexico has a strong private healthcare system with modern hospitals, English-speaking doctors, and short waiting times. Many retirees choose to self-fund care or combine private coverage with international insurance, often at a fraction of US costs.
Residency is another strength. Mexico offers both temporary and permanent residency options for retirees, with clear financial qualification thresholds. From a planning standpoint, Mexico’s flexibility makes it one of the easiest countries for Americans to transition into retirement abroad.
2. Costa Rica
Costa Rica appeals to retirees who prioritise political stability, environmental quality, and public healthcare access. Often described as one of the most stable democracies in Latin America, it offers a sense of security that many retirees value highly.
A comfortable lifestyle typically costs between $1,500 and $3,500 per month, depending on housing choices and proximity to popular coastal regions.
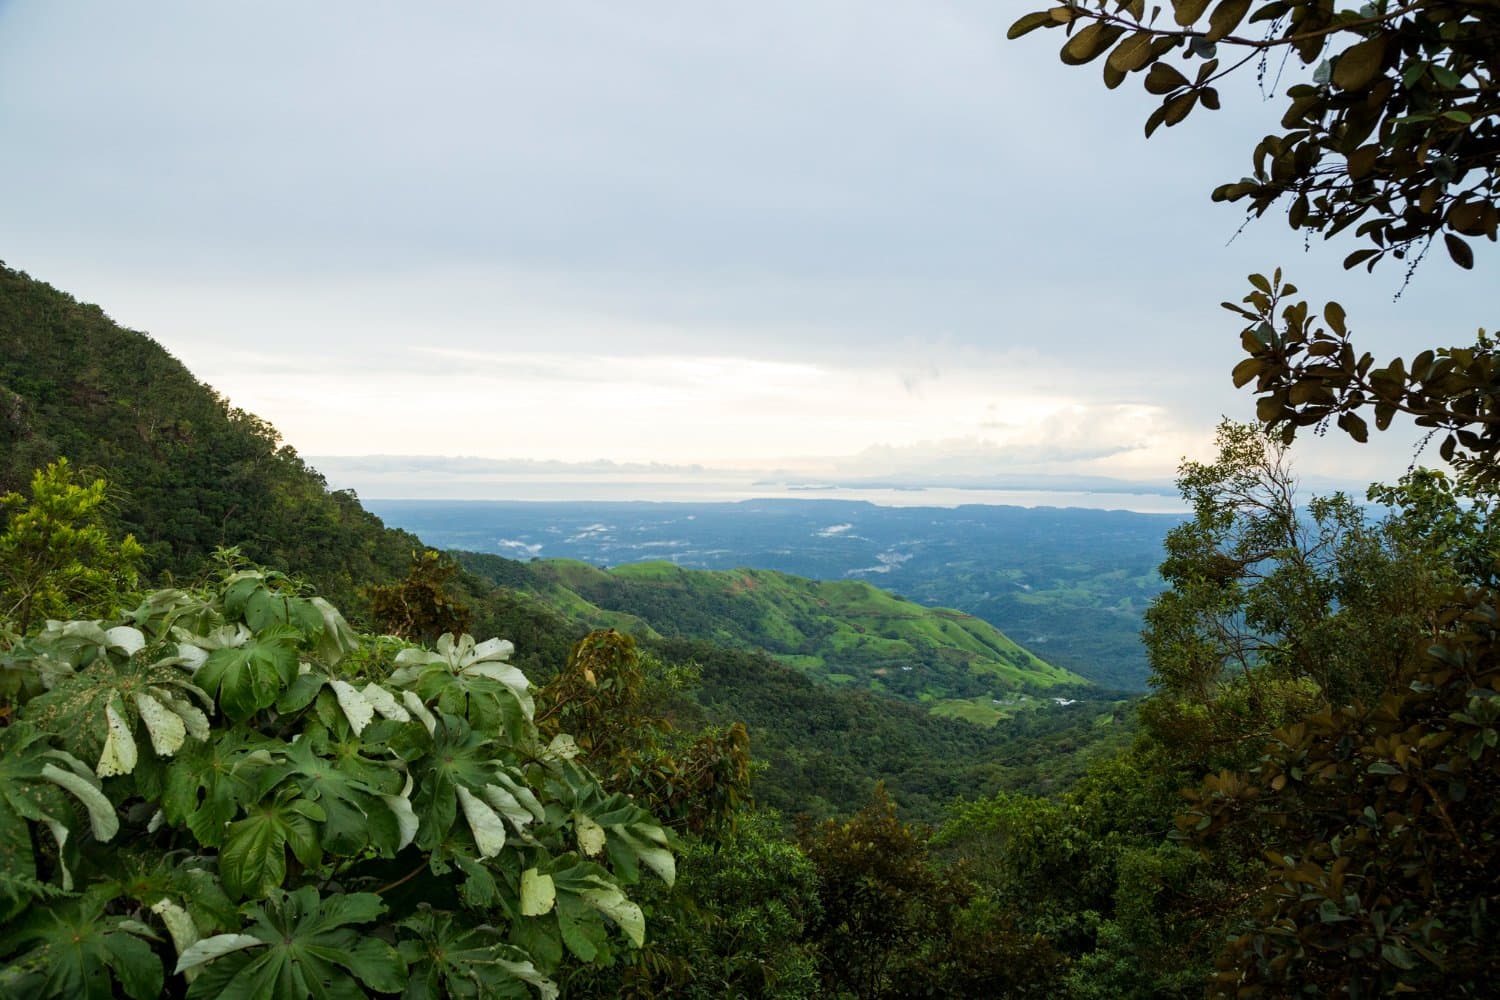
Healthcare in Costa Rica is well regarded. Legal residents can access the public healthcare system (Caja), while private healthcare is widely available and affordable. Many retirees choose a hybrid approach, using public care for routine needs and private providers for speed and convenience.
Residency options such as the Pensionado and Rentista visas are specifically designed for retirees, making Costa Rica a structured and transparent option. However, cost inflation in popular areas means careful location selection is increasingly important.
3. Panama
Panama continues to stand out as one of the most financially efficient retirement destinations in the region. The country uses the US dollar, eliminating currency risk for American retirees and simplifying budgeting and income planning.
Monthly living costs generally range from $2,300 to $2,900, with lower costs available outside Panama City.
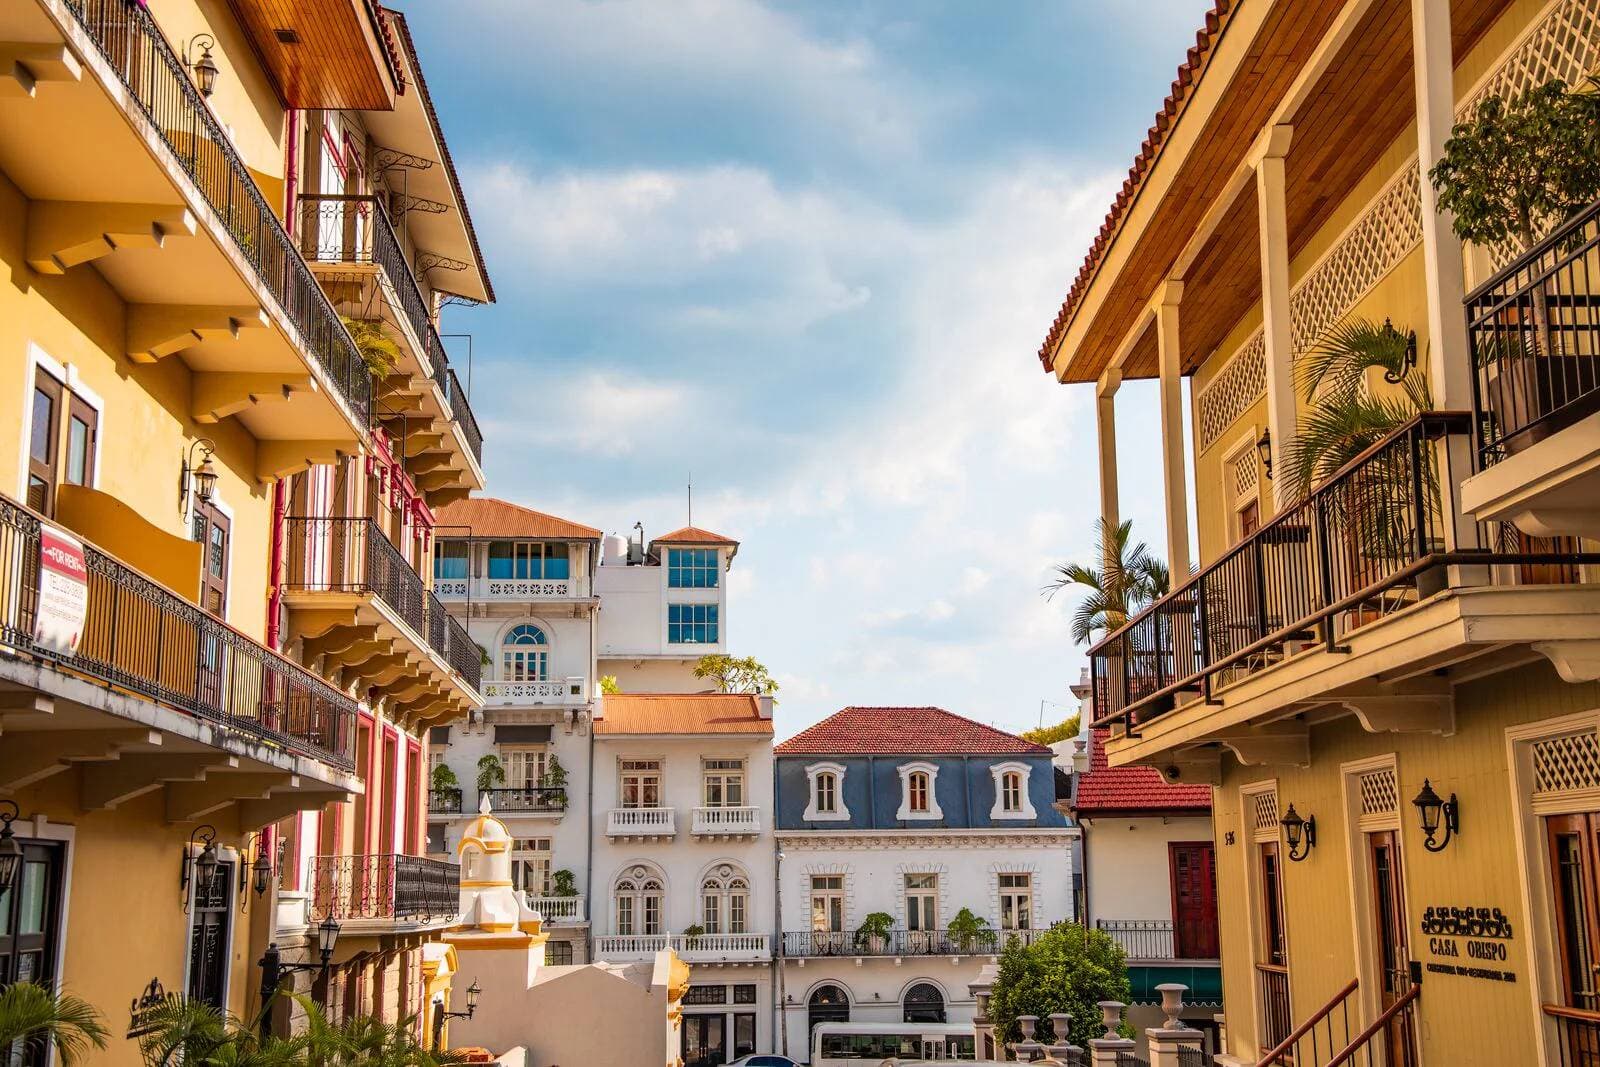
Panama’s Pensionado Visa is one of the most generous retiree visa programmes globally, offering:
Discounts on healthcare, utilities, entertainment, and travel
Access to private healthcare at competitive prices
Straightforward residency requirements for retirees with pension income
From a tax perspective, Panama operates a territorial tax system, meaning foreign-sourced income is not taxed locally. While Americans must still report worldwide income to the IRS, Panama’s structure can significantly reduce complexity and local tax exposure when planned correctly.
4. Belize
Belize offers a unique advantage in the region: English is the official language, making daily life and administration straightforward for American retirees. Combined with a Caribbean climate and slower pace of life, Belize appeals to those seeking simplicity over sophistication.
Monthly living costs typically fall between $1,500 and $2,800, depending on location and lifestyle.
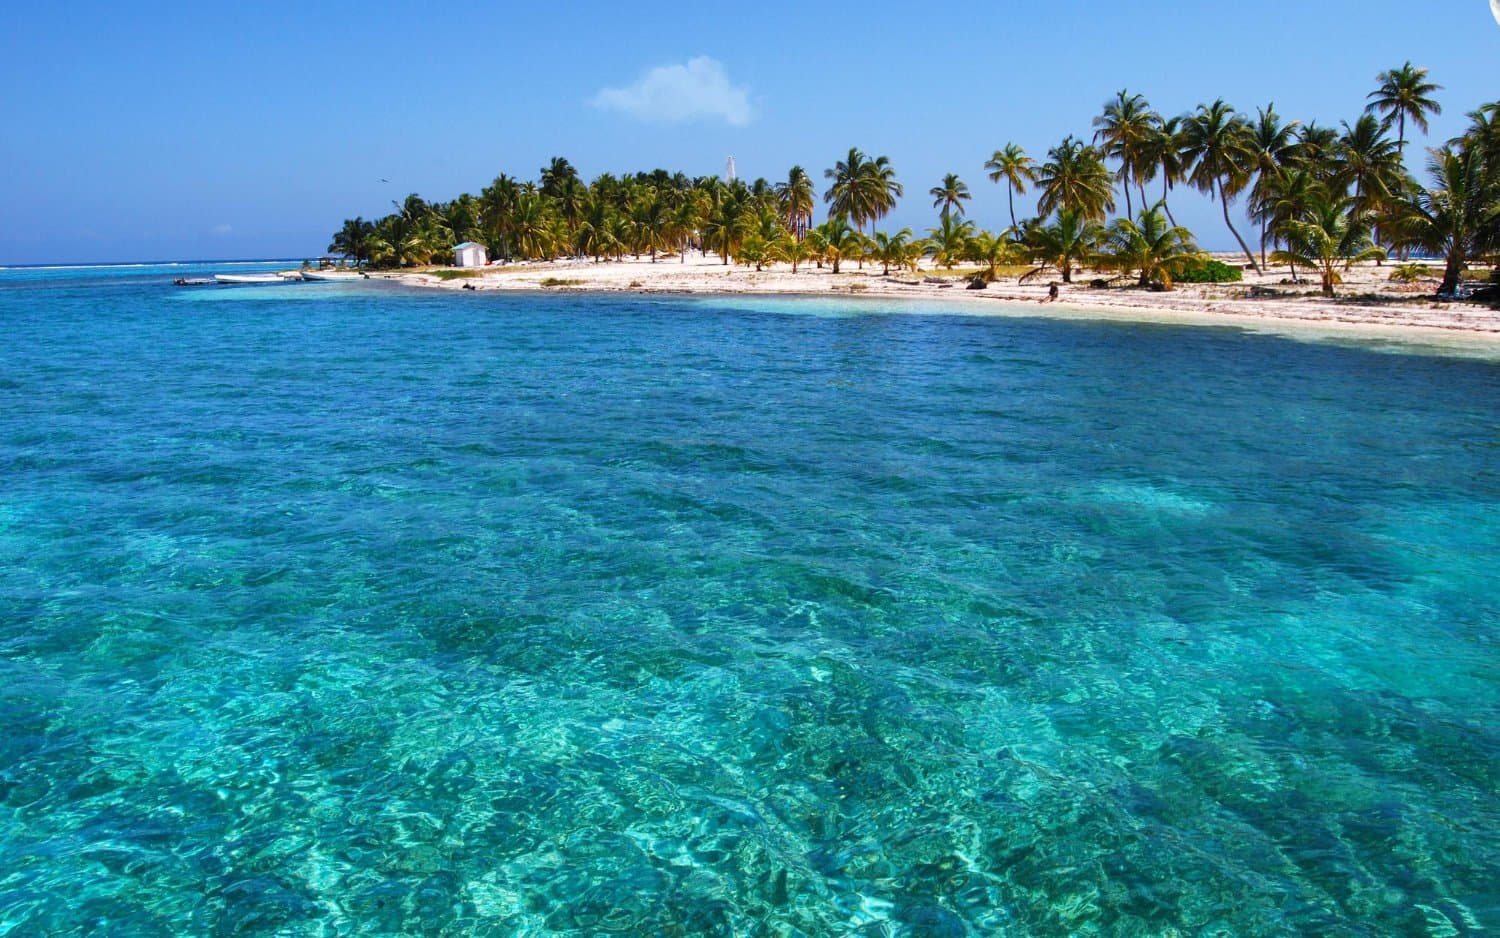
Belize’s Qualified Retired Persons (QRP) Programme allows eligible retirees to live in the country with minimal local tax exposure. However, healthcare infrastructure is limited compared with Mexico or Costa Rica, meaning some retirees travel abroad for complex medical care.
Belize is best suited to retirees who value ease of communication, natural beauty, and a laid-back lifestyle, while maintaining realistic expectations about healthcare access.
Europe
(Healthcare excellence, culture, and long-term residency stability)
Europe remains one of the most compelling regions for Americans planning retirement abroad in 2026, particularly for those who value quality healthcare, walkable cities, cultural richness, and long-established legal frameworks. While the cost of living in Europe has risen in recent years, many countries still offer excellent value compared with major US cities, especially once healthcare, transport, and lifestyle efficiencies are factored in.
From a financial planning perspective, Europe rewards retirees who plan carefully. Tax systems are more complex, but residency rights tend to be robust, infrastructure is dependable, and quality of life is consistently high. Below are the European countries that continue to rank among the best countries for Americans to retire in 2026.
1. Portugal
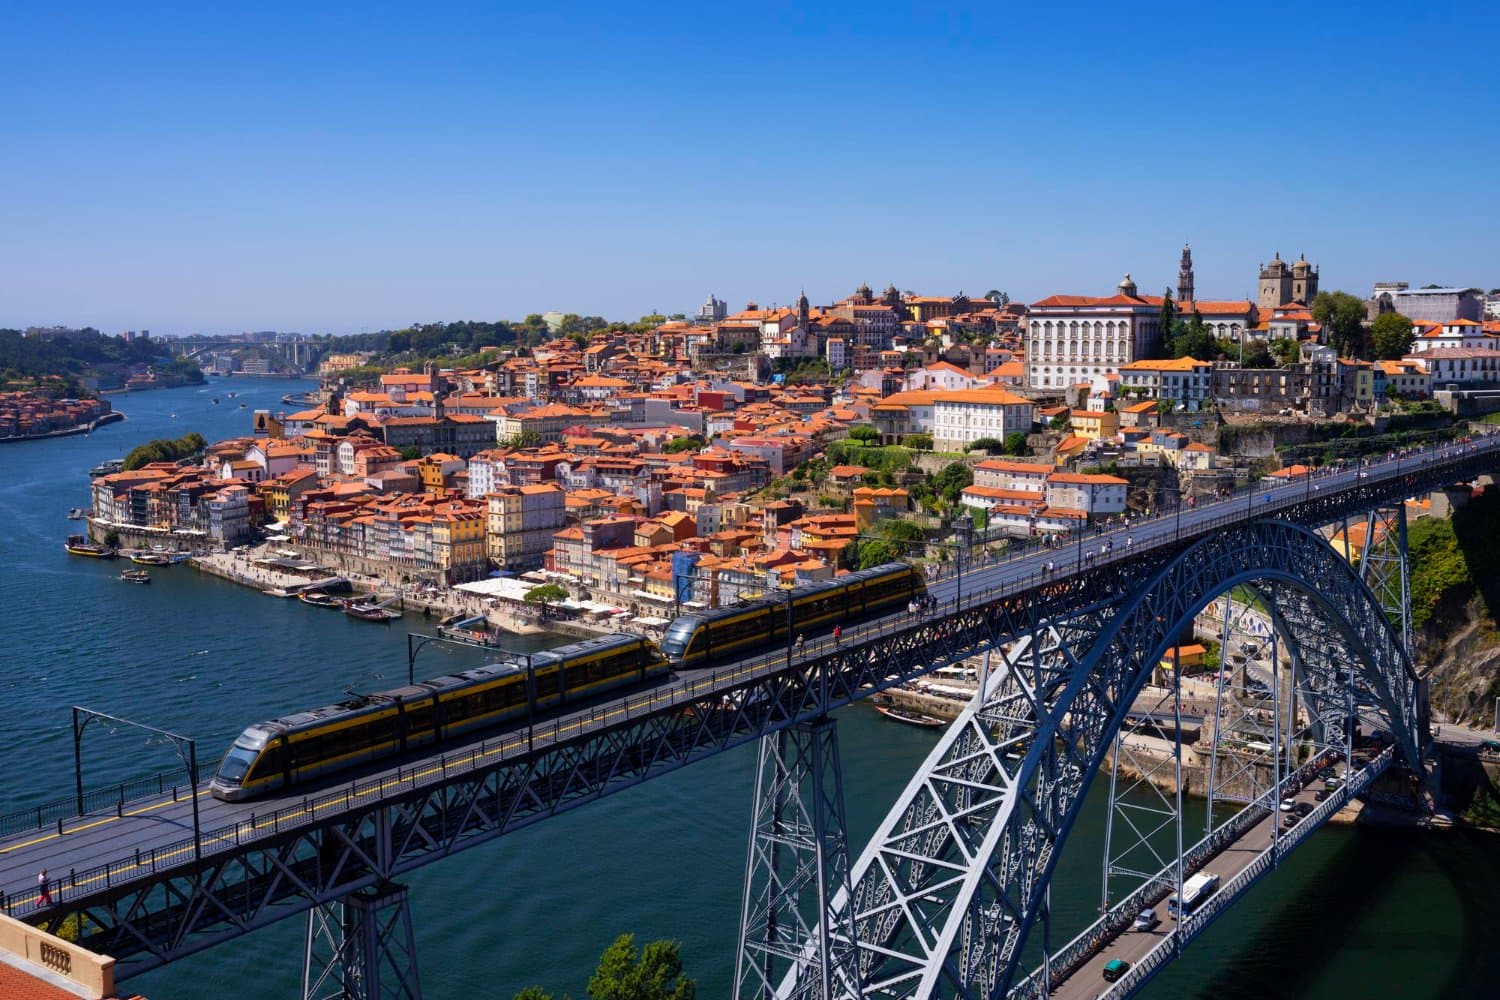
Portugal has earned its place as one of Europe’s most popular retirement destinations, and for good reason. It offers a rare balance of affordability, safety, climate, and healthcare access, making it especially attractive to American retirees seeking stability.
A realistic monthly budget for a comfortable retirement lifestyle typically ranges from $2,000 to $2,800, depending on location and housing choices. Costs are generally lower outside Lisbon and Porto, particularly in central regions, smaller coastal towns, and the islands of Madeira and the Azores.
Key advantages include:
Universal public healthcare supplemented by affordable private insurance
Well-established expat communities
High levels of safety and political stability
Straightforward residency routes via the D7 (passive income) and D8 (digital nomad) visas
From a financial standpoint, Portugal requires careful tax planning. Preferential tax regimes have evolved, and retirees should not assume automatic tax advantages.
However, with the right structure in place, particularly around pensions and investment income, Portugal can remain a highly efficient retirement base.
2. Spain
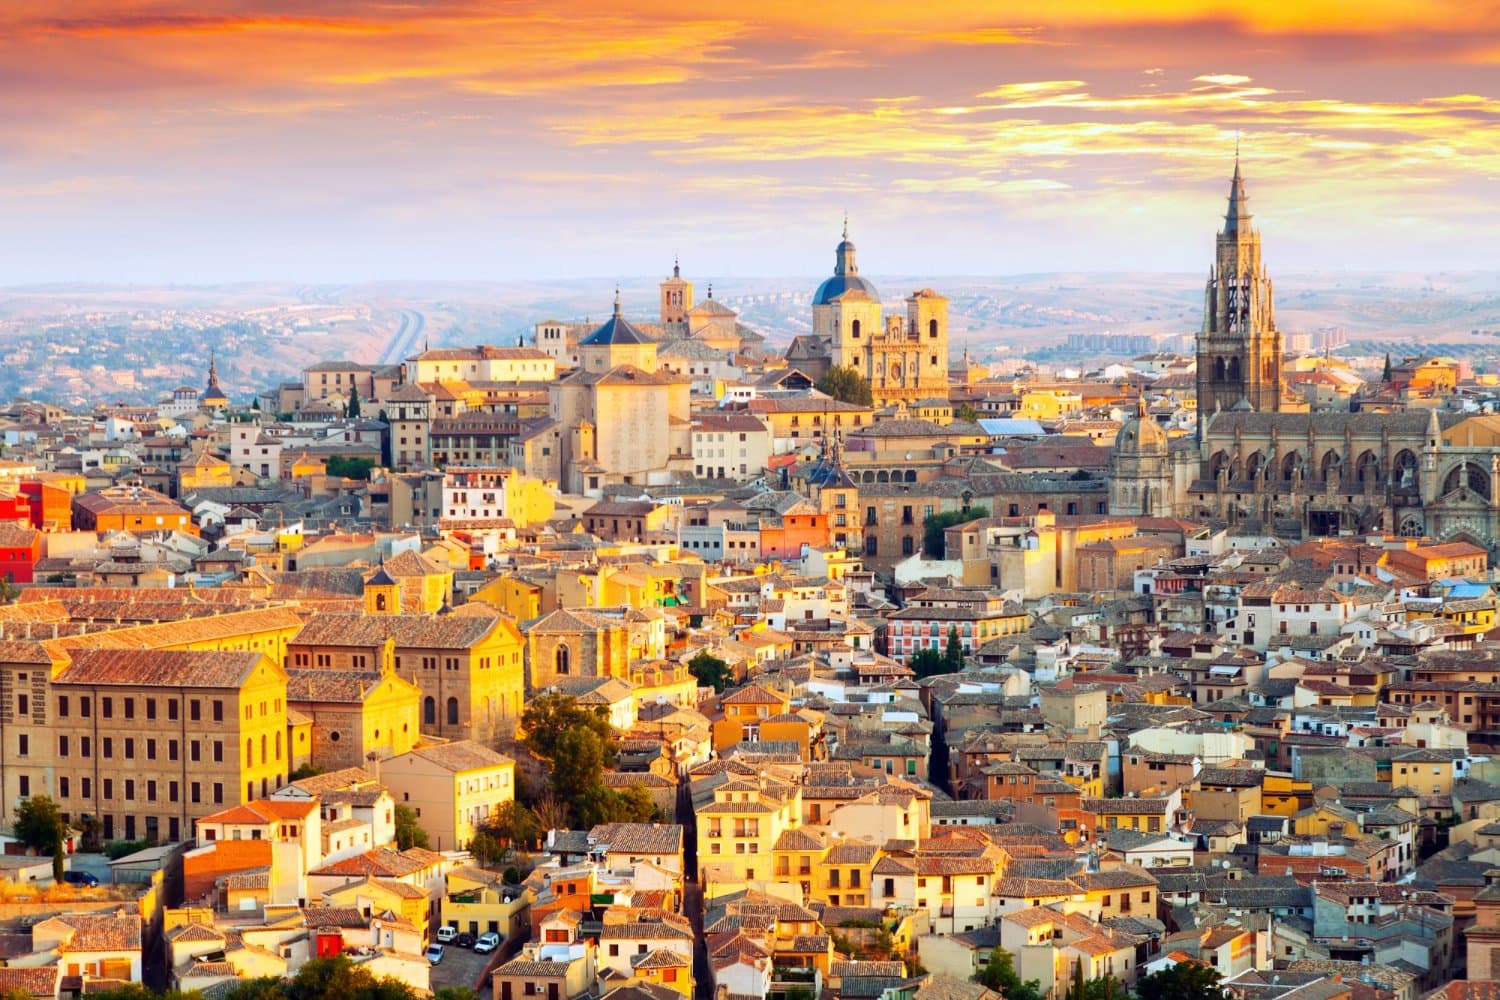
Spain continues to appeal to retirees seeking a relaxed pace of life, excellent weather, and a strong sense of community. Coastal cities and inland towns alike offer walkable neighbourhoods, vibrant social cultures, and access to one of Europe’s top healthcare systems.
A comfortable lifestyle in Spain generally costs $2,000 to $2,600 per month, with lower costs achievable in inland regions or less tourist-driven areas.
Healthcare is a major draw. Legal residents can access public healthcare after meeting residency requirements, while private insurance remains affordable by US standards. Many retirees choose to combine both.
Residency options include the non-lucrative visa, which is well suited to retirees with passive income or sufficient savings. However, Spain’s tax system can be less forgiving if not planned properly, particularly for investment income. Early financial advice is essential to avoid unnecessary exposure.
3. France
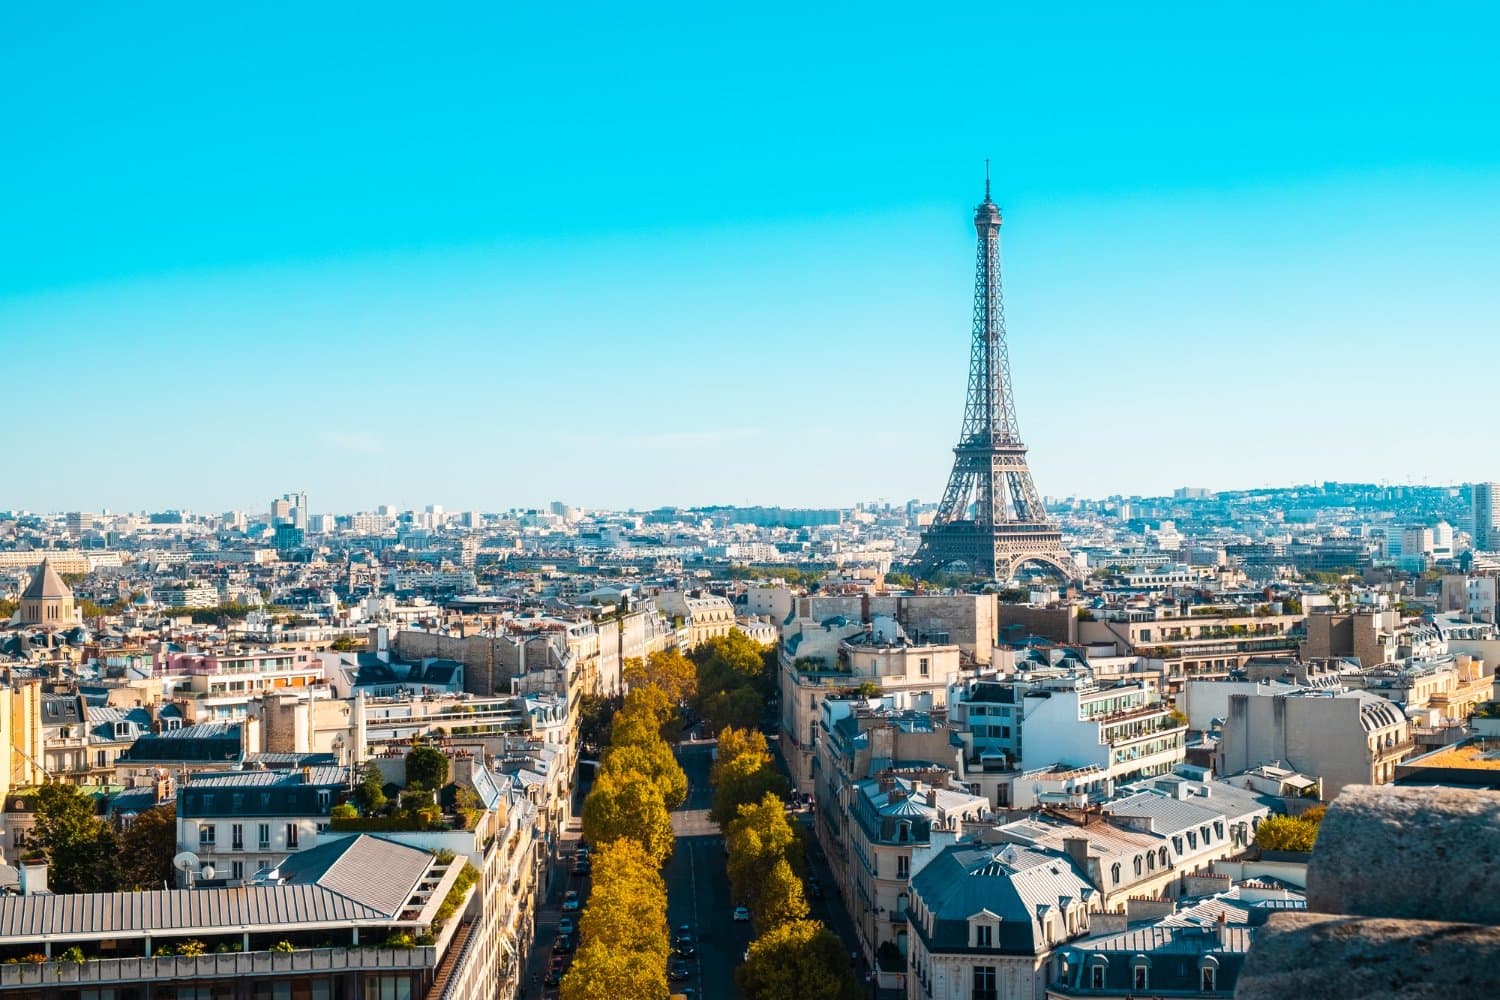
France offers something few countries can match: near-universal healthcare access regardless of age or pre-existing conditions. For retirees who place healthcare certainty high on their priority list, France remains one of the strongest choices in Europe.
Monthly living costs vary widely by region, but many retirees live comfortably on $2,400 to $3,200 per month, especially outside Paris and the Côte d’Azur. Rural regions and smaller towns offer excellent value and a slower pace of life.
From a financial adviser’s perspective, France is particularly attractive for retirees seeking:
Long-term residency stability
Predictable healthcare costs
Strong consumer protections
That said, French bureaucracy and language can be challenging initially. Retirees who invest time in learning basic French often find integration far smoother and more rewarding.
4. Italy
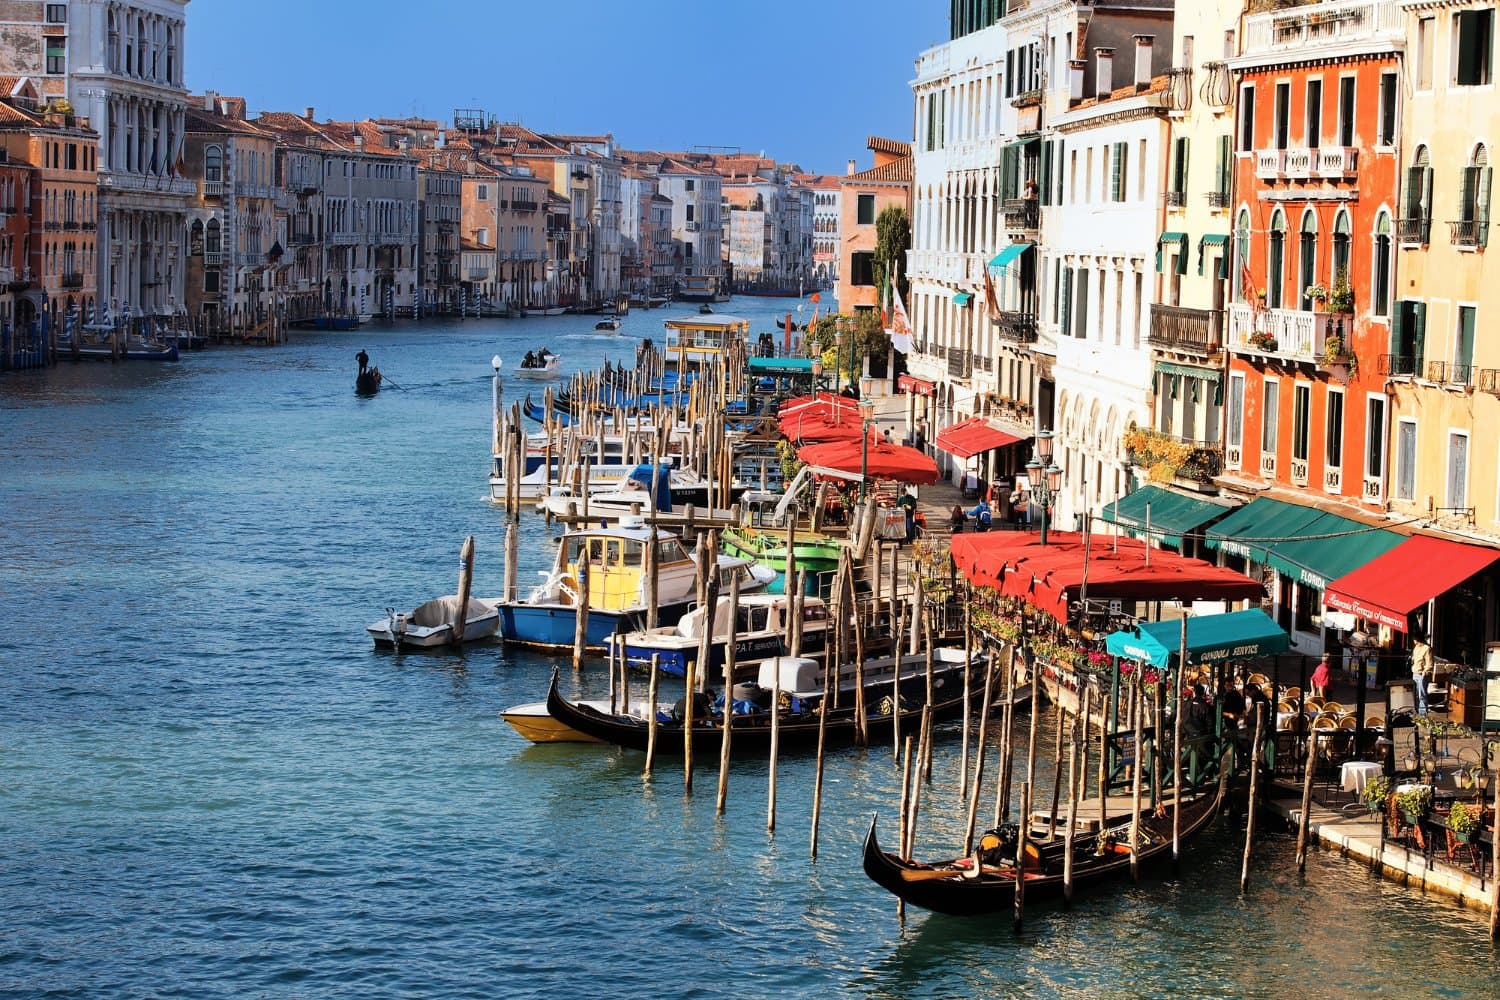
Italy continues to rank among the best countries for Americans to retire who are drawn to culture, food, and community living. While northern cities can be expensive, southern regions and smaller towns offer outstanding value.
Many retirees live comfortably on $1,800 to $2,500 per month, particularly in regions such as Sicily, Calabria, and parts of Umbria.
Key considerations include:
The Elective Residency Visa, designed specifically for retirees
Access to Italy’s public healthcare system after registration
Affordable housing, especially outside major urban centres
Italy rewards patience. Administrative processes can be slow, but lifestyle benefits, walkability, social connection, and culinary culture, are substantial. Financial planning is essential to navigate residency, taxation, and healthcare contributions efficiently.
5. Greece
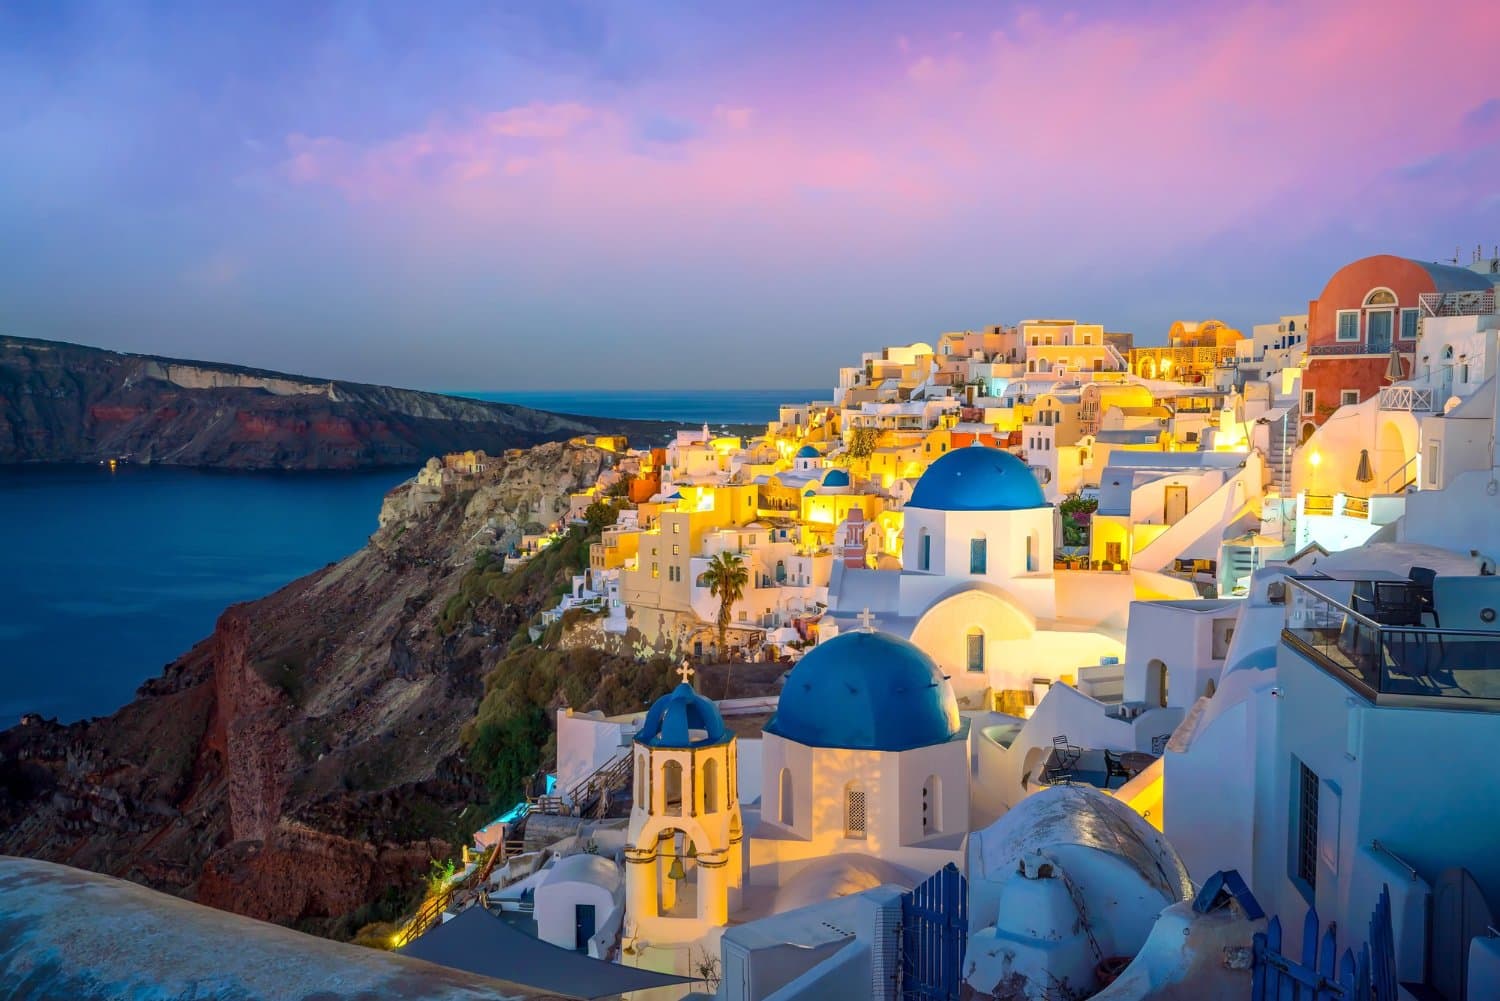
Greece has risen to the top of several global retirement rankings in 2026, and its appeal is increasingly evident. With over 300 days of sunshine in many regions, strong community living, and comparatively low living costs, Greece offers excellent lifestyle value.
Monthly living expenses typically range from $2,000 to $2,800, with significantly lower costs achievable in inland areas and lesser-known islands.
Highlights include:
Straightforward residency options for financially independent retirees
Affordable private healthcare with English-speaking doctors
Low-cost dining, fresh local produce, and active outdoor lifestyles
From a financial planning perspective, Greece can be attractive, but property purchases and long-term tax exposure must be reviewed carefully. Those who plan ahead often find Greece offers both financial efficiency and exceptional quality of life.
Key Financial Planning Considerations for American Retirees Abroad
While choosing among the best countries for Americans to retire is an exciting and often emotional decision, long-term success abroad is determined far more by financial preparation than by destination alone.
In my experience advising American expats, many of the most common challenges retirees face overseas are not lifestyle-related, but financial, and often preventable with early planning.
Below are the most important financial considerations every American should address before retiring abroad in 2026, along with practical guidance on how to approach each one.
1. US Tax Obligations Do Not Disappear
One of the most common misconceptions among Americans retiring overseas is the belief that relocating automatically reduces or eliminates US tax obligations. In reality, the United States taxes its citizens on worldwide income, regardless of where they live.
This means that income from the following sources remains reportable to the IRS:
Social Security benefits
US pensions and annuities
Investment income (dividends, interest, capital gains)
Rental income and business income

While some retirees benefit from foreign tax credits or tax treaties, these do not apply universally and must be assessed on a case-by-case basis. The key takeaway is this: retiring abroad changes how you are taxed, not whether you are taxed.
Proper structuring, particularly around pensions, withdrawals, and investment income, can significantly reduce unnecessary tax exposure and administrative complexity.
2. Currency Risk and Income Matching
When you retire abroad, your spending currency often changes, but your income may not. This creates currency risk, which can materially impact your purchasing power over time.
For example:
A retiree living in Europe but drawing income in USD is exposed to EUR/USD fluctuations
A strengthening local currency can increase living costs overnight
A weakening USD can reduce real income abroad
To manage this risk effectively, retirees should consider:
Matching income streams to local living expenses where possible
Holding multi-currency accounts
Structuring portfolios with global diversification rather than US-only exposure
Countries that use the US dollar, such as Panama, naturally reduce this risk, while destinations like Europe or Asia require more deliberate planning.
3. Healthcare Strategy Is as Important as Location
Healthcare is often one of the biggest financial variables in retirement, and moving abroad fundamentally changes how healthcare is accessed and paid for.
Many countries offer:
Public healthcare systems accessible after residency
Affordable private healthcare paid out of pocket
Hybrid systems combining public access with private care
For example:
In Asia, many retirees self-fund routine care due to low costs
In Central America, private healthcare fills gaps in public systems
In Europe, residency often unlocks comprehensive public healthcare
The key is not choosing “the best healthcare system,” but choosing the right healthcare strategy for your age, health profile, and risk tolerance. International health insurance, local private plans, or self-funded care all have a role, but only when coordinated properly.
4. Estate Planning and Succession Laws
One of the most overlooked aspects of retiring abroad is estate and estate planning. Many countries operate under forced heirship or civil law systems, which can override US wills if not addressed proactively.
Key risks include:
Local laws dictating how assets are distributed
Conflicts between US estate plans and foreign legal systems
Delays or complications for heirs living in the US
Retirees should review:
Whether a local will is required
How foreign property is treated upon death
Whether beneficiary designations align with international rules
Proper planning ensures that your wishes are respected across borders and that your family avoids unnecessary legal and financial stress.
5. Investment Strategy Must Reflect Your New Reality
Retirement abroad changes the context in which your investments operate. Portfolios designed for accumulation in the US may no longer be suitable once income withdrawals begin overseas.

Key considerations include:
Aligning investments with spending currency
Managing volatility when living expenses are fixed
Ensuring liquidity for healthcare and emergencies
Avoiding products that are tax-inefficient for US expats
In many cases, simplifying portfolios and focusing on income sustainability rather than growth becomes the priority. Investment decisions should support your lifestyle, not complicate it.
6. Banking and Access to Funds
Practical access to money is another area where retirees encounter surprises. Not all US banks are willing to maintain accounts for clients living abroad, and some foreign banks are reluctant to accept US citizens due to reporting requirements.
Before relocating, retirees should ensure:
Reliable access to US-based accounts
International transfer solutions with reasonable fees
Debit and credit cards that function globally
Backup options in case of account restrictions
Establishing these systems early prevents unnecessary disruption once you are living overseas.
Planning Your Retirement Abroad with Benjamin Sharvell
Countries such as Vietnam, Portugal, Panama, and Greece demonstrate how far your retirement income can stretch when paired with sound financial planning. In particular, Vietnam stands out as a high-value, under-appreciated option for those willing to look beyond traditional retirement hotspots.
As an expat myself, I understand both the excitement and complexity of retiring abroad. With the right preparation, this next chapter can be not only affordable, but deeply fulfilling.
Get in touch with us today for a free retirement planning consultation!