
For many UK retirees, Southeast Asia continues to stand out as one of the most attractive regions in the world for retirement.
Among the most commonly compared destinations are Vietnam and Thailand. Both countries offer unique advantages, vibrant expat communities, and affordable lifestyles when compared with the UK. However, they differ significantly in areas such as visas, healthcare infrastructure, cost of living, taxation, property ownership, and overall retirement suitability.
In this guide, I, as both an expat and financial adviser with many years of expatriate experience, will provide a complete comparison of Vietnam vs Thailand for UK retirees, helping you understand the practical realities of retiring in each country and what to consider before making a move.
Why UK Retirees Are Choosing Southeast Asia
Retirement in the UK has become increasingly expensive. Rising living costs, pressure on pensions, high utility bills, and property prices have encouraged many retirees to look overseas for better value and a higher quality of life. Which is why countries with lower cost of living such as those in Southeast Asia are slowly becoming prime retirement destinations for UK residents.
Aside from lower day to day living expenses, Southeast Asia offers several other compelling advantages:
Warm climate all year
Access to domestic help and affordable services
Strong expat communities
Excellent regional travel opportunities
Attractive rental markets
Quality private healthcare at lower costs than the UK
Of 11 countries belonging to Southeast Asia, Vietnam and Thailand both sit high on the list for British retirees, although each country appeals to different lifestyles and priorities.
Let’s explore their differences and see which country best fits your goals.
Vietnam vs Thailand for UK Retirees: Quick Overview
Before exploring the finer details, here is a broad comparison of the two countries for UK citizens looking to either retire in Vietnam or retire in Thailand.
| Category | Vietnam | Thailand |
|---|---|---|
| Cost of Living | Generally lower than Thailand | Slightly higher than Vietnam |
| Retirement Visa Options | Limited but improving | More established |
| Healthcare | Excellent private care in major cities | More developed nationwide |
| Expat Community | Growing rapidly | Long-established |
| English Usage | Less common | More widely spoken |
| Infrastructure | Fast developing | More mature |
| Property Ownership | Restrictions for foreigners | Restrictions for foreigners |
| Lifestyle Pace | Dynamic and energetic | More relaxed |
| Tax Environment | Complex but manageable | Familiar to many expats |
| Climate | Diverse north to south | Tropical throughout |
While Thailand remains the more traditional retirement destination, Vietnam has become increasingly attractive for retirees seeking affordability, modern urban living, and long-term growth potential.
Cost of Living: Vietnam Often Offers Better Value
One of the strongest advantages Vietnam holds over Thailand is affordability.
For retirees living on a pension or investment income, controlling monthly expenses without sacrificing quality of life is often a major priority.
Accommodation Costs
In cities such as Ho Chi Minh City or Da Nang, retirees can rent modern apartments for significantly less than comparable accommodation in Bangkok or Phuket.
Typical Monthly Rent
| Property Type | Vietnam | Thailand |
|---|---|---|
| Modern 1-bedroom apartment | £350–£700 | £500–£1,000 |
| Luxury city apartment | £900–£1,800 | £1,200–£2,500 |
| Coastal apartment | £400–£900 | £700–£1,500 |
Vietnam’s property market remains highly competitive, especially outside premium districts.
For retirees looking to maintain a comfortable lifestyle while preserving pension capital, Vietnam frequently delivers stronger value for money.
Daily Living Expenses
Dining out, transportation, groceries, and domestic services are generally cheaper in Vietnam.
A retired couple living in Vietnam comfortably may spend approximately:
£1,500–£2,500 per month in total
Including rent, dining, utilities, healthcare, and entertainment
In Thailand, the equivalent lifestyle often costs:
- £2,000–£3,500 per month
Of course, lifestyle choices matter enormously. Coastal villas, international schools for dependants, imported products, and luxury travel can increase costs substantially in either country.
Visa and Residency Options
Visa regulations remain one of the biggest deciding factors in the Vietnam vs Thailand for UK retirees debate.
Vietnam’s Current Position
Vietnam currently approaches long-term residency quite differently from Thailand. Unlike its neighbour, Vietnam does not yet offer a formal retirement visa specifically designed for foreign retirees. However, this does not mean retirement in Vietnam is impractical, far from it. In reality, many long-term expats successfully establish legal residency through alternative visa structures depending on their personal circumstances and financial objectives.
Common residency pathways include investor visas, business-related temporary residence cards, spousal visas, or arrangements linked to locally registered companies. Some retirees also choose to divide their time between Vietnam and neighbouring countries while utilising renewable visas, although this approach requires careful compliance with immigration regulations as policies continue evolving.
For financially established retirees, investment-related residency can sometimes provide one of the more stable options. For example, certain levels of business investment may qualify applicants for longer-duration residence cards, reducing the frequency of visa renewals and allowing greater day-to-day stability. While the precise requirements depend on the investment structure and prevailing regulations, many expats find Vietnam’s system workable when guided appropriately by qualified legal and financial professionals.
In practice, Vietnam often appeals to retirees who are slightly more internationally experienced or comfortable navigating emerging-market environments. The administrative processes can occasionally feel less streamlined than Thailand’s, particularly for first-time expats unfamiliar with Southeast Asian bureaucracy. However, many retirees find the trade-off worthwhile due to Vietnam’s significantly lower living costs, strong economic growth, and increasingly sophisticated urban infrastructure.
Additionally, Vietnam’s long-term outlook remains particularly attractive from an economic perspective. The country continues experiencing rapid infrastructure development, foreign investment growth, and rising international demand. As Vietnam becomes increasingly integrated into the global economy, many expats believe residency frameworks will continue modernising to accommodate growing international interest.
Thailand’s Retirement Visa Advantage
Thailand has spent many years positioning itself as one of Asia’s most retirement-friendly destinations, and this is reflected in its relatively structured visa system for older expats. For UK retirees over the age of 50, the most common route is the Non-Immigrant O-A Retirement Visa, which allows long-term residency provided applicants meet specific financial and administrative requirements.
At present, retirees typically need to demonstrate either a monthly income of at least approximately £1,500–£1,700 equivalent, maintain around £18,000 in a Thai bank account for a prescribed period, or use a combination of income and savings to satisfy immigration rules. In addition, applicants must obtain qualifying health insurance and complete annual renewals alongside periodic immigration reporting requirements.
While these financial thresholds may initially appear straightforward, retirees should also factor in practical considerations beyond the headline figures. For example, maintaining cash reserves in Thai bank accounts may expose individuals to currency fluctuations between pound sterling and the Thai baht over time. A retiree relying on a fixed UK pension income may therefore find their effective purchasing power changing year by year depending on exchange rate movements.
Furthermore, Thailand’s visa regulations have evolved repeatedly over the years, with adjustments to financial requirements, insurance obligations, and reporting procedures becoming increasingly common. As such, retirees should avoid assuming that current visa conditions will necessarily remain unchanged over the long term.
That said, Thailand still offers one of the clearest retirement pathways in Southeast Asia. For retirees who value administrative familiarity, established expat support services, and a well-developed retirement ecosystem, Thailand remains highly attractive. Areas such as Hua Hin and Chiang Mai, in particular, have become popular due to their sizeable retiree communities, slower pace of life, and access to healthcare infrastructure tailored towards foreign residents.
Healthcare Comparison
Healthcare quality is understandably a major concern for retirees.
The good news is that both Vietnam and Thailand offer excellent private healthcare options at costs far below those in the UK.
Vietnam’s Rapid Improvement
Vietnam’s healthcare system has evolved remarkably over the past decade, particularly within its major urban centres. While the country may not yet possess the same international medical tourism reputation as Thailand, the quality of private healthcare available in cities such as Ho Chi Minh City and Hanoi has improved substantially and continues advancing rapidly.
Many expats are pleasantly surprised by the standard of care available at Vietnam’s leading international hospitals and clinics. Facilities such as FV Hospital, Vinmec International Hospital, and Family Medical Practice provide modern equipment, internationally trained physicians, English-speaking medical staff, and increasingly efficient patient care systems.
For day-to-day healthcare needs, many retirees find Vietnam both highly convenient and cost-effective. Routine consultations, blood tests, diagnostics, dental work, and outpatient treatments are often available quickly and at comparatively low cost. In some cases, retirees report receiving same-day specialist appointments that would involve considerably longer waiting periods elsewhere.
Financially, Vietnam often offers even stronger value than Thailand. A standard private GP consultation may cost between £15–£40, while dental treatment, physiotherapy, and preventative healthcare services can be significantly cheaper than equivalent private options in the UK. For retirees living on fixed pension income, these lower ongoing healthcare costs can make a meaningful difference over a long retirement period.
At the same time, it is important to acknowledge Vietnam’s current limitations objectively. Outside major cities, healthcare standards can vary considerably, and more complex medical cases may still require treatment in larger urban centres or occasionally overseas. Retirees considering quieter provincial areas should therefore evaluate proximity to international-standard hospitals carefully before relocating.
That said, Vietnam’s healthcare trajectory remains extremely positive. The country continues investing heavily in private medical infrastructure as international demand increases and rising local incomes drive healthcare expansion. In major expat hubs such as Ho Chi Minh City and Da Nang, healthcare quality today is already far ahead of where it stood only ten years ago.
Thailand’s Healthcare Reputation
Thailand has built an international reputation as one of the world’s leading medical tourism destinations. Over the past two decades, the country has invested heavily in private healthcare infrastructure, resulting in hospitals and specialist clinics that attract patients from Europe, the Middle East, Australia, and across Asia.
Bangkok in particular is home to several internationally accredited hospitals that many UK retirees find reassuringly familiar in terms of service standards, equipment quality, and patient experience. Facilities such as Bumrungrad International Hospital, Bangkok Hospital, and Samitivej Hospital offer multilingual staff, internationally trained doctors, modern diagnostic technology, and streamlined appointment systems designed specifically for international patients.
One of Thailand’s strongest advantages is consistency across multiple regions. Retirees living not only in Bangkok, but also in Chiang Mai, Phuket, Pattaya, or Hua Hin can generally access reputable private hospitals relatively easily. This becomes especially valuable for retirees who prefer coastal or quieter retirement locations while still wanting dependable healthcare nearby.
In practical financial terms, private healthcare in Thailand remains significantly less expensive than equivalent private treatment in the UK. For example, a private specialist consultation may cost approximately £30–£80, while advanced imaging such as MRI scans can often be arranged for a fraction of UK private-sector pricing. Even more substantial procedures, including elective surgeries, frequently cost far less than many retirees anticipate.
However, healthcare costs should still be approached carefully. As retirees age, long-term medical expenses can rise substantially, particularly for chronic illnesses or ongoing specialist care. Comprehensive international health insurance therefore remains highly advisable regardless of destination. Thailand’s visa system itself increasingly incorporates health insurance requirements, reinforcing the importance of proper long-term planning rather than relying solely on out-of-pocket affordability.
Another consideration is that Thailand’s popularity among retirees and tourists has contributed to rising healthcare pricing in certain premium private hospitals. While still affordable by UK standards, top-tier facilities in Bangkok may now charge rates closer to international private healthcare benchmarks than they did a decade ago.
Lifestyle and Culture
Lifestyle preferences often become the deciding factor when comparing Vietnam vs Thailand for UK retirees.
Vietnam: Energetic, Authentic, and Fast-Growing
Vietnam offers a very different atmosphere from Thailand. Rather than feeling primarily tourism-driven, Vietnam often feels dynamic, entrepreneurial, and deeply connected to its local culture and economic momentum.
For many expats, this energy becomes one of the country’s most appealing characteristics.
Cities such as Ho Chi Minh City, Hanoi, and Da Nang combine modern development with strong cultural identity, creating an environment that feels both internationally connected and distinctly Vietnamese. Rather than retiring into a purely resort-oriented lifestyle, many retirees in Vietnam feel immersed in a country that is actively evolving and expanding around them.
This sense of growth is visible across nearly every aspect of life. New infrastructure projects, modern apartment developments, expanding international dining scenes, and improving transport systems continue reshaping Vietnam’s major cities at remarkable speed. At the same time, traditional street markets, local cafés, and strong family-oriented culture remain deeply embedded in everyday life.
For retirees who enjoy authenticity, local interaction, and cultural immersion, Vietnam can feel particularly rewarding.
Food culture also plays a major role in Vietnam’s lifestyle appeal. Fresh ingredients, healthy cuisine, vibrant café culture, and affordable dining make everyday living both enjoyable and cost-effective. Many retirees quickly adapt to regularly eating out due to the combination of quality and affordability.
For example, in Ho Chi Minh City or Da Nang, retirees can comfortably enjoy regular restaurant dining, domestic help, gym memberships, and modern apartment living while still maintaining lower monthly expenditure than in many comparable Thai expat areas.
Vietnam also tends to attract a slightly different expat demographic. While Thailand has larger retiree populations overall, Vietnam’s expat community often includes entrepreneurs, professionals, remote workers, and internationally mobile individuals drawn by the country’s economic growth and business opportunities. As a result, some retirees find Vietnam’s international community feels particularly active and forward-looking.
Financially, Vietnam’s affordability remains one of its strongest advantages. A retiree couple living comfortably in Ho Chi Minh City or Da Nang may maintain a high-quality lifestyle for approximately £2,000–£2,500 per month, including modern accommodation, dining, domestic travel, and private healthcare. Over a retirement period spanning 20 or 25 years, these lower ongoing costs can substantially improve financial sustainability and preserve investment capital for future needs.
For retirees seeking a balance between affordability, cultural depth, modern urban living, and long-term economic optimism, Vietnam increasingly stands out as one of Asia’s most compelling retirement destinations.
Thailand: Relaxed and Tourism-Friendly
Thailand has long been one of the world’s most established retirement destinations, and this is immediately apparent in how accessible the country feels to foreign residents. Decades of international tourism and expat migration have created an environment where many retirees can settle relatively quickly with minimal cultural adjustment.
In practical terms, this means retirees often benefit from:
Widespread English usage in tourist and expat areas
Well-developed international amenities
Large foreign communities
Extensive Western dining and shopping options
Mature tourism and hospitality infrastructure
For many UK retirees, particularly those relocating abroad for the first time, this familiarity can provide reassurance and ease the transition into retirement overseas.
Popular retirement locations such as Hua Hin, Chiang Mai, Phuket, and Pattaya each offer distinct lifestyles. Hua Hin, for example, is known for its quieter atmosphere and sizeable retiree population, while Chiang Mai appeals to those seeking a slower pace of life, mountain scenery, and lower living costs compared with Bangkok. Phuket attracts retirees looking for beach-oriented luxury living, although naturally at higher overall costs.
Thailand’s culture itself is often described as relaxed, service-oriented, and highly accommodating towards foreign visitors. The country’s hospitality sector is exceptionally well developed, which means retirees can often enjoy a comfortable lifestyle with relatively little friction in day-to-day living.
However, this accessibility can occasionally create a trade-off. In some heavily touristic areas, parts of Thailand may feel somewhat commercialised or detached from authentic local culture, particularly in districts dominated by short-term tourism. Some retirees enjoy this convenience, while others eventually seek a deeper sense of local integration and cultural immersion.
Cost also plays an important role. Although Thailand remains affordable compared with the UK, prices in major expat hubs have risen steadily over the years. Premium coastal areas and central Bangkok, in particular, now command significantly higher accommodation and lifestyle costs than many retirees initially anticipate.
Climate Comparison
Climate plays a far greater role in retirement planning than many people initially expect. While warm weather is often one of the main reasons UK retirees consider Southeast Asia in the first place, long-term comfort depends on much more than simply escaping British winters.
When comparing Vietnam vs Thailand for UK retirees, climate preferences are therefore highly personal.
Fortunately, both countries offer appealing climates, although in very different ways.
Vietnam: Greater Diversity and Regional Choice
Vietnam offers a much more geographically diverse climate than Thailand, largely due to the country’s long north-to-south shape stretching across multiple climate zones.
This diversity gives retirees significantly greater flexibility in choosing the type of environment that suits them best.
Rather than experiencing a single broadly tropical climate nationwide, Vietnam offers several distinct regional weather patterns:
Northern Vietnam experiences four seasons
Central Vietnam combines coastal tropical weather with seasonal variation
Southern Vietnam remains warm year-round with wet and dry seasons
For many retirees, this variety becomes one of Vietnam’s most underrated advantages.
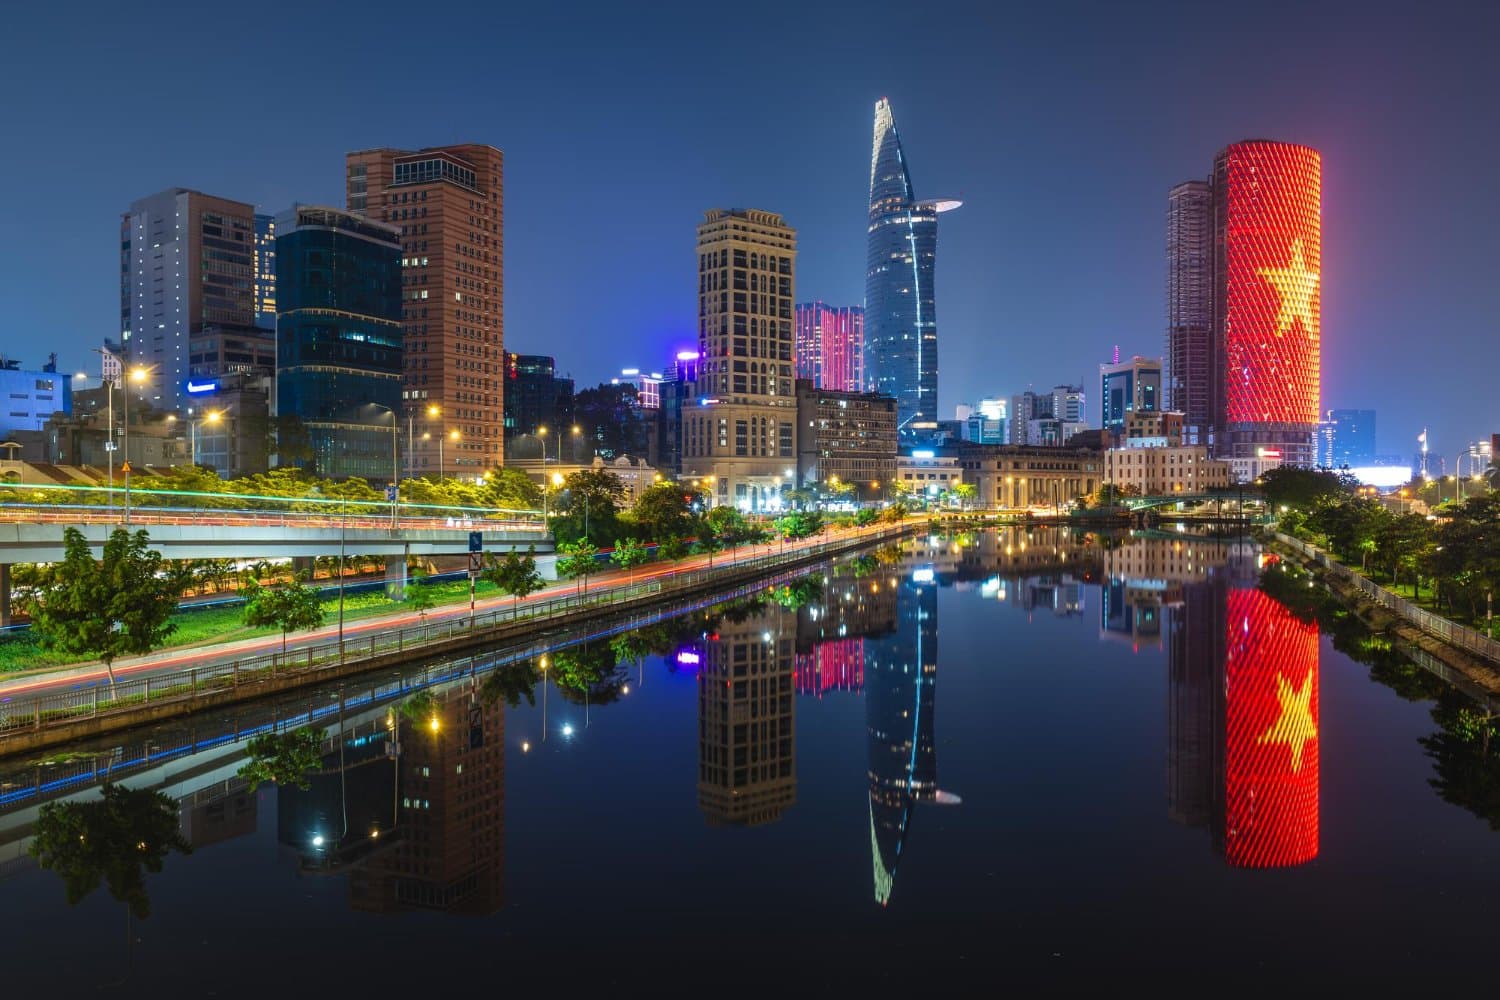
In southern cities such as Ho Chi Minh City, the climate remains consistently warm throughout the year, with temperatures typically ranging between 27°C and 35°C. The city experiences a dry season and a rainy season, although rainfall often arrives in short heavy bursts rather than prolonged all-day storms. Many expats adapt quickly to this rhythm and continue daily activities with little disruption.
Meanwhile, central coastal cities such as Da Nang and Hoi An offer a balance that many retirees find particularly attractive. These areas provide warm beach-oriented living while still experiencing slightly milder seasonal shifts compared with southern Vietnam or southern Thailand. As a result, retirees often describe central Vietnam as feeling more balanced and comfortable for long-term living.
Northern Vietnam offers yet another entirely different experience. Hanoi, for example, experiences cooler winters that can occasionally feel surprisingly crisp compared with the rest of Southeast Asia. For some UK retirees, this seasonal variation feels more familiar and psychologically comfortable than year-round tropical heat.
This regional flexibility allows retirees to choose environments aligned with both personal comfort and lifestyle goals. Some retirees prefer the year-round warmth and energy of Ho Chi Minh City, while others gravitate towards Da Nang’s coastal atmosphere or Hanoi’s more seasonal climate.
Another important consideration is lifestyle compatibility. Vietnam’s climate diversity also supports a wider range of activities and travel experiences. Retirees can enjoy beaches, mountain regions, cooler countryside escapes, and urban living all within the same country, often connected through affordable domestic travel.

Financially, climate can indirectly influence retirement costs here as well. For example, retirees living in coastal resort areas of Thailand may face considerably higher accommodation costs than retirees enjoying comparable coastal lifestyles in Da Nang or Nha Trang. Over time, these differences can significantly affect retirement budgets and long-term financial sustainability.
Of course, Vietnam is not without environmental considerations. Certain regions experience typhoon seasons, particularly in central coastal areas, while major cities can occasionally face air quality challenges linked to rapid urban growth and development. Nevertheless, many expats feel the country’s regional diversity ultimately provides more flexibility and lifestyle customisation than Thailand’s more uniformly tropical environment.
For UK retirees seeking climate variety alongside affordability and lifestyle flexibility, Vietnam offers an unusually broad range of options within a single country. This ability to choose between tropical city living, coastal relaxation, or more seasonal northern environments often becomes increasingly valuable over the course of a long retirement abroad.
Thailand: Consistently Tropical and Predictable
Thailand is best known for its tropical climate, with warm temperatures throughout most of the year across the majority of the country. For many UK retirees, this consistency is one of Thailand’s strongest lifestyle advantages, particularly for those looking to avoid cold weather permanently.
Most of Thailand experiences three broad seasons:
Hot season
Rainy season
Cooler dry season
Even during the “cooler” months, temperatures in many areas remain comfortably warm by UK standards. In Bangkok, daytime temperatures frequently range between 28°C and 35°C for much of the year, while southern coastal regions such as Phuket and Krabi remain warm and humid almost continuously.
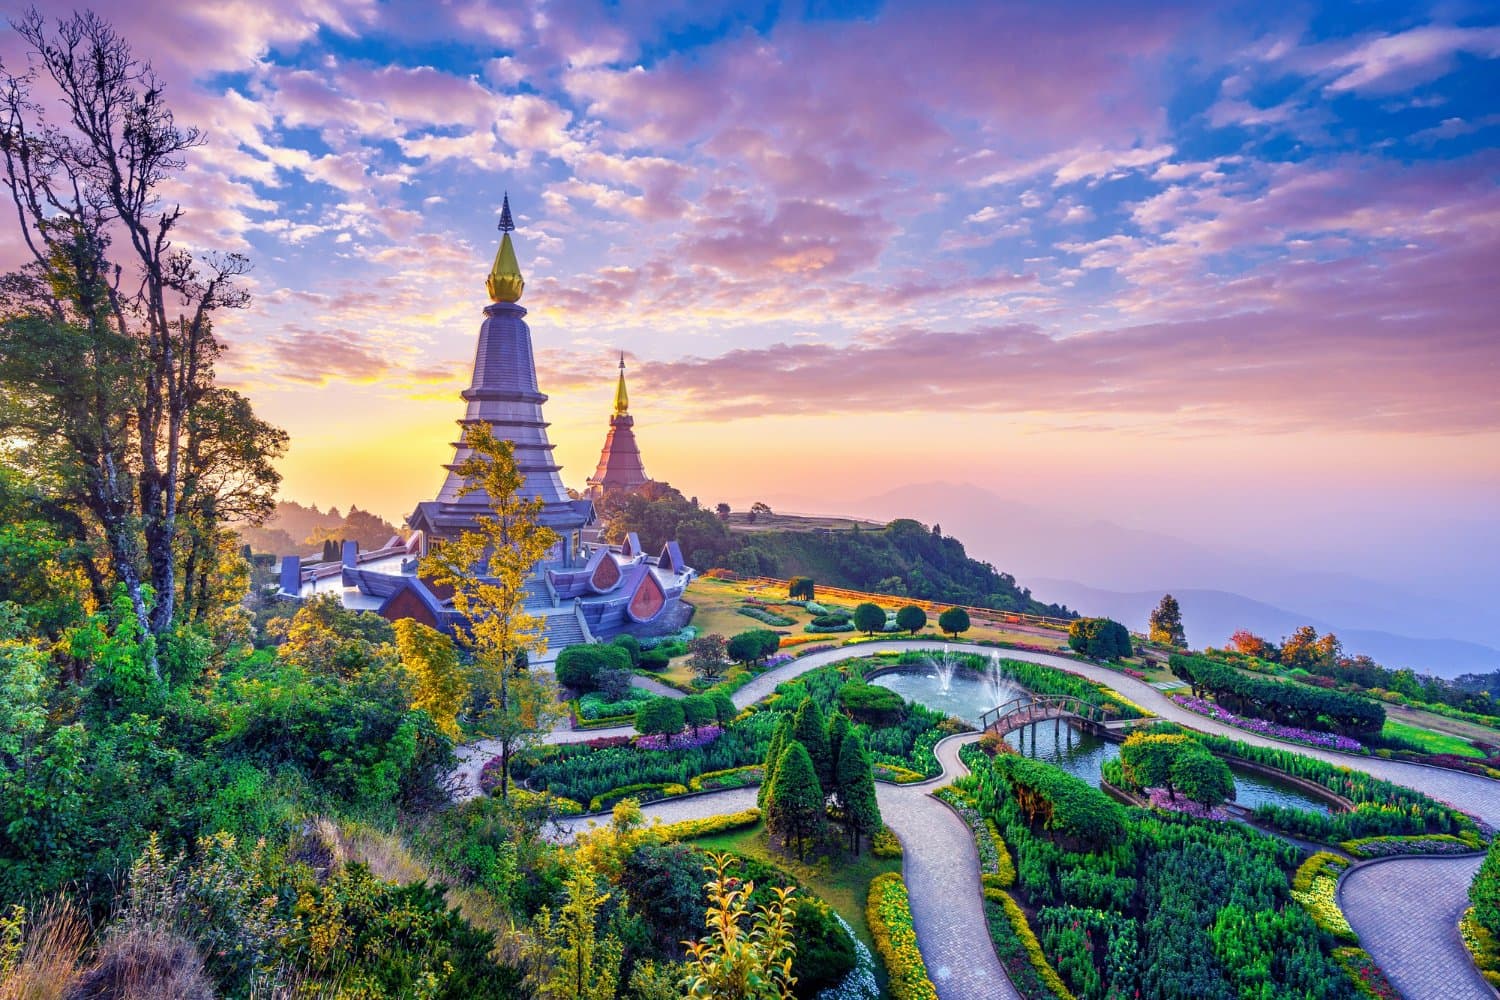
For retirees who enjoy beach living, outdoor dining, swimming, golf, or an active social lifestyle, Thailand’s predictable warmth can be highly appealing. Coastal areas in particular attract retirees seeking resort-style living combined with easy access to restaurants, cafés, and international amenities.
However, the tropical climate also comes with practical considerations. Humidity can feel intense, especially during the rainy season, and some retirees may find constant heat physically tiring over time. Air conditioning therefore becomes less of a luxury and more of a daily necessity, particularly during hotter months.
Additionally, regional climate differences matter more than many newcomers realise. Northern cities such as Chiang Mai experience a slightly cooler and more seasonal climate compared with Bangkok or southern Thailand, which is one reason many retirees favour the region. However, northern Thailand can also experience seasonal air pollution and agricultural burning periods that may affect individuals with respiratory sensitivities.
Rainfall patterns are another important consideration. Thailand’s monsoon season can bring periods of heavy rain and flooding in some regions, particularly between May and October depending on location. While this rarely disrupts daily life significantly in major urban centres, retirees should still consider seasonal weather patterns carefully before committing to long-term accommodation or property purchases.
From a financial perspective, climate also affects living costs more than many retirees expect. Constant air-conditioning use, particularly in larger apartments or villas, can noticeably increase monthly electricity bills over time. Similarly, retirees choosing premium beachfront locations often face substantially higher rental costs compared with inland cities.
Property Ownership and Investment
When comparing Vietnam vs Thailand for UK retirees, property ownership is an area where expectations must be approached carefully. Neither country operates under the same legal framework as the UK, and foreign ownership rules can differ significantly from what many retirees are accustomed to back home.
That said, both Vietnam and Thailand offer viable pathways for foreign residents to purchase certain types of property, particularly condominiums and apartments, provided buyers understand the legal structures involved and conduct proper due diligence.
Vietnam: Earlier Growth Cycle with Long-Term Potential
Vietnam’s property market differs significantly from Thailand’s in both structure and stage of development. While Thailand’s market is relatively mature and internationally established, Vietnam remains earlier in its long-term growth cycle, which is one reason many expats and investors find it increasingly attractive.
Foreigners in Vietnam are generally permitted to purchase apartments within approved developments under leasehold arrangements, commonly for periods of up to 50 years with potential renewal options depending on prevailing regulations. Similar to Thailand, direct foreign ownership of land itself remains restricted.
In practical terms, this means most foreign retirees purchasing property in Vietnam focus on condominiums or apartments within modern residential developments, particularly in major cities such as Ho Chi Minh City, Hanoi, and Da Nang.
What makes Vietnam especially interesting from an investment perspective is the country’s broader economic trajectory. Rapid urbanisation, infrastructure expansion, rising middle-class incomes, and sustained foreign direct investment have all contributed to significant growth across Vietnam’s real estate sector over the past decade.
For retirees who intend to remain long term, this creates potential opportunities not only for lifestyle affordability but also for capital appreciation over time.
For example, high-quality modern apartments in central districts of Ho Chi Minh City may still cost substantially less than comparable properties in Bangkok or Singapore despite Vietnam’s strong long-term economic growth outlook. This relative affordability allows some retirees to access modern city-centre living at considerably lower entry points than in many other Asian capitals.
At the same time, Vietnam’s property market still requires careful navigation. Regulations can evolve, legal processes may occasionally feel less transparent than in more mature markets, and project quality can vary significantly between developers. Thorough due diligence therefore becomes particularly important.
Retirees should pay close attention to:
Developer reputation
Ownership structures
Leasehold terms
Maintenance fees
Construction quality
Location fundamentals
Exit liquidity
Working with experienced legal advisers and independent financial professionals is highly advisable before making commitments.
One major advantage Vietnam currently offers is lower overall carrying costs. In many cases, retirees can rent high-quality accommodation at such competitive prices that purchasing property may not always make immediate financial sense. For example, a luxury apartment in Ho Chi Minh City that might cost several hundred thousand pounds to purchase could potentially be rented for £800–£1,500 per month depending on location and specification.
This creates flexibility for retirees who prefer preserving liquidity and maintaining mobility rather than tying substantial capital into overseas property immediately.
Over a long retirement horizon, this flexibility can prove extremely valuable. Economic conditions, visa policies, healthcare needs, family circumstances, and currency dynamics can all change considerably over time. Renting initially before committing to property ownership often allows retirees to better understand local markets and lifestyle preferences before making major financial decisions.
Thailand: Established but Increasingly Mature
Thailand has long attracted international property buyers, particularly in areas with strong tourism and expat demand such as Bangkok, Phuket, Pattaya, and Hua Hin. As a result, the country’s foreign property ownership framework is relatively well established and familiar to many international investors.
Under Thai law, foreigners are generally permitted to own condominium units outright provided foreign ownership within the building does not exceed prescribed quota limits. This structure has made condominiums one of the most common property choices for foreign retirees.
However, direct foreign ownership of land remains heavily restricted. As a result, retirees considering villas or standalone homes often encounter more complex arrangements involving long-term leases or company structures, each carrying varying levels of legal and financial risk.
For retirees prioritising simplicity and legal clarity, condominiums are typically the safer and more straightforward route.
Thailand’s mature property market offers several practical advantages. Retirees can often choose from:
Well-developed residential infrastructure
Large inventories of modern condominiums
Established expat-oriented neighbourhoods
Professional property management services
Strong short-term rental markets in tourist areas
This maturity creates a sense of familiarity and convenience that many retirees appreciate.
However, market maturity also means that growth potential in some areas may be more moderate compared with emerging markets. Prime locations in Bangkok and Phuket, for example, have already experienced substantial appreciation over previous decades, and property prices in certain premium areas now resemble those of developed international cities more than many retirees expect.
Rental yields can also vary considerably depending on location and tourism cycles. Properties heavily reliant on short-term tourism demand may experience periods of vacancy during economic downturns or shifts in travel patterns, as seen globally during recent years.
From a financial planning perspective, retirees should also carefully consider currency exposure. Purchasing Thai property using pound sterling-denominated retirement income introduces long-term exchange rate considerations between GBP and the Thai baht. Even relatively modest currency fluctuations over a 15–20 year retirement period can meaningfully affect affordability, maintenance costs, and eventual resale values when converted back into sterling.
For example, a property purchased for the equivalent of £150,000 today may become considerably more expensive in sterling terms if the baht strengthens materially over time. Conversely, future resale proceeds may fluctuate significantly depending on currency movements at the point of sale.
Tax Considerations for UK Retirees
Tax planning is one of the most important, and often most underestimated, aspects of retiring abroad. Many UK retirees naturally focus first on lifestyle factors such as climate, healthcare, accommodation, and cost of living, yet long-term financial outcomes are frequently shaped far more by how effectively retirement income, pensions, investments, and assets are structured internationally.
When comparing Vietnam vs Thailand for UK retirees, taxation should never be viewed as a simple question of “which country has lower tax rates”. In reality, cross-border retirement planning involves multiple overlapping considerations, including:
UK tax residency status
Local tax residency rules
Pension taxation
Investment income
Capital gains exposure
Currency management
Inheritance and succession planning
Double taxation agreements
Crucially, individual circumstances differ enormously. A retiree relying solely on a UK State Pension may face very different planning considerations from someone drawing income from SIPPs, property portfolios, offshore investments, or multiple international pension arrangements.
As such, retirees should avoid relying on general assumptions or online commentary when making decisions. Proper professional advice becomes increasingly valuable once retirement income crosses borders.
Understanding UK Tax Residency
One of the first considerations for retirees moving overseas is determining whether they remain UK tax resident after relocation.

This is particularly important because UK tax residency status influences how worldwide income may be taxed and reported. The UK’s Statutory Residence Test assesses factors such as:
Number of days spent in the UK
Ties to the UK
Accommodation availability
Family connections
Work activity
Many retirees incorrectly assume that simply leaving the UK automatically ends UK tax obligations. In practice, residency status can become more nuanced, especially for individuals who continue spending significant time in Britain each year or maintain substantial financial interests there.
For example, a retiree spending extended periods visiting family in the UK while maintaining overseas residency may still trigger UK tax residency depending on the number of days spent back home and the strength of their remaining UK ties.
This matters because UK tax residency may affect:
Pension taxation
Investment income reporting
Capital gains treatment
Inheritance planning
Offshore account disclosure obligations
Careful planning before relocation can therefore help avoid unintended tax complications later.
Vietnam’s Tax Framework for Expats
Vietnam’s tax environment can initially appear more administrative and less familiar to foreign retirees than Thailand’s, particularly because Vietnam does not yet possess the same long-established retirement expat infrastructure.
However, many long-term foreign residents successfully manage their affairs efficiently with appropriate planning and professional guidance.
Vietnam generally considers individuals tax resident if they spend 183 days or more in the country within a 12-month period or establish qualifying permanent residency arrangements. Tax residency may result in worldwide income becoming subject to Vietnamese taxation, although practical application depends heavily on income source, residency structure, and applicable international agreements.
Importantly, Vietnam also maintains a double taxation agreement with the UK, which helps reduce the likelihood of double taxation on the same income streams. Nevertheless, understanding how pensions, offshore investments, and international assets interact with local reporting obligations remains highly important.
For retirees living in Vietnam, common planning considerations may include:
UK pension withdrawals
Offshore investment structures
International bank accounts
Property income from the UK
Foreign exchange transfers
Long-term estate planning
Vietnam’s regulatory environment continues evolving as the country becomes increasingly integrated into the global financial system. As such, retirees should expect reporting standards and compliance expectations to continue modernising over time.
At the same time, Vietnam’s lower overall living costs can significantly improve retirement sustainability from a financial planning perspective.
For example, consider two retired couples each drawing £45,000 annually from pensions and investment income:
A couple living in premium areas of Bangkok or Phuket may spend £36,000–£42,000 annually maintaining a comfortable international lifestyle.
A comparable couple living comfortably in Ho Chi Minh City or Da Nang may spend closer to £24,000–£30,000 annually.
Over a 20-year retirement period, this difference could potentially preserve several hundred thousand pounds in investment capital depending on inflation, healthcare costs, and portfolio growth assumptions.
This becomes particularly important when managing longevity risk — the possibility of outliving retirement assets. Lower annual expenditure can reduce portfolio withdrawal pressure, improve investment sustainability, and create greater financial flexibility later in life.
Additionally, Vietnam’s comparatively lower costs may allow retirees to allocate more towards:
International health insurance
Emergency reserves
Estate planning
Family gifting strategies
Long-term investment growth
rather than directing a disproportionate share of income purely towards daily living expenses.
Thailand’s Tax Environment for Retirees
Thailand has historically been viewed as relatively favourable for retirees from a taxation perspective, although recent developments have increased international attention on how foreign-sourced income may be treated.
Under Thai tax rules, individuals who spend 180 days or more in Thailand during a calendar year are generally considered Thai tax residents. Historically, many foreign retirees structured finances around the principle that foreign income remitted into Thailand in a different tax year from when it was earned could avoid local taxation. However, evolving interpretations and enforcement priorities have made the situation more complex in recent years.
As a result, retirees relying on overseas pensions, investment income, or offshore portfolio withdrawals should monitor developments carefully rather than relying on outdated assumptions.
Thailand does maintain a double taxation agreement with the UK, which can help mitigate the risk of the same income being taxed twice. However, the interaction between UK pensions, Thai residency rules, and offshore income structures often requires case-by-case analysis.
For example, a UK retiree drawing:
UK State Pension income
SIPP withdrawals
Dividend income from investments
Rental income from UK property
may potentially face multiple reporting and planning considerations depending on how and when funds are transferred internationally.
Currency strategy also becomes increasingly important over time. Many retirees receive income in pound sterling while spending predominantly in Thai baht. Significant exchange-rate fluctuations can materially affect purchasing power over a retirement period lasting 20 or 30 years.
This is why many internationally mobile retirees benefit from coordinated financial planning that integrates taxation, currency management, investment structuring, and withdrawal strategy together rather than treating each issue separately.
Which Country Is Better for UK Retirees?
The answer of which country is better for your overseas retirement depends entirely on your priorities.
Vietnam May Suit You Better If:
You prioritise lower living costs
You enjoy dynamic urban environments
You prefer authentic local culture
You are comfortable with emerging-market growth
You value long-term affordability
You want access to one of Asia’s fastest-growing economies
Thailand May Suit You Better If:
You want a straightforward retirement visa
You prefer larger expat communities
You value established tourism infrastructure
You prioritise beach resort living
You want broader English usage
Increasingly, many retirees are finding Vietnam offers a compelling balance between affordability, lifestyle, modern infrastructure, and long-term opportunity.
While Thailand remains highly attractive, Vietnam’s rapid development and comparatively lower costs continue drawing growing numbers of expats from the UK and Europe.
Financial Planning for Retirement Abroad With Benjamin Sharvell
Retiring abroad involves far more than choosing where to live. Pensions, investments, taxation, healthcare costs, currency exposure, and estate planning all become increasingly important when managing wealth internationally.
As a globally experienced financial adviser specialising in wealth management for expat clients, I help individuals and families structure their finances with confidence while living overseas. My approach is pragmatic, personalised, and focused on long-term financial security.
I assist expat clients with:
Retirement & Future Planning: including retirement planning, pension planning, succession planning, and education fee planning.
Savings Solutions: helping clients manage regular savings, lump sum investments, offshore banking, and foreign exchange considerations.
Pension Solutions: including UK pensions, SIPPs, QROPS, QNUPS, and international pension arrangements.
Property Solutions: supporting clients with property investments, UK mortgages, and international mortgages.
Insurance Solutions: helping expats arrange suitable health and life insurance protection.
Whether you are planning retirement in Vietnam, Thailand, or elsewhere abroad, careful financial planning can help reduce complexity and support long-term financial stability.
Vietnam vs Thailand for UK Retirees
Both Vietnam and Thailand offer excellent retirement opportunities for UK expats.
Thailand provides familiarity, established retirement infrastructure, and convenience. Vietnam offers exceptional value, strong economic growth, vibrant culture, and increasingly sophisticated urban living.
For retirees seeking affordability without sacrificing lifestyle quality, Vietnam has become one of the most compelling destinations in Asia.
Ultimately, the right choice depends on your financial position, lifestyle preferences, healthcare priorities, and long-term retirement objectives.
Get in touch with us today and get a free consultation to a stress-free retirement plan in Vietnam!