
Relocating abroad for retirement is no longer a niche aspiration; it has become a strategic lifestyle and financial decision for many UK nationals. As an adviser who works closely with expat clients and has lived overseas myself, I see both the opportunities and the pitfalls. Choosing the best places to retire as an expat is not about chasing sunshine or the lowest rent. It comes down to five things that actually shape a retirement: cost of living, healthcare access, tax on your pension, residency rules and long-term financial planning.
Two of those five are missed by almost every “best places to retire” list, and they are the ones a financial adviser cares about most: whether your UK State Pension keeps rising once you move (many countries freeze it), and how much tax you will pay on your pension income once you get there. Those two factors can be worth tens of thousands of pounds over a retirement, so I have flagged them for every destination below. If you are still deciding whether to make the move at all, our guide on how to retire abroad walks through the process step by step.
Key Takeaways
The best place to retire as an expat depends on your priority: lowest cost, lowest pension tax, easiest healthcare, or staying close to the UK.
Lowest cost: Bulgaria, Turkey, Vietnam and Thailand, where couples can live well on roughly £700 to £1,500 per month.
Lowest tax on your pension: Cyprus (elect a flat 5%) and Greece (flat 7% for 15 years); Costa Rica does not tax foreign pension income at all.
Uprated UK State Pension: Portugal, Spain, Greece, Cyprus, France, Bulgaria and (unusually for a non-EU country) Turkey.
Frozen UK State Pension: Vietnam, Thailand, Malaysia, Mexico and Costa Rica, so plan private income to fill the gap.
Healthcare: in the EU and EEA, UK State Pension recipients can use the S1 form for public healthcare; outside it, private cover is essential and often required for the visa.
Portugal's old NHR pension tax break has closed to new applicants, so it is no longer the automatic tax winner it once was.
How We Ranked the Best Places to Retire as an Expat
Rather than chase headlines, each destination below is assessed against the factors that decide whether a retirement abroad actually works for a UK national:
Cost of living: a realistic monthly budget in pounds, not rough estimates.
Healthcare: quality, S1 eligibility and the cost of private cover.
UK State Pension: whether it is uprated each year or frozen at the rate you first receive.
Pension and income tax: how your pension is taxed locally, and any favourable regime.
Residency route: the retirement or long-stay visa available in 2026 and its income requirement.
Lifestyle and community: climate, safety, English use and the size of the expat network.
Best Places to Retire as an Expat at a Glance
Indicative monthly budgets for a couple; they vary widely by city and lifestyle. Verify pension, tax and visa positions before you move.
| Country | Budget (couple) | State Pension | S1? | Retirement visa route | Pension / tax note |
|---|---|---|---|---|---|
| Vietnam | £900 to £1,500 | Frozen | No | No retirement visa; TRC via business | Plan private income for the freeze |
| Portugal | £1,200 to £2,000 | Uprated | Yes | D7 (pension/passive income) | NHR closed; standard rates now |
| Spain | £1,300 to £2,200 | Uprated | Yes | Non-Lucrative Visa | Progressive; can be high |
| Thailand | £800 to £1,500 | Frozen | No | Non-O retirement (50+) or LTR | Low cost offsets frozen pension |
| Malaysia | £1,000 to £1,800 | Frozen | No | MM2H programme | Broadly territorial tax |
| Mexico | £900 to £1,700 | Frozen | No | Temporary/Permanent residency | Foreign income lightly taxed |
| Costa Rica | £1,200 to £2,000 | Frozen | No | Pensionado visa | No tax on foreign pensions |
| Greece | £1,200 to £1,800 | Uprated | Yes | Financially Independent Person visa | Flat 7% pension tax, 15 years |
| Turkey | £700 to £1,400 | Uprated | No | Short-term residence permit | Uprated (rare); currency risk |
| Cyprus | £1,300 to £2,100 | Uprated | Yes | Category F / residency by income | Elect flat 5% pension tax |
| France | £1,500 to £2,500 | Uprated | Yes | Long-stay visitor visa (VLS-TS) | Top-ranked healthcare |
| Bulgaria | £700 to £1,200 | Uprated | Yes | Type D long-stay visa | Flat 10% income tax |
1. Vietnam
Vietnam has rapidly positioned itself as one of the best places to retire as an expat, particularly for UK retirees seeking a balance between affordability, quality of life, and cultural richness.
Below, I’ve expanded on the key areas you should consider, with practical guidance to help you make informed decisions.
Cost of Living: Structuring a Comfortable Retirement Budget
One of Vietnam’s strongest advantages is its low cost of living, but it’s important to approach this with a structured budget rather than rough estimates.
In practical terms, most of my clients find they can live comfortably on £900–£1,500 per month, though this depends heavily on lifestyle choices and location. For example, living in central Ho Chi Minh City will naturally cost more than residing in Da Nang or a smaller coastal town.
To give you a clearer breakdown:
Accommodation
Modern one-bedroom apartment (city centre): £350–£700/month
Serviced apartment with amenities: £600–£1,000/month
Tip: Negotiate long-term leases (6–12 months) for better rates
Food and Dining
Local meals: £1.50–£3 per dish
Western restaurants: £8–£20 per meal
Monthly grocery spend: £100–£250
Example: Many expats mix local dining with occasional Western meals to maintain both cost efficiency and comfort
Utilities and Services
Electricity, water, internet: £50–£120/month
Domestic help (cleaning): £20–£50/month
Transport
Ride-hailing apps (e.g. Grab): £1–£5 per journey
Monthly transport budget: ~£30–£80
Practical advice: Set up a UK-based income stream (pensions, investments) and consider using a foreign exchange service to manage currency conversions efficiently. Small fluctuations in GBP/VND exchange rates can meaningfully impact your monthly budget over time.
Healthcare: Access, Insurance, and Practical Setup
Healthcare is often a primary concern for retirees, and rightly so. Vietnam offers a mixed system, so planning ahead is essential.
In major cities in Vietnam that are perfect for retired expats such as Ho Chi Minh City and Hanoi, you’ll find quality international hospitals with English-speaking staff. Facilities such as FV Hospital and Vinmec are commonly used by expats.
Here’s how to approach healthcare:
Private Health Insurance (Recommended)
Monthly premiums: approximately £40–£120 depending on age and cover
Ensure your policy includes:
Inpatient and outpatient care
Emergency evacuation (important in Southeast Asia)
Coverage for pre-existing conditions (if applicable)
Public vs Private Care
Public hospitals are inexpensive but may have language barriers
Private hospitals offer higher standards and shorter waiting times
Routine Care Example
GP consultation: £15–£40
Specialist consultation: £30–£80
Practical advice: Before relocating, arrange international health insurance and identify your nearest reputable hospital. It’s also wise to keep digital and printed copies of your medical records.
Lifestyle: Choosing the Right Location for Your Needs
Vietnam offers diverse lifestyle options, so selecting the right location is key to long-term satisfaction.
Ho Chi Minh City (Saigon)
Best for: Urban lifestyle, dining, international communities
Consider if you enjoy energy, convenience, and social opportunities
Hanoi
Best for: Cultural immersion, history, slightly cooler climate
Offers a more traditional Vietnamese experience
Da Nang
Best for: Balance between city and beach living
Popular among retirees for its cleanliness and slower pace
Hoi An
Best for: Quiet, scenic retirement
Ideal if you prioritise charm over infrastructure
Lifestyle considerations:
Climate: Expect heat and humidity, particularly in the south
Community: Growing expat networks make integration easier
Activities:
Beach living, golf, yoga, and wellness
Travel opportunities across Southeast Asia
Example: Many UK retirees choose Da Nang for its affordability and relaxed pace, while still being within easy reach of international airports and quality healthcare.
Visas and Residency: Planning Your Legal Stay
Unlike some European destinations, Vietnam does not currently offer a straightforward “retirement visa,” so planning your residency strategy is crucial.
Here are some Vietnam retirement visa alternatives for your consideration:
Tourist Visa (Short-Term Option)
Typically valid for 30–90 days
Requires regular renewals or visa runs
Business Visa (Longer-Term Stability)
Often arranged through local agencies
Valid for several months to a year
Temporary Residence Card (TRC)
Requires sponsorship (e.g. through business or employment)
More stable long-term option
Practical advice:
Work with a reputable visa agent in Vietnam
Keep up to date with changing immigration rules
Budget for visa costs and renewals as part of your monthly expenses
Financial Planning: Making Your Money Work Internationally
From a financial adviser’s perspective, this is where many retirees either succeed or encounter avoidable challenges.
When retiring in Vietnam, you should carefully structure your finances:
Income Streams
UK pensions (State Pension and private pensions)
Investment income (dividends, drawdowns)
Currency Management
Use multi-currency accounts
Consider timing transfers when GBP strengthens
Tax Considerations
Determine your UK tax residency status
Understand Vietnam’s tax rules on foreign income
Seek advice on double taxation agreements
Banking Setup
Maintain a UK account for income
Open a local Vietnamese account for expenses
Example strategy: A retiree drawing £1,200/month from a diversified investment portfolio could comfortably cover living expenses in Vietnam, while leaving additional capital invested for long-term growth.
If you want to make the financial planning process easier, you can contact a professional financial advisor such as Benjamin Sharvell IFA in Vietnam to help you.
For UK retirees. Vietnam freezes your UK State Pension, so build private income around it and read our guide on managing your UK pension in Vietnam. There is no S1 healthcare cover, so private insurance is essential, and there is no dedicated retirement visa, so most retirees use a temporary residence card via a business route. See our Vietnam retirement visa alternatives and how much you need to retire in Vietnam.
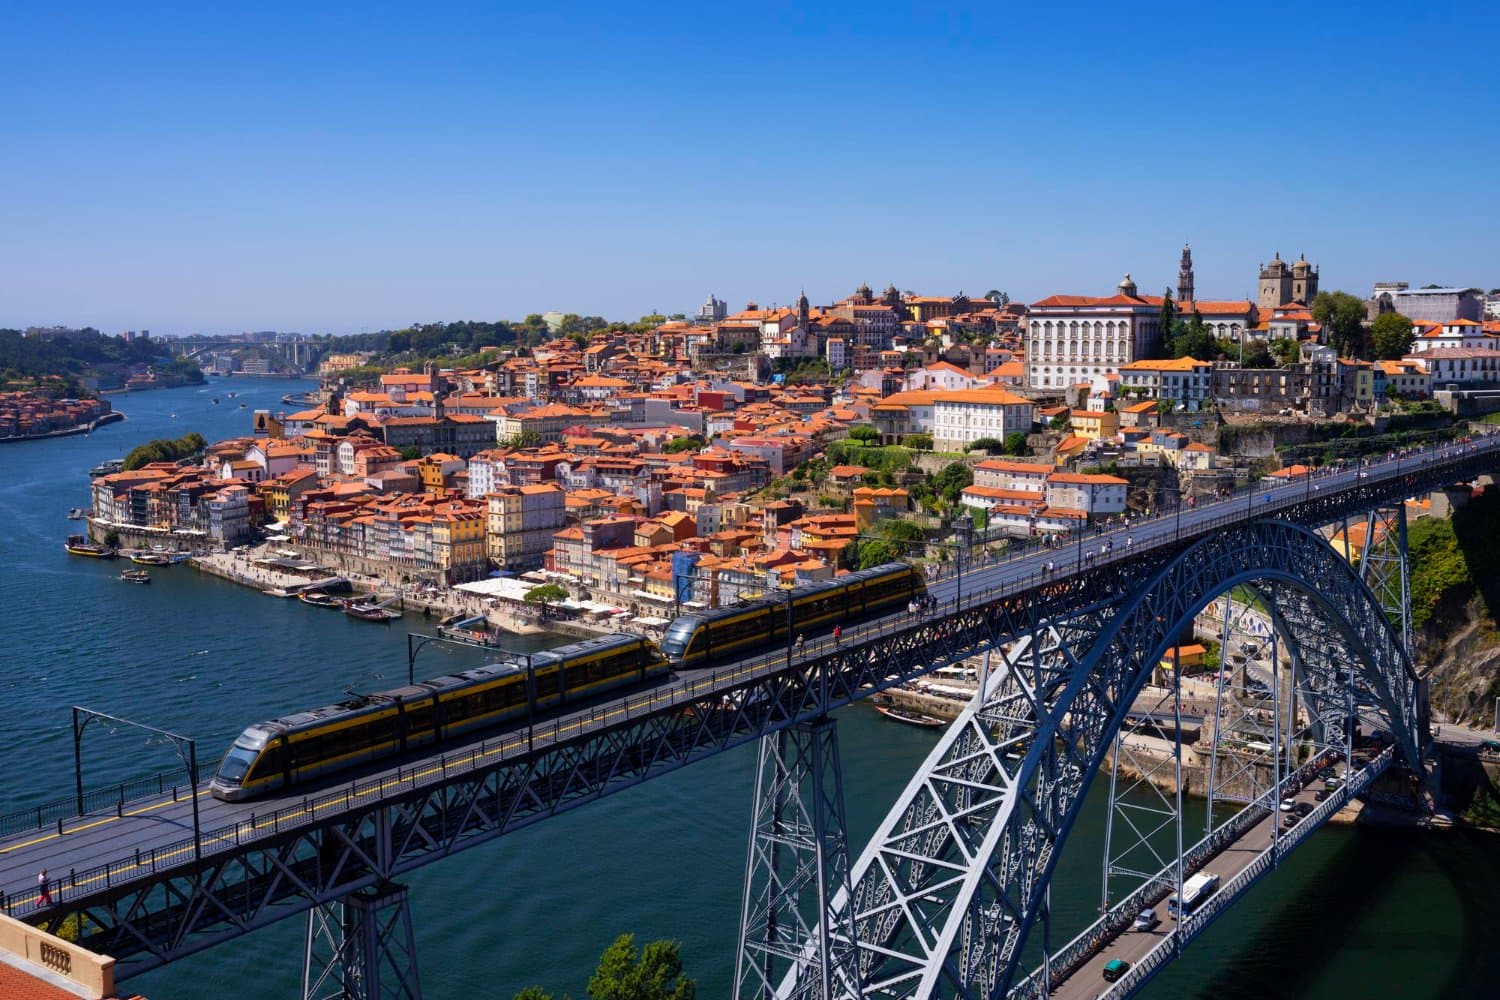
2. Portugal
Portugal continues to rank among the best places to retire as an expat, particularly for UK nationals seeking a blend of familiarity, lifestyle quality, and accessibility. However, as with any relocation, success lies in understanding the practical details and aligning them with your long-term financial strategy.
Below, I’ve expanded on the key considerations to help you approach retirement in Portugal with clarity and confidence.
Cost of Living: Building a Realistic Monthly Budget
Portugal offers good value relative to the UK, though costs vary significantly depending on location. The Algarve and Lisbon are naturally more expensive than inland regions or smaller towns.
In general, a comfortable lifestyle can be achieved on £1,200–£2,000 per month, though this depends on your accommodation choices and lifestyle preferences.
Here’s a more detailed breakdown:
Accommodation
One-bedroom apartment (Algarve or Lisbon): £600–£1,200/month
Smaller towns/inland areas: £400–£800/month
Tip: Long-term rentals (12+ months) often secure better pricing and stability
Food and Dining
Local meals: £8–£15
Mid-range restaurant: £20–£40 per person
Monthly groceries: £150–£300
Example: Many retirees adopt a hybrid lifestyle—cooking at home during the week and dining out socially at weekends
Utilities and Services
Electricity, water, internet: £80–£150/month
Council tax (IMI): relatively low compared to UK council tax
Transport
Public transport: £30–£60/month
Fuel costs similar to UK levels
Practical advice: When planning your move, allow a buffer of at least 10–15% above your expected monthly budget to account for seasonal utility fluctuations and lifestyle adjustments during your first year.
Healthcare: Access, Registration, and Insurance Options
Portugal’s healthcare system is one of its strongest advantages, offering both public and private options.
As a UK retiree, you may be eligible for access to the public healthcare system (SNS) if you are legally resident and registered. However, many expats choose to supplement this with private insurance for faster access and broader coverage.
Here’s how to approach it:
Public Healthcare (SNS)
Low-cost or free at point of use
Requires registration with your local health centre
Waiting times can vary, particularly in busy regions
Private Health Insurance (Highly Recommended)
Monthly premiums: £40–£100 depending on age and cover
Benefits include:
Shorter waiting times
Access to private hospitals and English-speaking doctors
Greater flexibility in specialist care
Typical Costs (Private Care)
GP consultation: £40–£70
Specialist appointment: £80–£150
**Practical advice:**Apply for an S1 form (if eligible) before leaving the UK, as this can grant access to state healthcare. Alongside this, arrange private insurance to ensure comprehensive coverage from the outset.
Lifestyle: Choosing the Right Region for Retirement
Portugal offers a diverse range of lifestyles, so selecting the right region is essential.
Algarve
Best for: Sun, beaches, established UK expat community
Lifestyle: Relaxed, social, and highly accessible
Ideal if you value familiarity and ease of integration
Lisbon
Best for: Culture, dining, and city living
More expensive, but vibrant and well-connected
Porto and Northern Portugal
Best for: Lower costs, authentic Portuguese lifestyle
Slightly cooler climate and fewer tourists
Central/Inland Regions
Best for: Quiet living and lower property prices
Ideal if you prioritise tranquillity over convenience
Lifestyle considerations:
Climate: Mild winters and warm summers, particularly in the south
Community: Strong expat networks, especially in the Algarve
Activities:
Golf, walking, sailing
Cultural events and local festivals
Easy travel within Europe
Example: Many UK retirees initially settle in the Algarve due to its familiarity, then later explore quieter inland areas for greater value and a slower pace of life.
For UK retirees. Portugal uprates your UK State Pension, and as a State Pension recipient you can register the S1 form for public healthcare. The main route is the D7 visa for those with pension or passive income. Note the tax change: Portugal's Non-Habitual Resident (NHR) regime closed to new applicants and its replacement no longer gives pensions a special rate, so budget for standard Portuguese tax and structure withdrawals before you move.
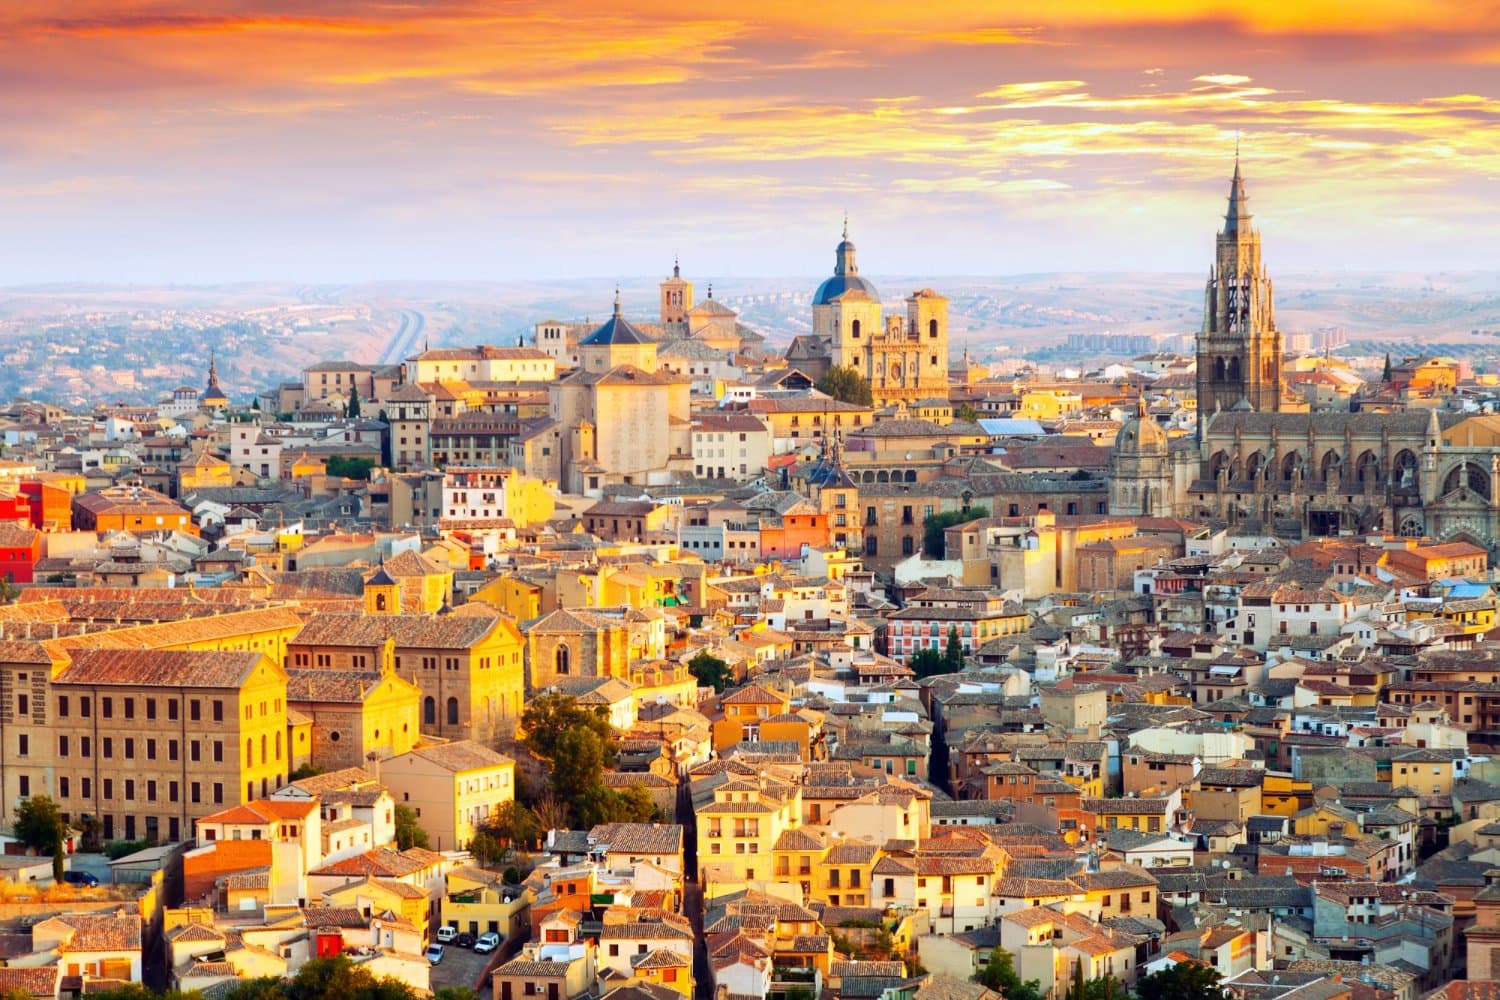
3. Spain
Spain has long been a cornerstone on any list of the best places to retire as an expat, particularly for UK nationals. Its combination of climate, accessibility, and established British communities makes it one of the easiest transitions for those relocating abroad. That said, a successful retirement in Spain still requires thoughtful planning across cost, healthcare, residency, and financial structure.
Below, I’ve expanded each key area to give you a clear and practical roadmap.
Cost of Living: Creating a Sustainable Monthly Plan
Spain offers a relatively affordable lifestyle compared to the UK, although costs vary depending on region. Coastal hotspots and major cities will naturally command higher prices than inland areas.
Most retirees can live comfortably on £1,300–£2,200 per month, depending on lifestyle choices.
Here’s a more detailed breakdown:
Accommodation
One-bedroom apartment (Costa del Sol/Costa Blanca): £600–£1,200/month
Inland towns: £400–£800/month
Tip: Consider renting initially before purchasing, as property markets can vary significantly by region
Food and Dining
Local menu del día (set lunch): £10–£15
Dinner at mid-range restaurant: £20–£40 per person
Monthly groceries: £150–£300
Example: Many expats embrace local markets for fresh produce, reducing grocery costs while improving quality
Utilities and Services
Electricity, water, internet: £90–£160/month
Note: Air conditioning in summer can increase electricity bills noticeably
Transport
Public transport: £30–£70/month
Car ownership: similar running costs to the UK
Practical advice: Spain’s cost of living can fluctuate seasonally in tourist areas. Budget slightly higher if you intend to live in coastal regions year-round, particularly during peak summer months.
Healthcare: Accessing Spain’s High-Quality System
Spain is widely recognised for its excellent healthcare system, which is a major draw for retirees.
As a UK expat, you may be eligible for public healthcare if you are a resident and hold an S1 form. However, many retirees choose to combine this with private insurance for added flexibility.
Here’s how to approach it:
Public Healthcare (Sistema Nacional de Salud)
High-quality and low-cost
Accessible with residency and S1 registration
Can involve waiting times for non-urgent treatments
Private Health Insurance (Recommended)
Monthly premiums: £50–£120
Benefits include:
Faster access to specialists
English-speaking doctors
Wider choice of facilities
Typical Private Costs
GP consultation: £40–£80
Specialist visit: £80–£150
Practical advice: Arrange your S1 form before leaving the UK, and register with your local health centre upon arrival. Even if you rely on public healthcare, private insurance provides valuable peace of mind.
Lifestyle: Selecting the Right Region for Your Retirement
Spain offers a diverse range of environments, so choosing the right location is essential for long-term satisfaction.
Costa del Sol
Best for: Large UK expat community, warm climate
Lifestyle: Social, active, well-connected
Ideal for those who want a familiar environment
Costa Blanca
Best for: Value for money and relaxed coastal living
Popular with retirees seeking affordability and sunshine
Barcelona
Best for: Culture, architecture, and city life
Higher cost but exceptional lifestyle offering
Valencia
Best for: Balance between city and beach living
Increasingly popular due to lower costs than Barcelona
Inland Spain
Best for: Lower costs and traditional lifestyle
Ideal if you prefer quiet surroundings and fewer tourists
Lifestyle considerations:
Climate: Hot summers, mild winters (particularly in the south)
Community: Strong expat presence in coastal areas
Activities:
Golf, walking, cycling
Dining and social culture
Festivals and cultural events
Example: Many UK retirees choose the Costa Blanca for its affordability and established expat networks, while others opt for Valencia to enjoy a more balanced and authentic Spanish lifestyle.
For UK retirees. Spain uprates your UK State Pension and gives S1 access to public healthcare. The usual retiree route is the Non-Lucrative Visa, which requires proof of sufficient passive income. Spanish income tax is progressive and can be high for larger pensions, so planning matters.
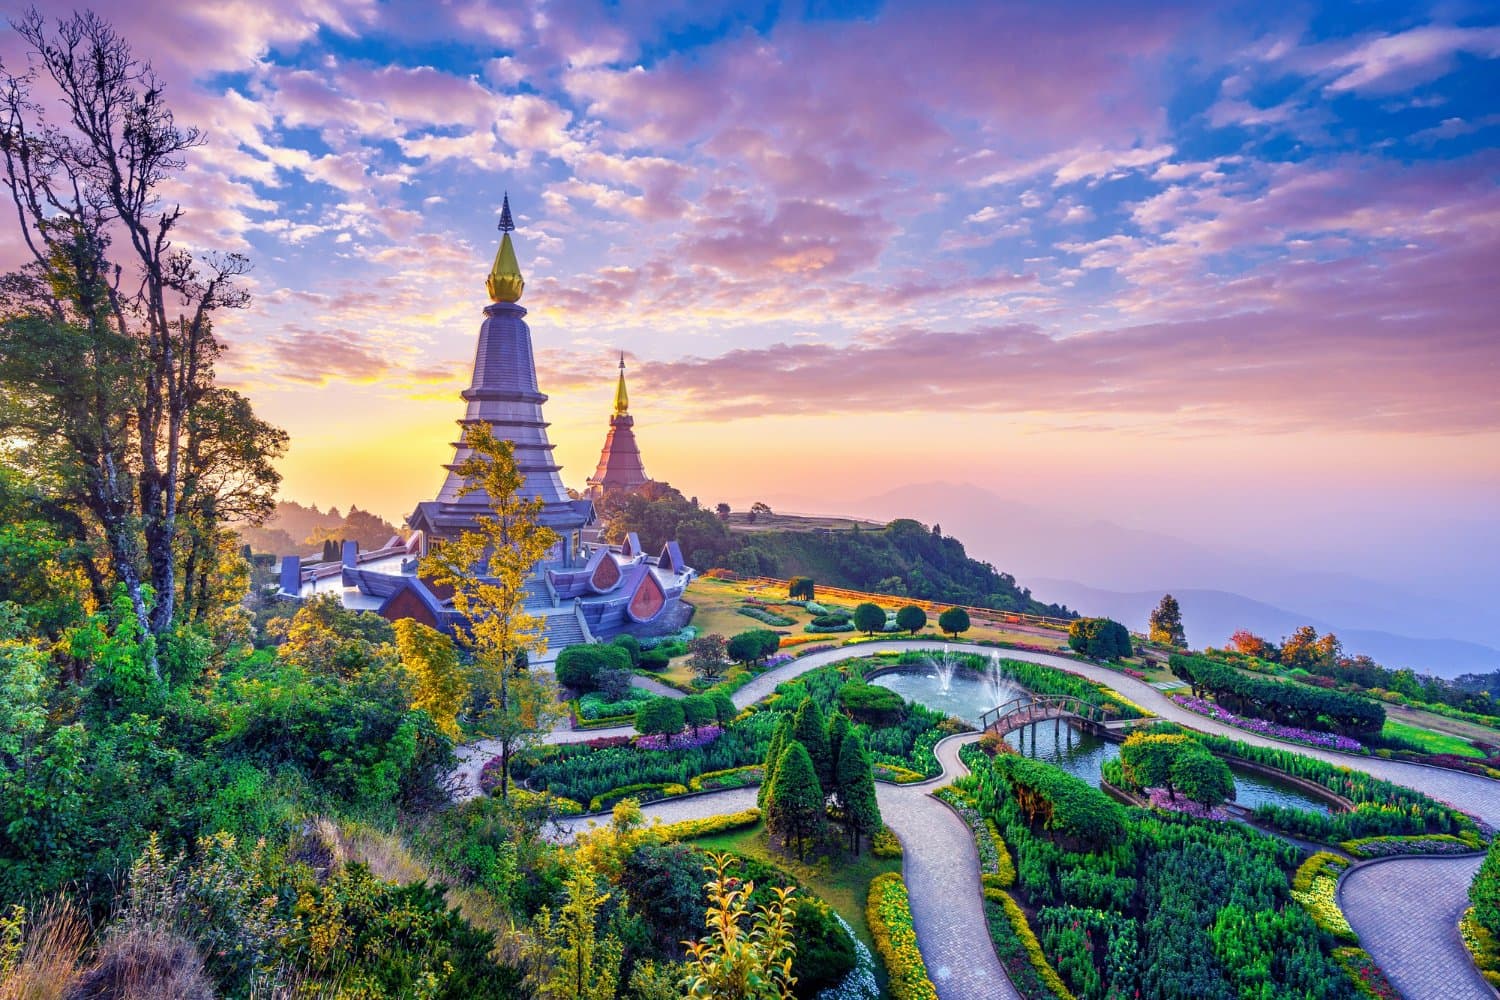
4. Thailand
Thailand has earned its place among the best places to retire as an expat thanks to its compelling mix of low living costs, high-quality healthcare, and an enviable lifestyle. For UK retirees willing to travel further afield, it offers excellent value without compromising on comfort.
However, as with any long-haul relocation, careful planning is essential. Below, I’ve expanded the key considerations to help you approach retirement in Thailand with clarity and structure.
Cost of Living: Maximising Value Without Compromising Lifestyle
Thailand is widely regarded as one of the most affordable retirement destinations, but your actual costs will depend heavily on location and lifestyle.
Most retirees live comfortably on £800–£1,500 per month, though this can increase in more premium areas such as central Bangkok or Phuket.
Here’s a practical breakdown:
Accommodation
One-bedroom apartment (Chiang Mai): £250–£500/month
Bangkok (modern condo): £400–£900/month
Beach locations (Phuket/Koh Samui): £500–£1,200/month
Tip: Opt for annual leases to secure lower rental rates and avoid seasonal price increases
Food and Dining
Street food/local meals: £1–£3
Mid-range restaurant: £10–£25 per person
Monthly groceries: £100–£250
Example: Many expats enjoy local cuisine daily while reserving Western dining for occasional social outings
Utilities and Services
Electricity, water, internet: £50–£120/month
Air conditioning can significantly increase electricity costs
Transport
Local transport (taxis, Grab): £1–£5 per journey
Monthly transport budget: £30–£100
Practical advice: Although Thailand is affordable, lifestyle inflation is common. It’s easy to spend more on dining, travel, and leisure, so set a clear monthly budget and review it regularly.
Healthcare: High Standards at Competitive Costs
Thailand is renowned for its private healthcare system, which is often comparable to Western standards at a fraction of the cost.
Cities such as Bangkok and Chiang Mai are home to internationally accredited hospitals, including Bumrungrad and Bangkok Hospital, which are widely used by expats.
Here’s how to approach healthcare:
Private Health Insurance (Essential)
Monthly premiums: £50–£150 depending on age and coverage
Ensure your policy includes:
Inpatient and outpatient care
Emergency evacuation
Long-term treatment coverage
Public vs Private Care
Public hospitals are inexpensive but less commonly used by expats
Private hospitals offer shorter waiting times and English-speaking staff
Typical Private Costs
GP consultation: £20–£50
Specialist visit: £40–£100
Many procedures are significantly cheaper than in the UK
Practical advice: Choose insurance that aligns with your long-term needs, particularly if you plan to remain in Thailand indefinitely. It’s also wise to identify your nearest reputable hospital shortly after arrival.
Lifestyle: Finding the Right Environment for Your Retirement
Thailand offers a wide range of lifestyle options, from bustling cities to tranquil beach towns.
Bangkok
Best for: Urban living, healthcare access, international amenities
Lifestyle: Fast-paced, convenient, highly connected
Chiang Mai
Best for: Lower cost of living, relaxed pace
Popular among retirees seeking community and affordability
Phuket and Koh Samui
Best for: Beach lifestyle and scenic surroundings
Higher costs but strong expat presence
Hua Hin
Best for: Quiet coastal retirement with easy access to Bangkok
Favoured by many European retirees
Lifestyle considerations:
Climate: Tropical, with high humidity and a distinct rainy season
Community: Well-established expat networks
Activities:
Golf, swimming, and wellness retreats
Travel across Southeast Asia
Cultural experiences and cuisine
Example: A retiree seeking a slower pace might choose Chiang Mai for its affordability and community, while someone prioritising healthcare and convenience may prefer Bangkok.
For UK retirees. Thailand freezes your UK State Pension, reconfirmed by the UK government in 2026, though the low cost of living softens the impact. There is no S1, so private insurance is essential and is required for the Non-O retirement visa (age 50 plus, with a deposit or income), with the LTR visa suiting wealthier applicants. Torn between the two most popular Asian bases? See Vietnam vs Thailand for UK retirees.
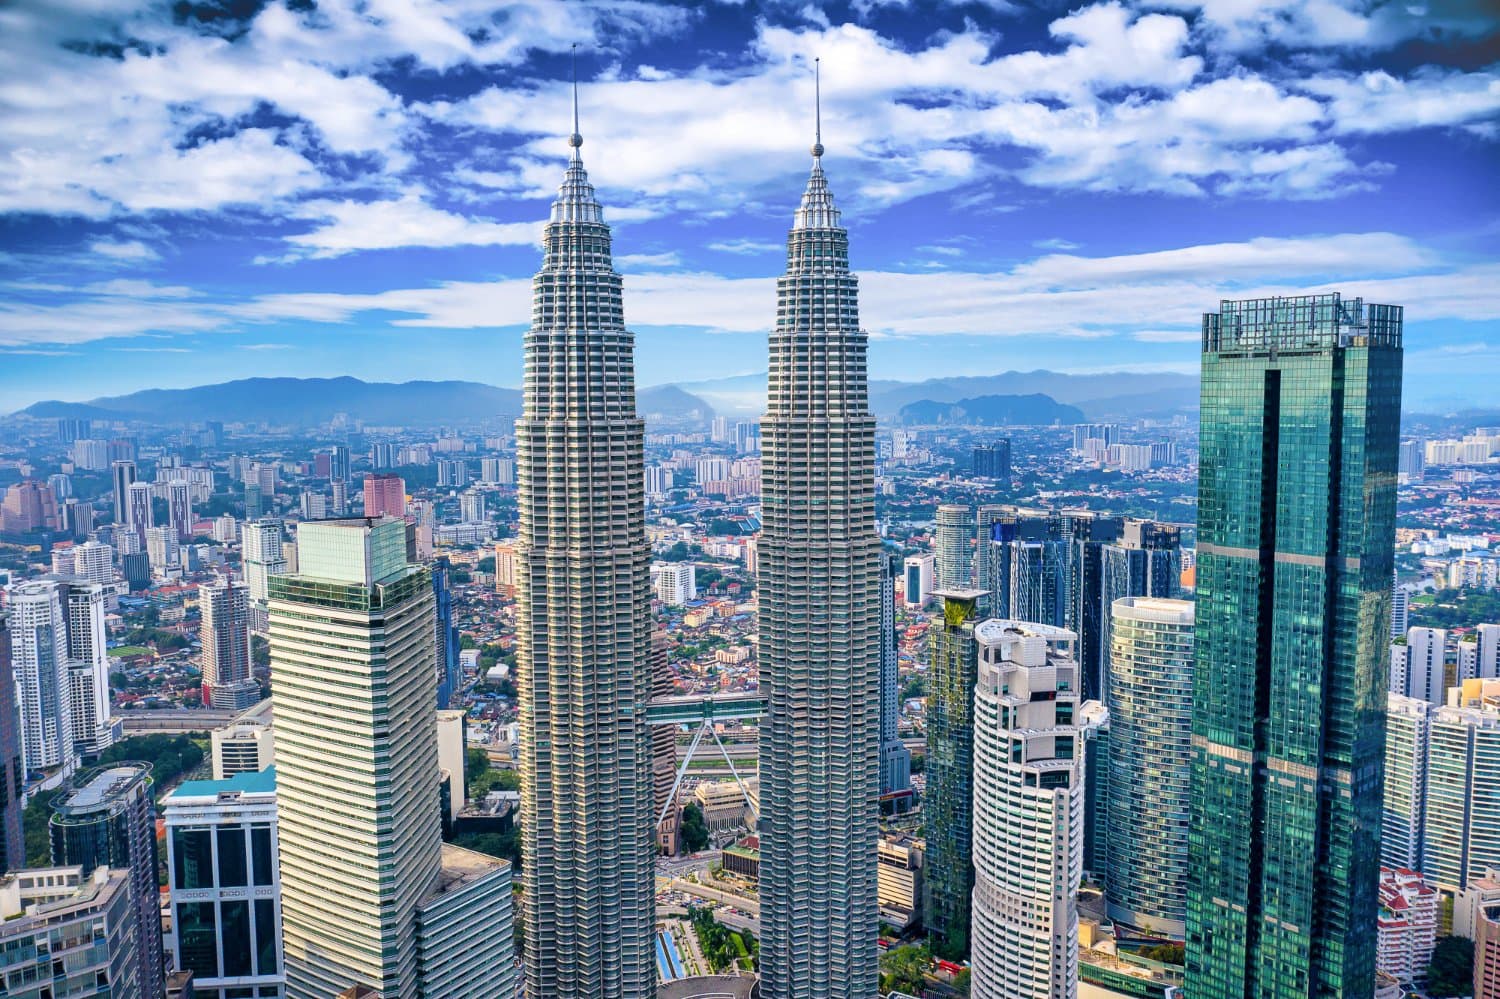
5. Malaysia
Malaysia is often overlooked, yet it quietly ranks among the best places to retire as an expat. For UK retirees, it offers an appealing combination of affordability, excellent healthcare, modern infrastructure, and widespread use of English, making the transition notably smoother than in many other Asian destinations.
That said, recent changes to visa schemes mean it is essential to approach Malaysia with a well-informed and structured plan. Below, I’ve expanded the key considerations to guide your decision-making.
Cost of Living: Achieving Comfort at Sensible Cost
Malaysia offers excellent value for money, particularly when compared to both the UK and neighbouring Singapore.
Most retirees can live comfortably on £1,000–£1,800 per month, depending on location and lifestyle. Kuala Lumpur will sit at the higher end, while Penang and smaller cities offer better value.
Here’s a detailed breakdown:
Accommodation
Modern one-bedroom apartment (Kuala Lumpur): £400–£800/month
Penang or smaller cities: £300–£600/month
Serviced apartments with facilities: £600–£1,000/month
Tip: Many developments include pools, gyms, and security as standard
Food and Dining
Local meals (hawker centres): £2–£5
Mid-range restaurant: £10–£25 per person
Monthly groceries: £120–£250
Example: A mix of local dining and occasional Western meals allows you to maintain both variety and affordability
Utilities and Services
Electricity, water, internet: £60–£130/month
Domestic help: £30–£80/month
Transport
Ride-hailing (Grab): £1–£4 per trip
Public transport (Kuala Lumpur): efficient and low-cost
Monthly transport budget: £30–£80
Practical advice: Malaysia offers strong value, but imported goods (especially Western brands) can be expensive. Adjust your lifestyle towards local products and services to maximise your budget.
Healthcare: Quality and Internationally Recognised
Malaysia’s healthcare system is one of its standout strengths and a major reason it features among the best places to retire as an expat.
Private healthcare is widely used by expats and is both affordable and of a very high standard. Many doctors are UK- or internationally trained, and English is commonly spoken.
Here’s how to approach it:
Private Health Insurance (Recommended)
Monthly premiums: £40–£120 depending on age and cover
Ensure coverage includes:
Inpatient and outpatient care
Specialist treatment
Emergency services
Private Healthcare Costs
GP consultation: £15–£40
Specialist visit: £30–£80
Procedures are typically far more affordable than in the UK
Public Healthcare
Available at low cost but less commonly used by expats
Longer waiting times compared to private facilities
Practical advice: Select a hospital near your residence early on. Cities like Kuala Lumpur and Penang have internationally accredited hospitals that cater specifically to expats.
Lifestyle: Balancing Modern Living with Cultural Diversity
Malaysia offers a unique blend of modern infrastructure and rich cultural diversity, which makes it particularly appealing for retirees seeking both comfort and interest.
Kuala Lumpur
Best for: Modern living, healthcare access, international amenities
Lifestyle: Cosmopolitan, convenient, and well-connected
Penang (George Town)
Best for: Culture, food, and relaxed coastal living
Popular among retirees for its charm and community feel
Langkawi
Best for: Quiet island lifestyle
Ideal if you prioritise tranquillity over urban convenience
Lifestyle considerations:
Climate: Tropical, with consistent warmth and humidity
Language: English widely spoken, easing integration
Community: Strong expat presence, particularly in Penang
Activities:
Dining (Malaysia is renowned for its food culture)
Travel across Southeast Asia
Beaches, walking, and cultural exploration
Example: Many UK retirees choose Penang for its balance of affordability, culture, and healthcare, while Kuala Lumpur suits those who prefer a more urban and connected lifestyle.
For UK retirees. Malaysia freezes your UK State Pension, so lean on private pensions and investments. There is no S1, so arrange private cover. Longer-term residency is via the Malaysia My Second Home (MM2H) programme, now organised into tiers with financial requirements.
6. Mexico
Mexico has steadily become one of the best places to retire as an expat, particularly for those seeking a vibrant lifestyle, strong expat communities, and excellent value for money. While it is geographically further from the UK than European options, it offers a compelling mix of affordability, culture, and climate.
As always, success lies in understanding the practical details before making the move. Below, I’ve expanded the key areas to help you plan effectively.
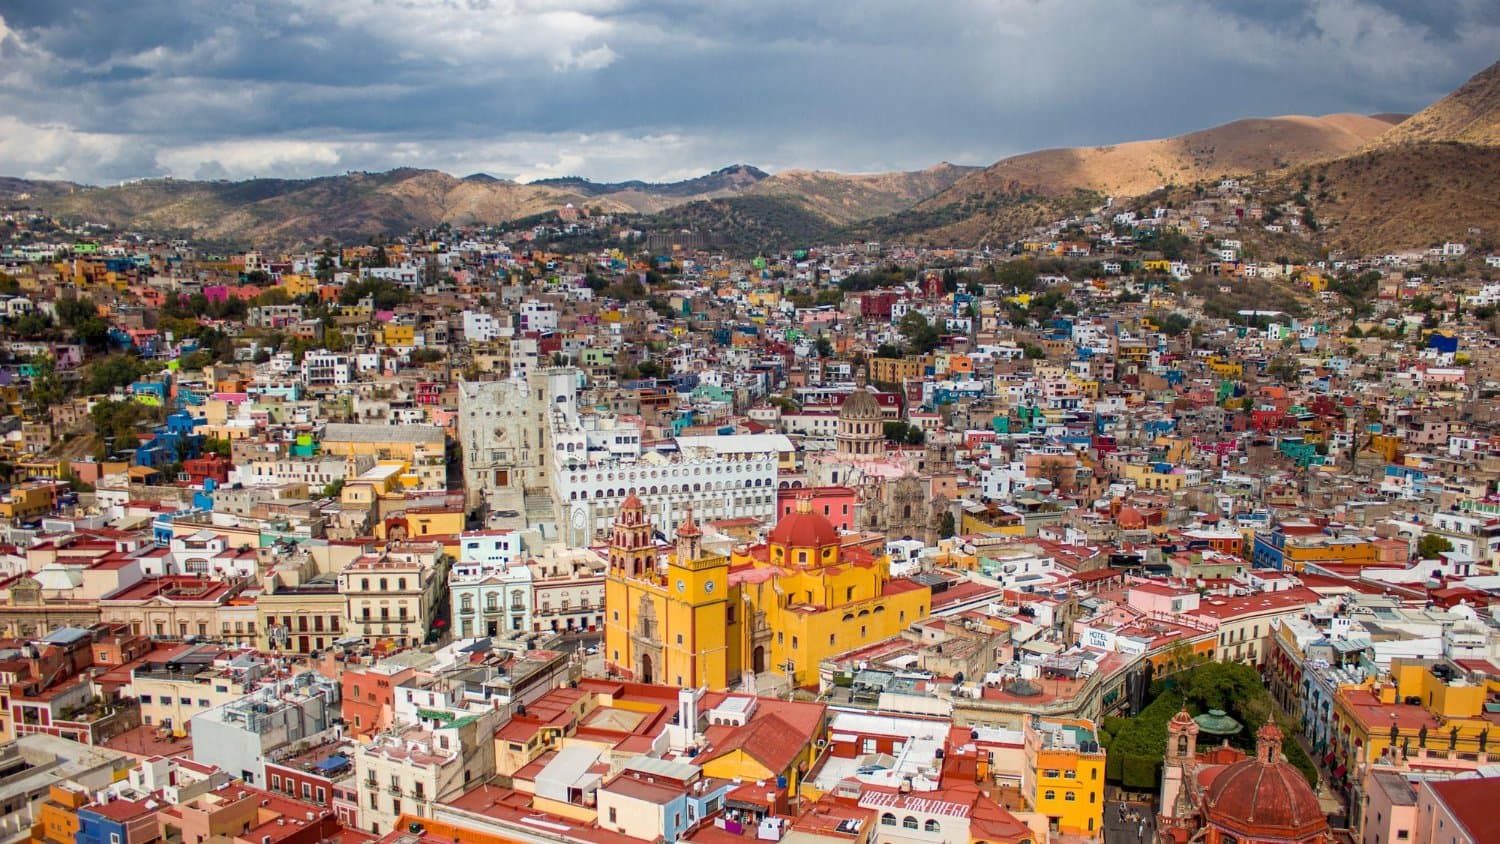
Cost of Living: Balancing Affordability with Lifestyle Choice
Mexico offers excellent value, although costs can vary widely depending on location. Coastal hotspots and well-established expat areas tend to be more expensive than inland towns.
Most retirees can live comfortably on £900–£1,700 per month, with higher budgets required in premium areas.
Here’s a more detailed breakdown:
Accommodation
One-bedroom apartment (expat areas such as Lake Chapala or Playa del Carmen): £400–£900/month
Smaller towns: £300–£600/month
Gated communities or modern developments: £700–£1,200/month
Tip: Renting initially allows you to explore different regions before committing long-term
Food and Dining
Local meals: £3–£8
Mid-range restaurant: £12–£25 per person
Monthly groceries: £120–£250
Example: Shopping at local markets can significantly reduce costs while offering fresh produce
Utilities and Services
Electricity, water, internet: £50–£120/month
Note: Air conditioning in warmer regions can increase electricity bills
Transport
Local buses and taxis: very affordable
Monthly transport budget: £30–£80
Practical advice: Costs can fluctuate depending on exchange rates (GBP/MXN), so consider transferring funds strategically rather than all at once.
Healthcare: Affordable and Accessible Private Care
Healthcare in Mexico is a key strength, particularly in private facilities, which are widely used by expats.
Major cities and expat hubs offer high-quality hospitals with English-speaking staff, often at a fraction of UK private healthcare costs.
Here’s how to approach it:
Private Health Insurance (Recommended)
Monthly premiums: £50–£130 depending on age and cover
Ensure your policy includes:
Inpatient and outpatient care
Emergency treatment
Access to reputable private hospitals
Public Healthcare (IMSS)
Available at low cost for residents
Can be a useful backup, though many expats prefer private care
Typical Private Costs
GP consultation: £20–£50
Specialist visit: £40–£100
Procedures are often significantly cheaper than in the UK
Practical advice: Research healthcare facilities in your chosen area before relocating. Many expats prioritise locations with established medical infrastructure, such as Guadalajara or Cancun.
Lifestyle: Choosing the Right Region for Your Retirement
Mexico offers a wide range of lifestyle options, from colonial towns to beachside living.
Lake Chapala (Ajijic)
Best for: Large expat community, mild climate
One of the most established retirement hubs
Riviera Maya (Playa del Carmen, Tulum)
Best for: Beach lifestyle and vibrant social scene
Higher cost but strong international community
San Miguel de Allende
Best for: Culture, art, and historic charm
Popular with retirees seeking a slower pace
Mexico City or Guadalajara
Best for: Urban living and top-tier healthcare
More suited to those who enjoy city environments
Lifestyle considerations:
Climate: Varies by region (coastal areas are hotter and more humid)
Community: Strong expat networks in key locations
Activities:
Cultural events and festivals
Dining and social life
Travel within North and Central America
Example: Many UK retirees choose Lake Chapala for its temperate climate and established support networks, while others prefer Playa del Carmen for a more active, beach-oriented lifestyle.
For UK retirees. Mexico freezes your UK State Pension. There is no S1, so private cover (or IMSS) is needed. Residency is via temporary then permanent routes, granted on proof of income or savings, and foreign income is generally taxed lightly, though you should confirm your position under the UK to Mexico treaty.
7. Costa Rica
Costa Rica has earned a strong reputation as one of the best places to retire as an expat, particularly for those prioritising political stability, natural beauty, and a slower pace of life. For UK retirees, it offers a compelling mix of lifestyle and security, though it is important to plan carefully as costs can be higher than other Latin American destinations.
Below, I’ve expanded the key areas to help you assess whether Costa Rica aligns with your financial and lifestyle goals.
Cost of Living: Understanding Where Your Money Goes
Costa Rica is not the cheapest option on this list, but it offers solid value when viewed in terms of quality of life and infrastructure.
Most retirees live comfortably on £1,200–£2,000 per month, although premium coastal areas can push costs higher.
Here’s a more detailed breakdown:
Accommodation
One-bedroom apartment (Central Valley): £500–£900/month
Coastal areas (e.g. Tamarindo): £700–£1,400/month
Gated communities or modern developments: £900–£1,600/month
Tip: Inland areas often provide better value and cooler climates
Food and Dining
Local meals (“sodas”): £4–£8
Mid-range restaurant: £15–£30 per person
Monthly groceries: £200–£350
Note: Imported goods can be expensive, so adopting local products helps manage costs
Utilities and Services
Electricity, water, internet: £70–£150/month
Air conditioning (in coastal regions) can increase electricity bills
Transport
Public transport: low-cost and widely available
Monthly transport budget: £40–£100
Practical advice: Costa Rica’s currency (colón) can fluctuate, so it’s wise to maintain flexibility in your budget. Additionally, factor in higher initial setup costs when relocating.
Healthcare: A Strong and Reliable System
Healthcare is one of Costa Rica’s key strengths and a major reason it features among the best places to retire as an expat.
The country offers a dual system:
Public Healthcare (Caja Costarricense de Seguro Social – “Caja”)
Mandatory for residents
Funded through monthly contributions based on income
Provides comprehensive coverage, though waiting times can vary
Private Healthcare (Supplementary Option)
Widely used by expats for faster access
Monthly insurance: £50–£120
Private consultation costs:
GP: £30–£60
Specialist: £60–£120
Healthcare standards are high, particularly in the Central Valley, where most major hospitals are located.
Practical advice: Register for the Caja system as part of your residency process, and consider private insurance as a supplement to ensure flexibility and shorter waiting times.
Lifestyle: Embracing the “Pura Vida” Approach
Costa Rica is known for its relaxed “Pura Vida” lifestyle, which emphasises simplicity, wellbeing, and connection with nature.
Choosing the right region is essential:
Central Valley (San José, Escazú, Atenas)
Best for: Healthcare access, mild climate, infrastructure
Popular among retirees seeking convenience and stability
Pacific Coast (Guanacaste, Tamarindo)
Best for: Beach lifestyle and sunshine
Higher cost but strong expat presence
Southern Zone (Uvita, Ojochal)
Best for: Quiet, nature-focused living
Less developed but increasingly popular
Lifestyle considerations:
Climate: Tropical, with dry and rainy seasons
Community: Established expat networks in key areas
Activities:
Outdoor living (beaches, hiking, wildlife)
Wellness and eco-living
Slower, more relaxed daily pace
Example: Many retirees begin in the Central Valley for ease of access to healthcare and services, then explore coastal regions once they are more familiar with the country.
For UK retirees. Costa Rica freezes your UK State Pension, but it does not tax foreign pension income, which is a real draw. There is no S1, so you register with Caja and usually add private cover. The Pensionado visa requires a modest guaranteed monthly pension.
8. Greece
Greece has increasingly established itself as one of the best places to retire as an expat, particularly for UK nationals seeking a relaxed Mediterranean lifestyle combined with attractive tax incentives and relatively low living costs.
However, while the appeal is clear, sunshine, culture, and slower living, it is important to approach retirement in Greece with a structured plan, particularly around healthcare access, taxation, and regional differences.
Below, I’ve expanded the key considerations to help you make a well-informed decision.
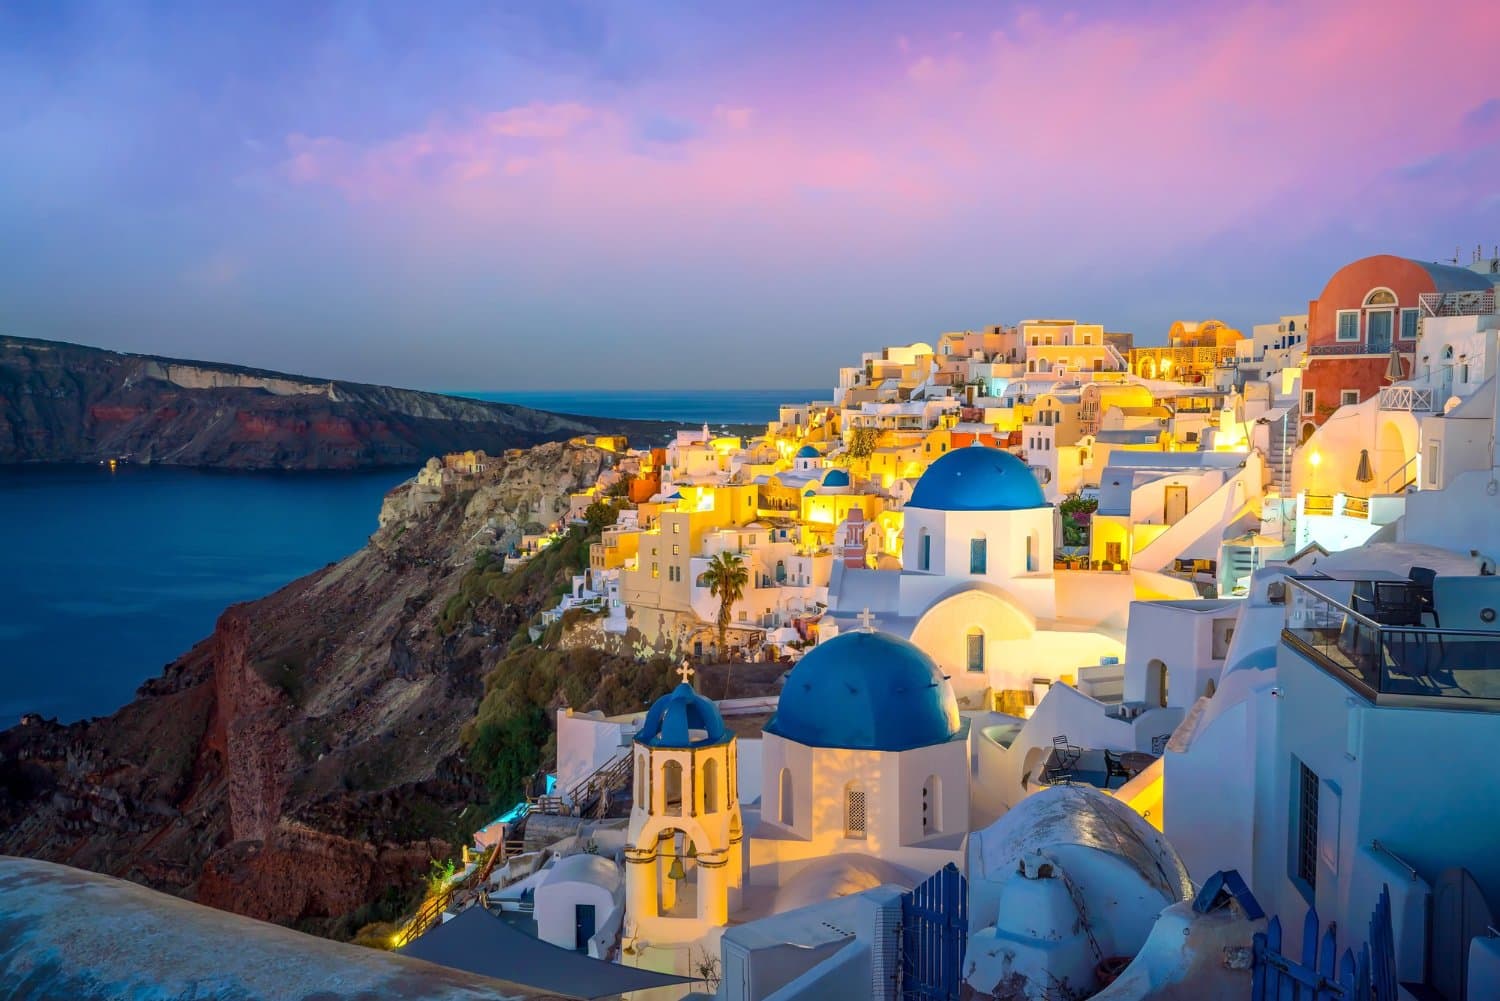
Cost of Living: Finding Value Across Regions
Greece offers good value compared to the UK, although costs vary significantly depending on whether you choose a major city, an island, or a rural area.
Most retirees can live comfortably on £1,200–£1,800 per month, with islands and tourist-heavy areas sitting at the higher end.
Here’s a more detailed breakdown:
Accommodation
One-bedroom apartment (Athens): £500–£900/month
Islands (e.g. Crete, Rhodes): £600–£1,200/month
Rural areas: £300–£700/month
Tip: Long-term rentals outside peak tourist zones offer significantly better value
Food and Dining
Local meals: £8–£15
Mid-range restaurant: £20–£35 per person
Monthly groceries: £150–£300
Example: Shopping at local markets and cooking at home can noticeably reduce monthly costs
Utilities and Services
Electricity, water, internet: £80–£150/month
Note: Energy costs can fluctuate, particularly in winter or during peak summer usage
Transport
Public transport: £30–£60/month
Car hire or ownership may be necessary in rural or island locations
Practical advice: If you are cost-conscious, consider living slightly outside major tourist areas. This often results in lower rent, lower day-to-day expenses, and a more authentic lifestyle.
Healthcare: Access, Quality, and Private Options
Greece offers a mixed healthcare system, combining public services with a well-developed private sector.
As a UK retiree, access to public healthcare depends on your residency status and documentation (such as an S1 form), but many expats choose to supplement this with private insurance.
Here’s how to approach it:
Public Healthcare (ESY)
Available to residents at low cost
Quality varies by region, with better facilities in cities like Athens and Thessaloniki
Waiting times can be longer for non-urgent care
Private Health Insurance (Recommended)
Monthly premiums: £50–£120
Benefits include:
Faster access to specialists
Higher comfort standards
English-speaking medical professionals
Typical Private Costs
GP consultation: £40–£70
Specialist appointment: £70–£120
Practical advice: If you choose island living, ensure there is adequate healthcare infrastructure nearby. Many retirees opt to live within reasonable distance of a major hospital for peace of mind.
Lifestyle: Choosing Between Island, City, and Mainland Living
Greece offers a variety of lifestyle options, each with its own advantages.
Athens
Best for: Culture, healthcare access, and international connectivity
Lifestyle: Vibrant but more urban and busy
Thessaloniki
Best for: Lower cost city living with strong cultural identity
Less crowded than Athens
Crete
Best for: Balanced lifestyle with good infrastructure
Popular among retirees due to its size and accessibility
Smaller Islands (e.g. Rhodes, Corfu)
Best for: Scenic, relaxed living
Consider seasonal fluctuations in activity and services
Mainland Rural Areas
Best for: Low-cost, quiet retirement
Ideal if you prioritise tranquillity
Lifestyle considerations:
Climate: Hot, dry summers and mild winters
Community: Growing expat presence, particularly in islands and coastal regions
Activities:
Outdoor living, beaches, and walking
Cultural exploration and history
Social dining and local festivals
Example: Many UK retirees choose Crete as it offers a balance between island charm and practical infrastructure, including hospitals, airports, and year-round services.
For UK retirees. Greece uprates your UK State Pension and offers S1 healthcare access. Its headline draw is tax: qualifying foreign pensioners who move their tax residency can elect a flat 7% tax on foreign pension income for up to 15 years, far below the standard progressive rates. The retiree route is the Financially Independent Person visa.
9. Turkey
Turkey has become an increasingly attractive option among the best places to retire as an expat, particularly for those seeking exceptional value for money, a warm climate, and a rich cultural experience. For UK retirees, it offers a compelling lifestyle at a significantly lower cost than most European destinations.
That said, Turkey does require a more considered approach, particularly in relation to currency volatility and long-term financial planning. Below, I’ve expanded the key areas to help you assess whether Turkey is the right fit for your retirement.
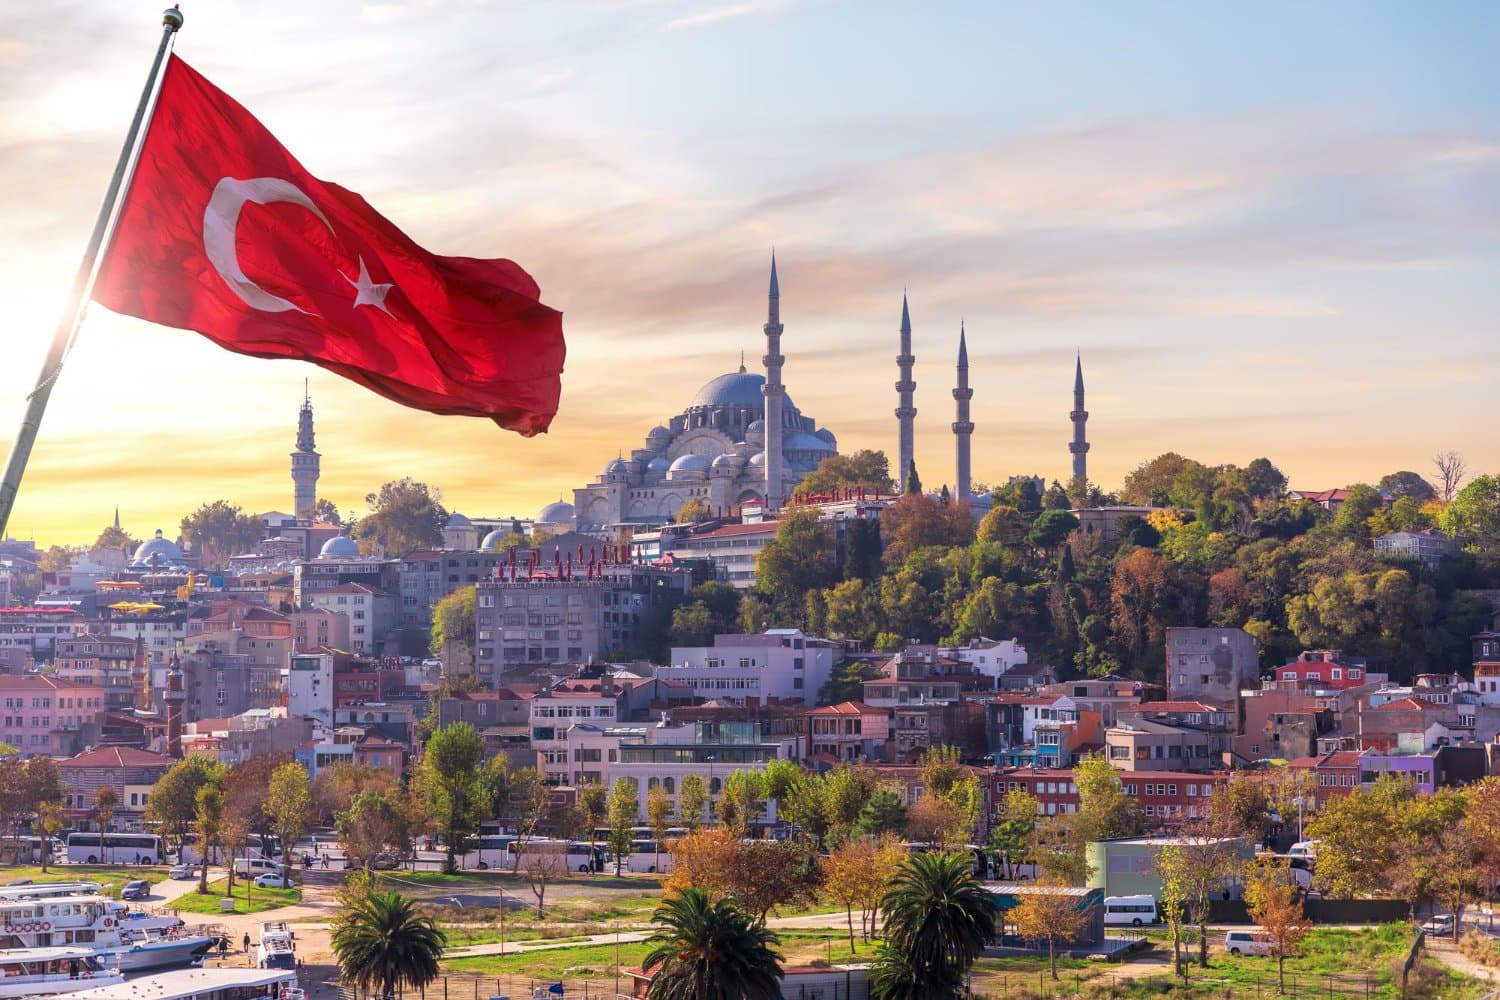
Cost of Living: Exceptional Value with Careful Budgeting
Turkey stands out for its affordability, especially when compared to the UK and much of Europe. However, inflation and currency fluctuations mean it is important to review your budget regularly.
Most retirees can live comfortably on £700–£1,400 per month, depending on location and lifestyle.
Here’s a practical breakdown:
Accommodation
One-bedroom apartment (coastal areas such as Antalya or Bodrum): £300–£700/month
Inland towns: £200–£500/month
Modern developments or villas: £600–£1,200/month
Tip: Long-term rentals often provide better value and price stability
Food and Dining
Local meals: £3–£8
Mid-range restaurant: £10–£20 per person
Monthly groceries: £120–£250
Example: Buying from local markets can significantly reduce food costs while maintaining quality
Utilities and Services
Electricity, water, internet: £60–£130/month
Energy costs can vary depending on season and usage
Transport
Public transport: efficient and low-cost
Monthly transport budget: £20–£60
Practical advice: Due to inflation in Turkey, it is sensible to build flexibility into your budget and review your spending every 3–6 months to ensure it remains aligned with current costs.
Healthcare: Affordable and Improving Standards
Turkey offers a mix of public and private healthcare, with private facilities generally preferred by expats.
In major cities and coastal regions, private hospitals are modern, well-equipped, and often staffed by English-speaking professionals.
Here’s how to approach healthcare:
Private Health Insurance (Recommended)
Monthly premiums: £40–£100
Required for residency permits in many cases
Ensure coverage includes:
Inpatient and outpatient care
Emergency services
Public Healthcare
Accessible at low cost once registered
Quality can vary by location
Typical Private Costs
GP consultation: £15–£40
Specialist visit: £30–£80
Many treatments are significantly cheaper than in the UK
Practical advice: Identify reputable hospitals in your chosen area before relocating. Coastal regions such as Antalya tend to have better access to private healthcare facilities.
Lifestyle: Coastal Living and Cultural Richness
Turkey offers a diverse lifestyle, combining Mediterranean living with a deep cultural heritage.
Antalya
Best for: Beach lifestyle, affordability, and expat community
One of the most popular retirement destinations
Bodrum
Best for: More upscale coastal living
Slightly higher costs but strong lifestyle appeal
Fethiye
Best for: Relaxed pace and scenic surroundings
Popular with UK retirees
Istanbul
Best for: Urban lifestyle and cultural depth
More suited to those who enjoy city living
Lifestyle considerations:
Climate: Hot summers, mild winters (particularly along the coast)
Community: Established UK expat presence in coastal regions
Activities:
Beach and outdoor living
Historical and cultural exploration
Dining and social life
Example: Many UK retirees choose Fethiye for its balance of affordability, natural beauty, and a welcoming expat community.
For UK retirees. Turkey is a rare non-EU country that uprates the UK State Pension, thanks to a reciprocal agreement, which makes it unusual among budget destinations. There is no S1, so private insurance is needed (and required for residency). Build in a currency buffer and review spending every few months given inflation.
10. Cyprus
Cyprus is consistently ranked among the best places to retire as an expat, particularly for UK nationals. Its familiar legal system, widespread use of English, and left-hand driving make the transition notably smoother than many other destinations.
However, while Cyprus offers a comfortable and accessible lifestyle, it is still important to approach your move with a clear financial and practical plan. Below, I’ve expanded the key considerations to help you evaluate Cyprus as a retirement destination.
Cost of Living: Planning for a Comfortable Mediterranean Lifestyle
Cyprus is moderately priced compared to the UK—more affordable than many Western European countries, but slightly higher than some Eastern European or Asian destinations.
Most retirees can expect to live comfortably on £1,300–£2,100 per month, depending on location and lifestyle.
Here’s a more detailed breakdown:
Accommodation
One-bedroom apartment (Paphos or Limassol): £600–£1,100/month
Smaller towns or inland areas: £400–£800/month
Villas or sea-view properties: £900–£1,500+/month
Tip: Long-term rentals often provide better value, particularly outside peak tourist areas
Food and Dining
Local meals: £10–£18
Mid-range restaurant: £25–£45 per person
Monthly groceries: £180–£350
Example: Shopping locally and cooking at home regularly helps manage costs effectively
Utilities and Services
Electricity, water, internet: £100–£180/month
Note: Air conditioning in summer can significantly increase electricity bills
Transport
Public transport is limited in some areas
Car ownership is often necessary
Monthly transport costs: £60–£150
Practical advice: Factor in seasonal variations, summer cooling costs and higher demand in coastal areas can increase your monthly expenses.
Healthcare: Reliable Access with Public and Private Options
Cyprus offers a solid healthcare system, combining public provision with a strong private sector.
As a resident, you may be eligible for access to the General Healthcare System (GESY), though many expats also choose private insurance for additional flexibility.
Here’s how to approach it:
Public Healthcare (GESY)
Accessible to residents who register
Offers low-cost access to doctors and hospitals
Generally good standards, though waiting times can vary
Private Health Insurance (Recommended)
Monthly premiums: £50–£120
Benefits include:
Faster access to specialists
Wider choice of facilities
English-speaking medical staff
Typical Private Costs
GP consultation: £40–£70
Specialist appointment: £70–£120
Practical advice: Register for GESY once resident, but maintain private insurance to ensure quicker access and broader coverage, particularly for specialist care.
Lifestyle: Familiarity Meets Mediterranean Living
Cyprus offers a lifestyle that is particularly appealing to UK retirees due to its familiarity combined with a relaxed Mediterranean pace.
Paphos
Best for: Large UK expat community and relaxed lifestyle
Popular for its accessibility and coastal setting
Limassol
Best for: More cosmopolitan lifestyle
Slightly higher cost but greater variety of amenities
Larnaca
Best for: Balance between affordability and convenience
Close to the main international airport
Nicosia
Best for: Urban living and local culture
Less focused on tourism
Lifestyle considerations:
Climate: Hot summers, mild winters
Language: English widely spoken
Community: Strong British expat presence
Activities:
Beach and outdoor living
Golf and leisure activities
Social clubs and expat networks
Example: Many UK retirees choose Paphos for its combination of affordability, community, and relaxed coastal lifestyle, making integration particularly straightforward.
For UK retirees. Cyprus uprates your UK State Pension and the S1 form works well there. On tax, UK retirees can elect a flat 5% on foreign pension income above a small allowance (or use the progressive bands), plus a modest GeSY health levy, giving one of Europe's lowest effective pension tax rates. Non-EU Brits typically obtain residency via an income-based route.
11. France
France remains one of the best places to retire as an expat for UK nationals who prioritise quality of life, excellent healthcare, and cultural familiarity over purely low costs. While it is not the cheapest destination on this list, it offers a level of infrastructure, stability, and lifestyle that is difficult to match.
From a financial planning perspective, France rewards those who take a structured approach, particularly around taxation, residency, and long-term wealth management. Below, I’ve expanded the key areas to help guide your decision.
Cost of Living: Balancing Quality with Affordability
France offers a high standard of living, but costs vary significantly depending on location. Paris and the Côte d’Azur are notably expensive, whereas rural regions provide much better value.
Most retirees can expect to live comfortably on £1,500–£2,500 per month, depending on lifestyle and region.
Here’s a more detailed breakdown:
Accommodation
One-bedroom apartment (Paris): £1,000–£1,800/month
Regional cities (e.g. Bordeaux, Lyon): £600–£1,200/month
Rural areas: £400–£800/month
Tip: Many retirees find better value and quality of life in rural or semi-rural locations
Food and Dining
Local meals: £12–£20
Mid-range restaurant: £25–£50 per person
Monthly groceries: £200–£350
Example: Shopping at local markets and cooking at home can significantly reduce costs while maintaining high food quality
Utilities and Services
Electricity, water, internet: £100–£180/month
Heating costs can increase expenses during winter months
Transport
Public transport: £50–£100/month
Rural living may require car ownership
Practical advice: France offers excellent value outside major cities. If cost efficiency is important, consider regions such as Dordogne or Occitanie, where property and living costs are significantly lower.
Healthcare: One of the Best Systems in the World
France is widely regarded as having one of the best healthcare systems globally, making it a key reason it ranks among the best places to retire as an expat.
As a resident, you can access the public healthcare system (PUMA), which reimburses a significant portion of medical costs.
Here’s how to approach healthcare:
Public Healthcare (PUMA System)
Accessible once you are legally resident
Typically reimburses around 70% of healthcare costs
High standards across the country
Top-Up Insurance (Mutuelle – Strongly Recommended)
Monthly cost: £40–£120
Covers the remaining portion of medical expenses
Widely used by both locals and expats
Typical Costs (Before Reimbursement)
GP consultation: £20–£30
Specialist visit: £50–£100
Practical advice: Register for healthcare as soon as you establish residency. A mutuelle policy is essential to minimise out-of-pocket expenses and ensure comprehensive coverage.
Lifestyle: Regional Diversity and Cultural Appeal
France offers a diverse range of lifestyles, allowing you to tailor your retirement to your personal preferences.
South of France (Provence, Côte d’Azur)
Best for: Climate, scenery, and lifestyle
Higher cost but exceptional quality of life
Southwest France (Dordogne, Occitanie)
Best for: Value, rural charm, and slower pace
Popular among UK retirees
Brittany and Normandy
Best for: Proximity to the UK and coastal living
Cooler climate but strong cultural identity
Paris and Major Cities
Best for: Culture, connectivity, and amenities
Higher cost and faster pace
Lifestyle considerations:
Climate: Varies by region (Mediterranean in the south, cooler in the north)
Community: Established expat populations in many regions
Activities:
Food, wine, and cultural experiences
Walking, cycling, and outdoor living
Easy travel across Europe
Example: Many UK retirees choose the Dordogne for its affordability, scenic countryside, and established expat networks, offering a balance between cost and quality of life.
For UK retirees. France uprates your UK State Pension and gives S1 holders access to its top-ranked healthcare, with S1 status also exempting pension income from certain French social charges. The retiree route is a long-stay visitor visa (VLS-TS) with proof of income.
12. Bulgaria
Bulgaria is often considered one of the most underrated options among the best places to retire as an expat, particularly for UK retirees seeking a European base at a significantly lower cost. While it may not offer the same level of infrastructure as Western Europe, it provides excellent value, low property prices, and a relaxed pace of life.
From a financial planning perspective, Bulgaria can be highly efficient, provided you approach healthcare, residency, and long-term planning with care. Below, I’ve expanded the key considerations to help you evaluate whether Bulgaria aligns with your retirement goals.
Cost of Living: Maximising Affordability Within Europe
Bulgaria is one of the most affordable countries in Europe, making it particularly attractive for retirees working with a fixed income.
Most retirees can live comfortably on £700–£1,200 per month, depending on location and lifestyle.
Here’s a detailed breakdown:
Accommodation
One-bedroom apartment (Sofia): £300–£600/month
Coastal or smaller towns: £200–£500/month
Property purchase prices are notably low compared to the UK
Tip: Many retirees choose to buy property outright due to affordability
Food and Dining
Local meals: £5–£10
Mid-range restaurant: £10–£20 per person
Monthly groceries: £120–£250
Example: Buying seasonal produce from local markets helps keep costs low while maintaining quality
Utilities and Services
Electricity, water, internet: £60–£130/month
Heating costs can increase during winter
Transport
Public transport: £20–£50/month
Car ownership is affordable but not always necessary in cities
Practical advice: While Bulgaria is low-cost, it’s wise to maintain a contingency fund. Unexpected expenses, particularly related to property maintenance or travel, can arise.
Healthcare: Improving System with Private Options
Healthcare in Bulgaria is improving, though it may not match Western European standards in all areas. As a result, many expats rely on a combination of public access and private care.
Here’s how to approach it:
Public Healthcare
Available through mandatory contributions once resident
Costs are low, but quality can vary depending on location
Private Health Insurance (Recommended)
Monthly premiums: £40–£100
Provides access to better facilities and shorter waiting times
Typical Private Costs
GP consultation: £20–£40
Specialist visit: £30–£70
Healthcare Infrastructure
- Best facilities are located in larger cities such as Sofia, Plovdiv, and Varna
Practical advice: If healthcare is a priority, consider living within reasonable distance of a major city. Additionally, ensure your insurance includes options for treatment abroad if required.
Lifestyle: Affordable Living with European Charm
Bulgaria offers a relaxed lifestyle with a mix of cultural heritage, natural beauty, and affordability.
Sofia
Best for: Urban living, healthcare access, and amenities
More developed infrastructure
Plovdiv
Best for: Culture and lower cost city living
Known for its historic charm
Varna and Burgas (Black Sea Coast)
Best for: Coastal lifestyle
Popular during summer months
Rural Areas
Best for: Very low-cost, quiet living
Ideal if you prioritise tranquillity
Lifestyle considerations:
Climate: Hot summers, cold winters
Community: Smaller expat networks compared to Spain or Portugal
Activities:
Outdoor living (mountains, beaches)
Cultural and historical exploration
Slower pace of life
Example: Many UK retirees choose coastal towns like Varna for a balance between affordability and lifestyle, while others prefer rural villages for ultra-low living costs.
For UK retirees. Bulgaria uprates your UK State Pension and provides S1 healthcare access. It also has a flat 10% income tax, among the lowest in the EU, which combined with rock-bottom living costs makes it strong for pension-only retirees. Residency is via a Type D long-stay visa.
Will Your UK State Pension Rise? Frozen vs Uprated Countries
This is the single factor most retirement lists ignore. The UK only increases (uprates) the State Pension each year for residents of countries with a qualifying reciprocal agreement. Everywhere else it is frozen at the rate you first receive, and the gap compounds year after year.
Uprated (rises each year): Portugal, Spain, Greece, Cyprus, France and Bulgaria (EU/EEA), plus Turkey under a reciprocal agreement.
Frozen (never rises): Vietnam, Thailand, Malaysia, Mexico and Costa Rica.
A frozen pension can leave a retiree tens of thousands of pounds worse off over a long retirement compared with someone on the same record in the UK or the EU. It does not rule out low-cost destinations like Vietnam or Thailand, where the savings can more than absorb a static pension, but the maths must be done deliberately. Structuring private pensions, offshore investments for UK expats and tax-efficient withdrawals is what turns a frozen-pension country into a financially sound choice.
Aligning Lifestyle with Financial Strategy
When considering the best places to retire as an expat, the key is alignment. It’s about matching your financial position with your desired lifestyle and long-term objectives.
From a financial planning perspective, I always advise clients to consider:
Currency exposure and exchange rate risk
Tax residency and double taxation agreements
Access to healthcare and insurance requirements
Estate planning across jurisdictions
Investment portfolio structuring for international living
Relocating abroad can be one of the most rewarding decisions you make but it must be approached with clarity and structure.
As someone who specialises in advising expats, I take a pragmatic and collaborative approach to ensure your wealth strategy supports your lifestyle choices, wherever in the world you decide to call home.
How Benjamin Sharvell Can Support Your Retirement in Vietnam
Retiring in Vietnam can be both financially rewarding and personally enriching, but as with any international move, it requires careful planning to ensure your wealth supports your lifestyle over the long term.
This is where I work closely with clients.

As a financial adviser specialising in expat wealth management, I help UK retirees structure their finances so they can confidently relocate while maintaining control, flexibility, and long-term security.
When it comes to retiring in Vietnam, my role typically focuses on the following key areas:
Structuring Sustainable Income for Life Abroad
A successful retirement in Vietnam begins with ensuring your income is both reliable and efficient.
I work with clients to:
Align pension withdrawals with their cost of living in Vietnam
Structure investment portfolios to generate consistent income
Balance income and growth to ensure longevity of capital
Example: If your target monthly budget is £1,200, I will help design a withdrawal strategy that supports this level of income while preserving your portfolio for the future.
Managing Currency Exposure
Living in Vietnam means your day-to-day expenses will be in Vietnamese dong, while most UK retirees receive income in pounds sterling.
This introduces currency risk, which can impact your lifestyle.
I help clients to:
Implement structured currency transfer strategies
Avoid unnecessary exchange costs
Reduce the impact of short-term currency volatility
Tax Efficiency and Cross-Border Planning
One of the most overlooked aspects of retiring abroad is tax.
I provide guidance on:
UK tax residency status and implications
Structuring income to avoid unnecessary taxation
Navigating double taxation considerations
Ensuring compliance across jurisdictions
Investment Strategy for Expat Life
Your investment approach should evolve when you retire abroad.
I help clients:
Reposition portfolios for income and stability
Diversify globally to reduce risk
Align investments with long-term retirement goals
As an expat myself, I understand that your priorities shift, from accumulation to preservation and income, while still maintaining flexibility for future needs.
Long-Term Financial Planning and Peace of Mind
Ultimately, retiring in Vietnam is not just about reducing costs, it’s about improving your quality of life while maintaining financial confidence.
I take a pragmatic and collaborative approach, working with you to:
Plan for healthcare and unexpected expenses
Review estate and legacy planning across borders
Ensure your financial strategy adapts as your circumstances evolve
Start Planning Your Retirement Abroad
Choosing among the best places to retire as an expat is an exciting step but turning that vision into a secure and sustainable reality requires careful financial planning.
If you are considering retiring overseas, I can help you structure your finances with clarity and confidence.
Get in touch with Benjamin Sharvell IFA today!
Frequently Asked Questions
1. Where is the best place to retire abroad from the UK?
It depends on your priority. For an uprated pension, public healthcare via the S1 form and European familiarity, Portugal, Spain, Cyprus, Greece and France lead. For the lowest pension tax, Cyprus and Greece stand out. And for the lowest cost of living, Bulgaria, Turkey, Vietnam and Thailand are hard to beat.
2. Which of these countries freeze the UK State Pension?
Vietnam, Thailand, Malaysia, Mexico and Costa Rica freeze it, so it never rises. Portugal, Spain, Greece, Cyprus, France, Bulgaria and Turkey uprate it each year. Always confirm your destination with the UK's International Pension Centre.
3. What is the best place to live for retirees on a budget?
Bulgaria and Turkey (from around £700 a month), followed by Vietnam and Thailand, offer the lowest costs on this list. Our guide to the best countries to retire on a budget compares them in detail.
4. Do I need private health insurance to retire abroad?
Usually yes. In the EU and EEA, UK State Pension recipients can use the S1 form for public healthcare, but most retirees still add private cover for speed. Outside the EU, in Vietnam, Thailand, Malaysia, Mexico, Costa Rica and Turkey, private insurance is essential and is often a condition of the retirement visa.
5. Where can I retire abroad and pay the least tax on my UK pension?
Cyprus lets you elect a flat 5% on foreign pension income, and Greece offers a flat 7% for up to 15 years. Costa Rica does not tax foreign pension income at all. Your exact position depends on the relevant double taxation treaty, so take advice before relying on any regime.
6. How much money do I need to retire abroad from the UK?
Indicative couple budgets range from about £700 a month in Bulgaria or Turkey to £2,500 in France, with most destinations between £1,200 and £2,200. On top of living costs, many retirement visas set a minimum income or savings threshold. Our retirement planning for UK expats service can model this for your situation.