
As a globally experienced financial adviser specialising in wealth management for expat clients, I spend a great deal of time discussing one core question with UK nationals considering life abroad:
What are the best countries for British expats to live, work and build long-term financial security in?
The honest answer is that it is never just about sunshine or a lower cost of living. The right destination has to balance three practical things, cost of living, tax efficiency and quality of life, with two that most “best country” lists ignore entirely: whether your UK State Pension keeps rising once you move, and how you will access healthcare. Those two factors alone can be worth tens of thousands of pounds over a retirement.
Below are the nine best countries for British expats in 2026, assessed with financial practicality firmly in mind, and with a clear note on pensions, healthcare and visas for each. If you are weighing up the move itself rather than the destination, our guide on how to retire abroad walks through the process step by step.
Key Takeaways
The best country for British expats depends on your priorities: value and growth, European familiarity, tax-free income, or pure affordability.
Vietnam offers the strongest mix of low cost, opportunity and lifestyle for expats focused on building wealth, not just preserving it.
Portugal, Spain, France and Ireland keep your UK State Pension rising each year (uprating) and give access to public healthcare through the S1 form.
Vietnam, Thailand, Malaysia, Singapore and the UAE freeze your UK State Pension at the rate you first receive it, which can cost a retiree well over £50,000 across a long retirement.
The UAE (Dubai) is the standout for tax-free income, while Singapore suits high earners who can absorb the cost of living.
Whichever country you choose, structuring your pensions, investments and tax residency correctly matters more than the headline cost of living.
How We Chose the Best Countries for British Expats
This is not a lifestyle wish list. Each country below is assessed against the factors that actually shape a British expat's finances:
Cost of living in pounds, for a single person and a couple.
Tax environment, including how UK-sourced income and the Double Taxation Agreement are treated.
UK State Pension status, whether it is uprated (rises each year) or frozen.
Healthcare access for UK nationals, including S1 rights in the EU and private cover elsewhere.
Visa and residency route as it stands in 2026.
Quality of life, from climate and safety to community and connectivity.
Best Countries for British Expats at a Glance
Figures are indicative monthly costs for a couple and will vary by city and lifestyle. Always verify pension and visa positions before you move.
| Country | Est. monthly cost (couple) | UK State Pension | Healthcare for Brits | Main visa route (2026) | Best for |
|---|---|---|---|---|---|
| Vietnam | £1,500 to £1,800 | Frozen | Private cover | Work, business or long-stay TRC | Value and growth |
| Portugal | £1,600 to £2,200 | Uprated | S1 to public health | D7, D8 or Golden Visa (funds) | Europe and retirement |
| Spain | £1,800 to £2,400 | Uprated | S1 to public health | Non-Lucrative Visa | Sunshine and culture |
| France | £1,800 to £2,300 | Uprated | S1 (top-ranked system) | Long-stay visa (VLS-TS) | Proximity and healthcare |
| Ireland | £2,000 to £2,800 | Uprated | Common Travel Area rights | No visa needed (CTA) | Familiarity and careers |
| UAE (Dubai) | £2,500 to £3,500 | Frozen | Private (often employer) | Golden Visa or employment | Tax-free income |
| Thailand | £1,300 to £1,800 | Frozen | Private cover | Non-O retirement or LTR | Budget and lifestyle |
| Malaysia | £1,300 to £1,600 | Frozen | Private cover | MM2H programme | Affordable and English-speaking |
| Singapore | £3,000 to £4,000 | Frozen | Private (costly) | Employment or ONE Pass | High earners |
1. Vietnam – Outstanding Value, Growth Potential, and Lifestyle Balance
Vietnam continues to establish itself as one of the best countries for British expats, particularly for those seeking to balance lifestyle enjoyment with long-term financial progress.
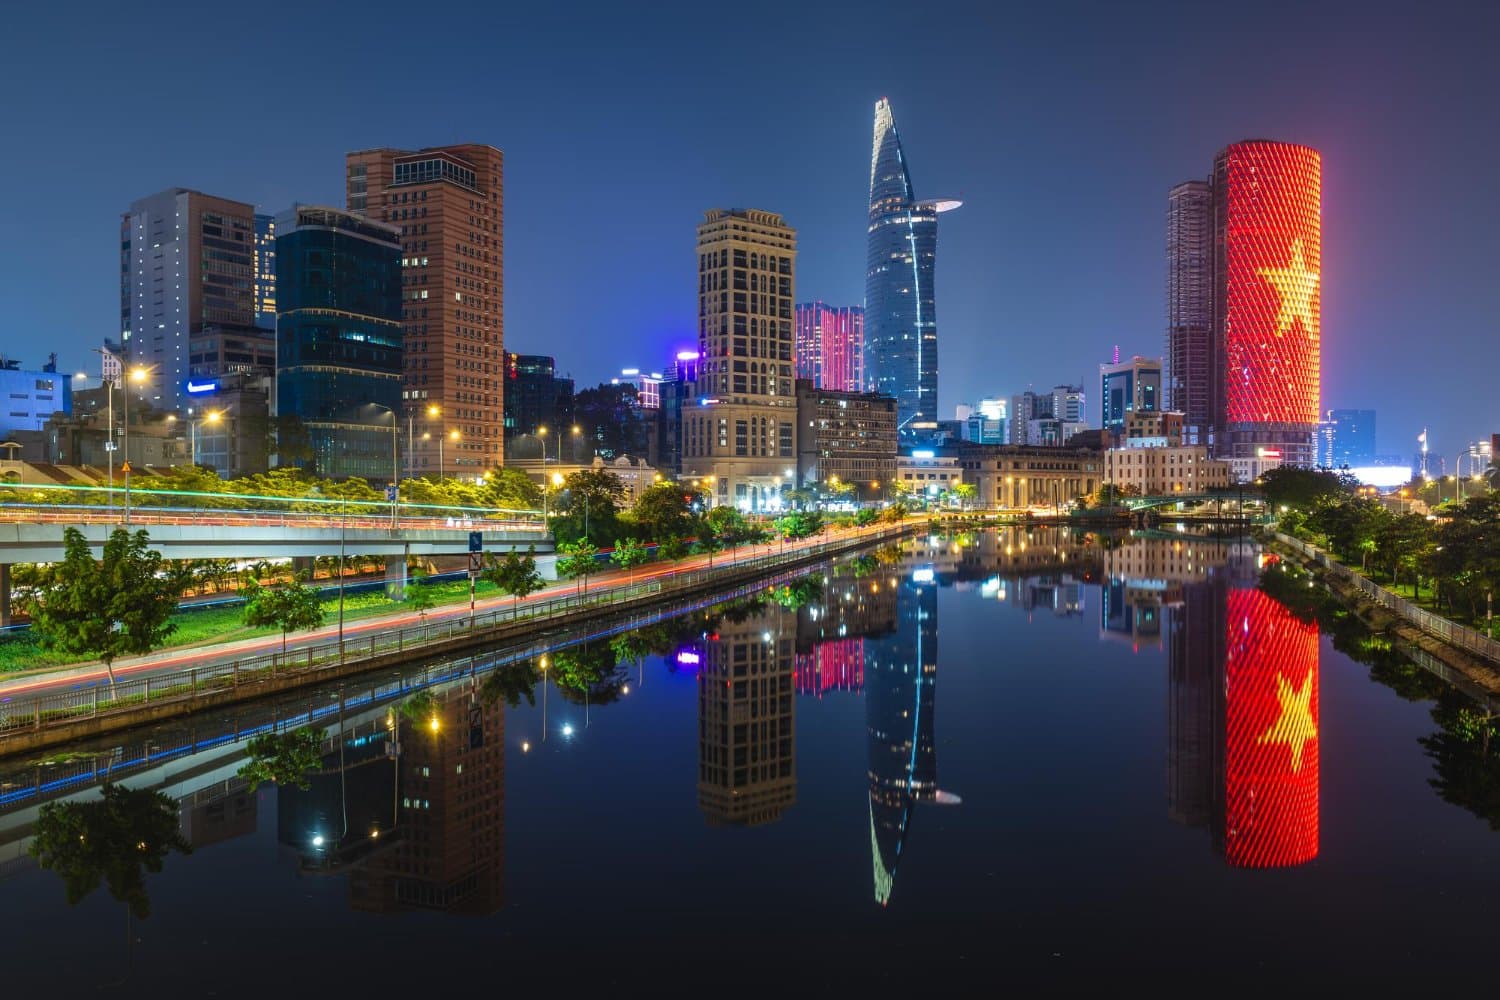
From my professional and personal experience living in Ho Chi Minh City, Vietnam offers a rare combination of affordability, opportunity, and momentum that is increasingly difficult to find elsewhere.
Cost of Living
One of the most compelling advantages is Vietnam's low cost of living relative to the UK. This affordability allows British expats to either significantly reduce monthly expenses or redirect surplus income towards investments, pensions, and future planning.
In Ho Chi Minh City, a single professional can live comfortably on approximately £900–£1,300 per month, while couples often manage well within £1,500–£1,800, depending on lifestyle choices. Importantly, this level of spending still allows for modern accommodation, dining out, and access to private healthcare.
Typical monthly costs include:
One-bedroom apartment in a central district: £400–£700
Utilities and high-speed internet: £40–£70
Local meals: £2–£4, with international dining still modest by UK standards
Transport (taxis, ride-hailing apps, fuel): £30–£60
As a result, many British expats find they can maintain their quality of life while spending 40–60% less than they would in the UK. This cost differential can be transformational when paired with disciplined saving and investing.
Tax Environment
Vietnam operates a progressive personal income tax system, with rates ranging from 5% to 35%, depending on income level. While this may appear comparable to the UK on the surface, the key distinction lies in how income is structured and sourced.
Crucially for British expats, the UK–Vietnam Double Taxation Agreement helps prevent income from being taxed twice. This makes Vietnam particularly attractive for individuals with international earnings, offshore investments, or business income.
Practical planning considerations often include:
Determining tax residency status in Vietnam
Structuring income between local salary and offshore sources
Positioning investments in tax-efficient jurisdictions
Coordinating Vietnam tax rules with UK non-resident status
When approached correctly, many expats are able to optimise their effective tax rate, freeing up additional capital for medium- and long-term goals. From a financial planning perspective, Vietnam rewards proactive and well-advised structuring rather than a passive approach.
What UK nationals should note. Vietnam is a frozen State Pension country, so your UK State Pension will not rise once you are resident here. That makes private pensions, offshore investments for UK expats and other income streams more important. There is also no NHS reciprocal cover, so private medical insurance is essential. For the practical side of receiving and managing income once you arrive, see our guide on managing your UK pension in Vietnam.
Quality of Life
Beyond cost and tax efficiency, Vietnam offers a high quality of life that continues to improve year on year. Ho Chi Minh City is a dynamic, international city with modern infrastructure, a growing professional services sector, and a well-established expat community.
Healthcare is a particular strength. International-standard private hospitals and clinics are readily available, with annual health insurance premiums often costing significantly less than private cover in the UK. International schools, co-working spaces, and serviced apartments are also widely accessible.
Lifestyle benefits include:
Warm climate year-round
Vibrant food and social culture
Excellent regional travel connections across Asia
A strong sense of personal safety in major cities
Perhaps most importantly, Vietnam offers upward momentum. It is a country experiencing economic growth, infrastructure investment, and increasing global relevance. For British expats, this creates not only lifestyle enjoyment but also a sense of opportunity, particularly for those focused on building wealth rather than simply preserving it.
Visa and residency. Vietnam has no dedicated retirement visa, so most British expats stay through work, business or a temporary residence card obtained via a qualifying route. Our guide on the Vietnam retirement visa explains the current options, and if you want the full picture on budgets, see how much you need to retire in Vietnam and our hub on how to retire in Vietnam.
2. Portugal: Europe's Enduring Favourite for British Expats
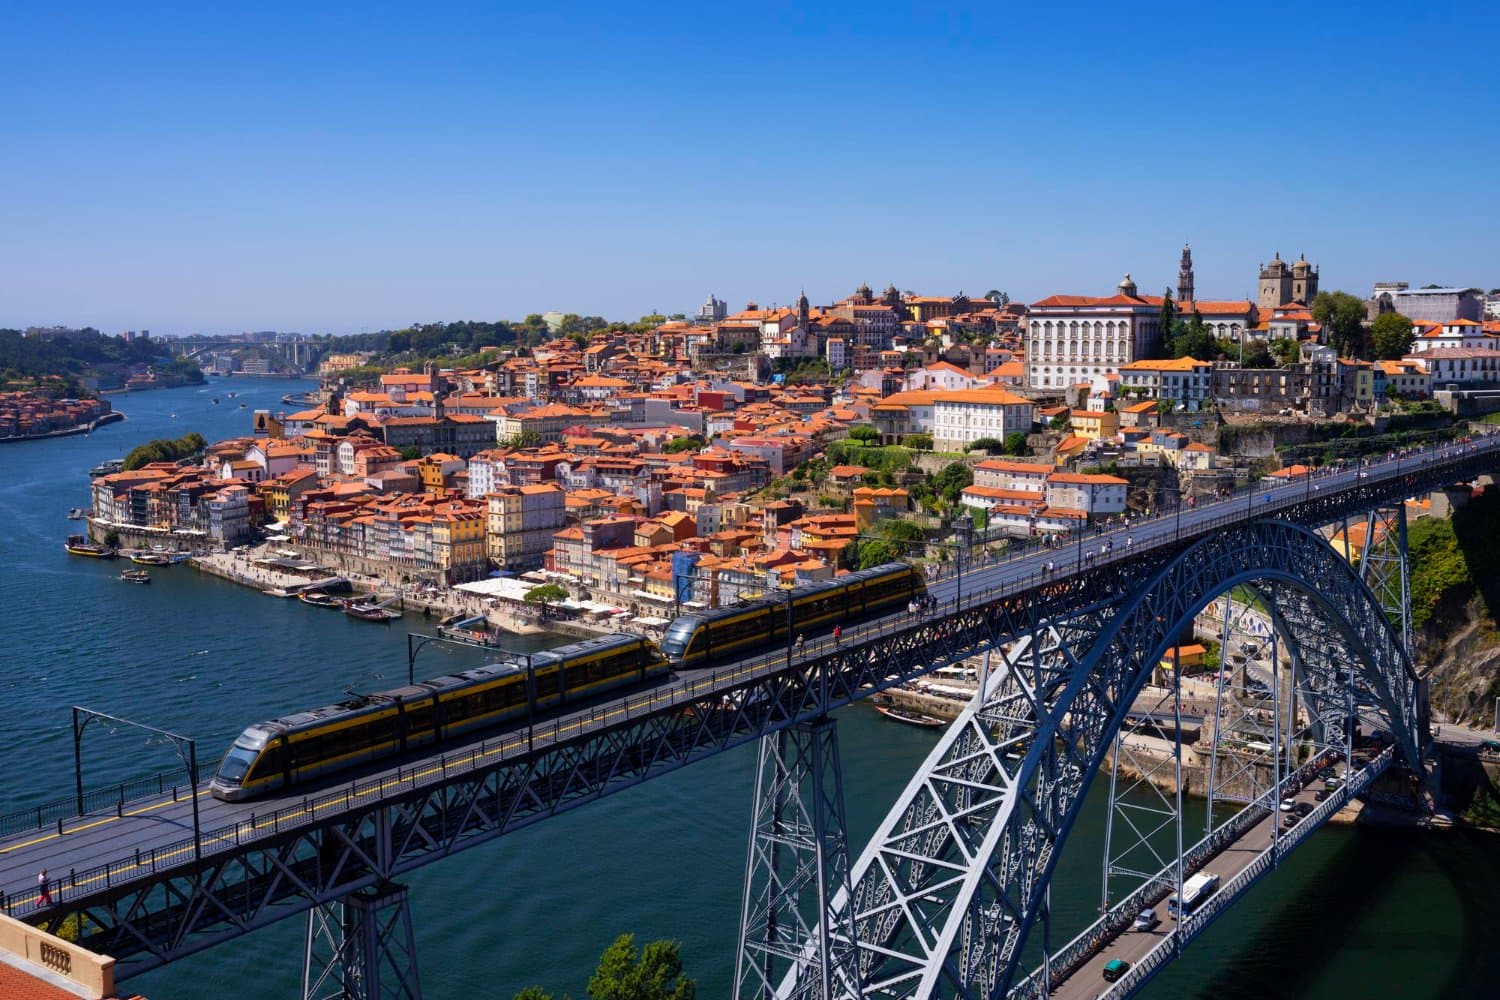
Portugal is consistently one of the most popular destinations for British expats, and it is a notable omission from many “best country” lists. It combines a mild climate, a relaxed pace of life and one of the largest UK communities in Europe, particularly across the Algarve, with a genuinely important financial advantage: your UK State Pension keeps rising.
Cost of Living
Portugal offers strong value for a Western European country. Outside Lisbon and Porto, a couple can often live comfortably on £1,600 to £2,000 per month, while the two main cities push costs higher. Typical monthly costs include:
One-bedroom apartment outside the city centre: £700 to £1,100
Utilities and internet: £100 to £150
Groceries and dining: generally lower than the UK for comparable quality
Public transport: £40 to £70
Tax Environment
Portugal's headline Non-Habitual Resident (NHR) regime was closed to new entrants at the start of 2024 and replaced by the narrower IFICI scheme, sometimes called NHR 2.0, which targets specific high-value professions. For most retirees, the practical position is now standard Portuguese residency taxation, softened by the UK to Portugal Double Taxation Agreement. This makes structuring your pension income and investment withdrawals before you move more important than it was under the old regime, and professional advice is strongly recommended.
What UK nationals should note. Portugal is an uprated country, so your UK State Pension rises each year in line with the UK triple lock. As a State Pension recipient you can also register the S1 form to access Portugal's public health service. Visa routes include the D7 (passive or pension income, with a low income threshold), the D8 digital nomad visa, and the restructured Golden Visa, which is now based on qualifying investment funds rather than property.
Quality of Life
Portugal ranks highly for safety, climate and friendliness towards English speakers, especially in expat-heavy areas. The healthcare system is solid, English is widely spoken in tourist and coastal regions, and the country's Schengen location makes European travel straightforward. For retirees and remote workers who want a warm, familiar and pension-friendly base within the EU, Portugal is hard to beat.
3. Spain
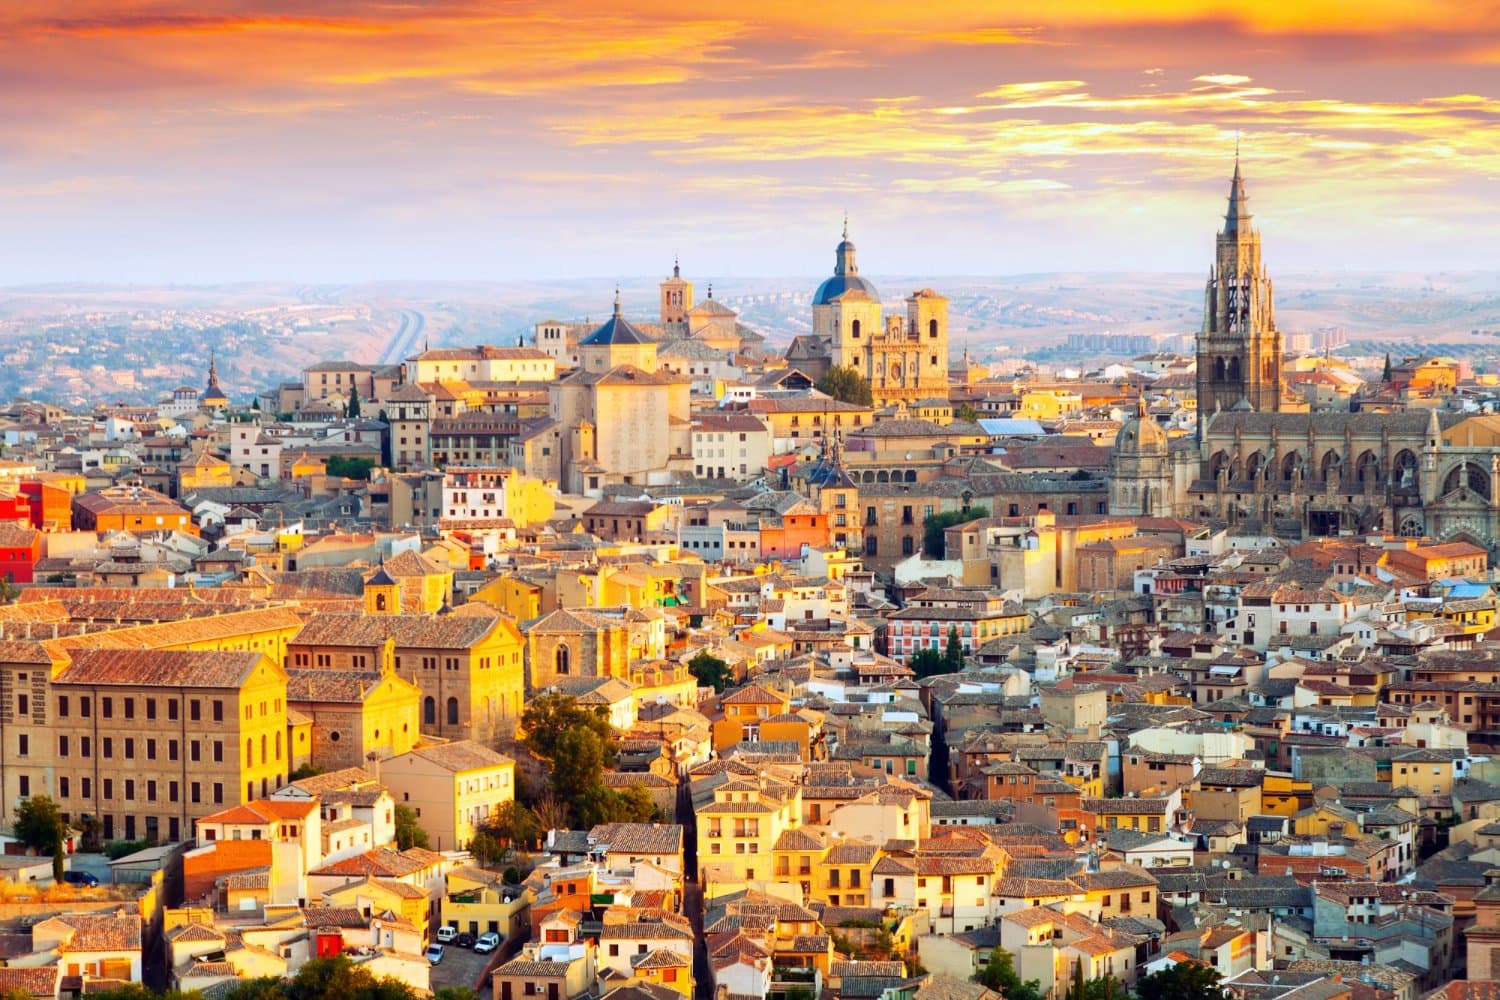
Spain remains one of the most popular destinations among the best countries for British expats, particularly for retirees and lifestyle-led movers. Its climate, culture and healthcare system continue to attract UK nationals, but Spain is also a country where careful tax planning is essential to avoid unintended financial consequences.
Cost of Living
Spain offers a broad range of living costs depending on location. Madrid and Barcelona command higher prices, while many coastal regions and inland cities provide excellent value, especially for those relocating from London or the South East. Outside major city centres, a comfortable lifestyle is often achievable on £1,200 to £1,600 per month for a single person, with couples managing within roughly £1,800 to £2,000. Typical monthly costs include:
One-bedroom apartment outside prime areas: £500 to £800
Utilities and internet: £80 to £120
Local meals: £8 to £12, with excellent value for quality dining
Public transport: £50 to £80
Tax Environment
Spain's tax system is progressive and can be relatively high, particularly for higher earners and those with substantial assets. Income tax rates vary by region but can exceed 45 percent, and wealth tax may apply depending on residency, asset levels and the autonomous community. Key considerations for British expats include establishing Spanish tax residency (typically 183 days or more), understanding how pensions, rental income and investments are treated, and assessing exposure to wealth and succession taxes. The UK to Spain Double Taxation Agreement helps prevent double taxation but does not remove the need for structured planning.
What UK nationals should note. Spain is an uprated country, so your UK State Pension keeps rising, and the S1 form gives State Pension recipients access to the public health system. On visas, Spain closed its Golden Visa to new applicants on 3 April 2025, so the main routes are now the Non-Lucrative Visa for those with sufficient passive income and the Beckham Law for qualifying employees.
Quality of Life
Spain's quality of life is consistently cited as one of its greatest strengths, with a relaxed pace of life, a strong social culture and a healthcare system widely regarded as one of the best in Europe. Notable benefits include quality public and private healthcare, a Mediterranean climate, established British communities and a rich cultural, culinary and outdoor lifestyle. For retirees and semi-retirees, Spain's accessibility, familiarity and infrastructure make day-to-day living straightforward and enjoyable.
4. France
France continues to rank among the best countries for British expats, particularly for those who value proximity to the UK alongside a high standard of living. Its cultural depth, robust public services and strong infrastructure make it appealing for UK nationals seeking lifestyle benefits without relocating too far from home.
Cost of Living
France's cost of living varies significantly by region. Paris is among Europe's most expensive cities, while provincial cities and rural areas offer considerably better value. Outside Paris, many British expats find a comfortable lifestyle achievable on £1,500 to £2,000 per month, with couples often managing within £1,800 to £2,300. Typical monthly costs include:
One-bedroom apartment outside Paris: £700 to £1,100
Utilities and internet: £100 to £150
Groceries and dining: generally lower than the UK for comparable quality
Public transport: £60 to £100
Tax Environment
France has a comprehensive tax system, and British expats should approach it with careful planning. Personal income tax is progressive, and social contributions can significantly increase overall exposure if not managed correctly. Key considerations include determining French tax residency (usually based on your centre of economic and personal interests), understanding the taxation of pensions, rental income and investment portfolios, and coordinating with your UK non-resident status. The UK to France Double Taxation Agreement helps mitigate double taxation but does not remove the need for proactive structuring.
What UK nationals should note. France is an uprated country, so your UK State Pension continues to rise, and its healthcare system is consistently ranked among the best in the world, freely accessible to S1 holders. The usual route is a long-stay visa (VLS-TS) converted to residency; the main challenge is administrative rather than financial.
Quality of Life
France's quality of life is one of its defining strengths, ranking highly for healthcare, life expectancy and social infrastructure. Benefits include renowned cuisine and food standards, extensive transport infrastructure, rich cultural and recreational opportunities and diverse living environments from cities to countryside and coast. For families there are strong education options, and for retirees the combination of healthcare, culture and a slower pace is particularly attractive.
5. Ireland
Ireland remains a compelling option among the best countries for British expats, particularly for those who value cultural familiarity while still benefiting from an internationally connected economy. For UK nationals who wish to remain close to home without sacrificing career prospects or lifestyle quality, Ireland offers a balanced and reassuring transition.
Cost of Living
Ireland's cost of living varies significantly by location. Dublin is comparable to London for accommodation and daily expenses, while regional cities and towns provide considerably better value. Outside Dublin, a comfortable lifestyle is often achievable on £1,400 to £1,800 per month, whereas the capital may require £2,000 to £2,400 or more. Typical monthly costs include:
One-bedroom apartment outside Dublin city centre: £700 to £1,000
Utilities and internet: £120 to £160
Groceries and dining: broadly similar to the UK
Public transport: £80 to £120
Tax Environment
Ireland's personal tax system is more complex than some expat destinations, with progressive income tax rates and social contributions that can lead to a relatively high overall burden. That does not automatically make it unattractive from a planning perspective. Key considerations include understanding Irish tax residency and domicile status, coordinating with your UK non-resident status and structuring pensions, investments and offshore assets efficiently. Ireland has an extensive Double Taxation Agreement network, including with the UK.
What UK nationals should note. Ireland is the easiest country in this list to move to. Under the Common Travel Area, British citizens can live, work and access healthcare in Ireland without a visa, and your UK State Pension is uprated. This makes Ireland uniquely low-friction for Brits who want a fresh start without leaving the familiarity of an English-speaking, EU-connected economy.
Quality of Life
Ireland offers a high quality of life built on strong institutions, modern infrastructure and a familiar cultural environment. English is the primary language, and many British expats find social and professional integration seamless. Healthcare combines public and private systems, and Ireland benefits from strong worker protections, a vibrant cultural scene, quality education and close proximity to the UK. From a career perspective, Ireland is home to many multinationals in technology, pharmaceuticals, finance and professional services.
6. United Arab Emirates (Dubai and Abu Dhabi): Tax-Free Income
No serious list of the best countries for British expats is complete without the UAE. Dubai and Abu Dhabi have become magnets for UK professionals and entrepreneurs, and the single biggest draw is simple: there is no personal income tax. For higher earners in finance, construction, technology and hospitality, that can transform how quickly wealth is built.
Cost of Living
The UAE is not cheap, and housing is the main cost driver. A couple should typically budget £2,500 to £3,500 per month, more with international schooling. Typical monthly costs include:
One-bedroom apartment in a central area: £1,300 to £2,000
Utilities and internet: £150 to £250
Dining out: mid-range to high, though local options are affordable
Transport: efficient metro and taxis, with many residents running a car
Tax Environment
The UAE levies no personal income tax, no capital gains tax and no inheritance tax on individuals, which is why it is so attractive for wealth accumulation. The key planning point for Brits is getting your UK exit right: confirming non-resident status through the Statutory Residence Test, filing form P85 where relevant, and structuring UK assets and pensions so the tax-free environment works fully in your favour. Tax-free income only delivers its full benefit when the UK side is handled correctly.
What UK nationals should note. The UAE is a frozen State Pension country, so your UK State Pension will not rise once you are resident. There is no reciprocal healthcare, so private medical insurance is essential, though employers in Dubai and Abu Dhabi usually provide it. Residency is typically via employment or the UAE Golden Visa, available through qualifying investment or a high salary threshold.
Quality of Life
The UAE offers world-class infrastructure, a very high standard of safety, excellent international schools and a large, well-established British community. The climate is hot for much of the year, and the lifestyle is fast-paced and consumer-focused, which suits some expats more than others. For career-driven Brits and high earners, the combination of tax-free income and global connectivity is compelling.
7. Thailand
Thailand remains firmly positioned among the best countries for British expats, particularly for those seeking affordability, accessibility, and a well-developed expat ecosystem.
Over many years, Thailand has built an infrastructure that caters specifically to foreign residents, making it one of the easiest countries in Southeast Asia for British nationals to settle into.
Cost of Living
Thailand continues to offer an attractive cost of living, especially when compared with the UK. While prices in Bangkok and popular island destinations have risen, overall expenses remain manageable, allowing expats to enjoy a comfortable lifestyle without excessive financial pressure.
In cities such as Bangkok, Chiang Mai, and Pattaya, a single British expat can live comfortably on £800–£1,200 per month, while couples often manage within £1,300–£1,600, depending on accommodation choices and lifestyle preferences.
Typical monthly costs include:
One-bedroom apartment in a city centre: £350–£650
Utilities and internet: £50–£80
Local meals: £1.50–£3, with international dining still affordable
Public transport and taxis: £40–£70
As a result, many British expats find they can maintain a higher standard of living than in the UK while preserving more disposable income for savings, investments, or travel.
Tax Environment
Thailand taxes individuals on Thai-sourced income, while foreign-sourced income has historically been treated differently depending on timing, residency, and remittance rules. This area requires particular care, as tax interpretation and enforcement can evolve.
For British expats, key considerations often include:
Establishing whether income is locally earned or foreign sourced
Understanding Thai tax residency rules (typically 180 days or more)
Coordinating Thailand tax exposure with UK non-resident status
Reviewing how pensions, dividends, and investment income are treated
Thailand has a Double Taxation Agreement with the UK, which helps prevent income from being taxed twice. However, due to the nuances involved, proactive planning and professional advice are essential to avoid unexpected liabilities and ensure compliance.
From a financial planning perspective, Thailand can be very effective when income streams are clearly structured and documented.
What UK nationals should note. Thailand is a frozen State Pension country, confirmed again by the UK government in 2026, so your State Pension will not rise once you are resident. Healthcare is strong but private: Thailand has excellent internationally accredited hospitals at a fraction of UK private prices, and insurance is essential. The main route for older expats is the Non-O retirement visa (age 50 plus, with a deposit or income requirement), with the newer LTR visa suiting wealthier applicants. If you are torn between the two most popular Asian bases, our Vietnam vs Thailand for UK retirees comparison goes deeper.
Quality of Life
Thailand’s quality of life is one of its strongest attractions. The country offers a welcoming culture, strong service standards, and a mature expat infrastructure that makes day-to-day living straightforward for British nationals.
Private healthcare is a notable strength, with internationally accredited hospitals available across major cities. Annual private health insurance premiums are often significantly lower than comparable cover in the UK, while standards remain high.
Additional lifestyle benefits include:
Well-established British and international expat communities
Wide availability of English-speaking professionals
Excellent food culture and social lifestyle
Convenient regional travel across Southeast Asia
Moreover, Thailand offers a variety of environments, allowing expats to tailor their lifestyle according to personal priorities and stage of life.
8. Malaysia
Malaysia is often overlooked in discussions about the best countries for British expats, yet it offers one of the most balanced combinations of affordability, accessibility, and liveability in Southeast Asia.
For UK nationals seeking a lower-cost lifestyle without sacrificing modern infrastructure or ease of communication, Malaysia presents a compelling and practical option.
Cost of Living
Malaysia offers a consistently low cost of living, particularly in cities such as Kuala Lumpur and Penang, where high-quality accommodation and services remain affordable by international standards.
A single British expat can typically live comfortably on £900–£1,200 per month, while couples often manage within £1,300–£1,600, depending on housing choices and lifestyle preferences.
Typical monthly costs include:
One-bedroom apartment in a central location: £350–£600
Utilities and high-speed internet: £50–£80
Local meals: £2–£4, with international options still reasonably priced
Transport (public and ride-hailing services): £30–£60
This affordability allows many expats to allocate a greater proportion of income towards savings, investments, or travel, enhancing long-term financial flexibility.
Tax Environment
Malaysia operates a territorial tax system, meaning that income earned within Malaysia is generally taxable, while foreign-sourced income is often not subject to Malaysian tax, depending on individual circumstances and prevailing regulations.
Key planning considerations for British expats include:
Determining Malaysian tax residency status
Understanding the treatment of employment income versus offshore income
Coordinating Malaysian tax rules with UK non-resident status
Reviewing pension and investment income structures
Malaysia also has a Double Taxation Agreement with the UK, which provides further clarity and protection against double taxation. When income streams are clearly defined and structured, Malaysia can be a highly efficient base from a tax perspective.
What UK nationals should note. Malaysia is a frozen State Pension country, so plan for a static State Pension and lean on private pensions and investments. Healthcare is a genuine strength, with high-quality private hospitals at affordable prices, and private cover is recommended. Longer-term residency is usually via the Malaysia My Second Home (MM2H) programme, which has been revamped into tiers with financial requirements.
Quality of Life
Malaysia offers a high quality of life supported by modern infrastructure, reliable services, and a culturally welcoming environment. English is widely spoken, particularly in business and professional settings, making day-to-day life straightforward for British expats.
Additional lifestyle benefits include:
Quality private healthcare at affordable costs
International schools and universities
Well-developed shopping, dining, and leisure facilities
A diverse cultural and culinary landscape
Penang, in particular, is popular among British retirees due to its slower pace of life, coastal setting, and strong expat community, while Kuala Lumpur appeals to professionals seeking urban convenience and connectivity.
9. Singapore
Singapore continues to rank among the best countries for British expats, particularly for professionals, entrepreneurs and investors seeking stability, transparency and access to global markets. It offers strong earning potential, efficient governance and a highly favourable business environment.
Cost of Living
Singapore is consistently ranked among the most expensive cities in the world, with housing the primary cost driver. However, for British expats relocating for senior or regional roles, higher salaries often offset elevated costs. A single professional should expect £2,200 to £2,800 per month, while couples and families may exceed this. Typical monthly costs include:
One-bedroom apartment in a central area: £1,200 to £1,700
Utilities and high-speed internet: £120 to £180
Local meals at hawker centres: £4 to £6, with international dining significantly higher
Public transport: £80 to £120, with no need for a private vehicle
Tax Environment
Singapore's tax system is one of its strongest attractions. Personal income tax is progressive and capped at 24 percent, with no capital gains tax and no inheritance tax, creating a favourable environment for long-term wealth accumulation when income and investments are structured appropriately. Key considerations include understanding Singapore tax residency, planning around foreign-sourced income and remittance rules, and coordinating with your UK non-resident status.
What UK nationals should note. Despite its low taxes, Singapore is a frozen State Pension country, so the State Pension advantage sits with European destinations, not here. Healthcare is world-class but expensive, so comprehensive private insurance is essential. Singapore has no retirement visa, so residency is generally tied to employment, an Employment Pass, or the ONE Pass for high earners, which makes it best suited to working professionals rather than retirees.
Quality of Life
Singapore offers an exceptionally high quality of life, underpinned by political stability, personal safety and world-class infrastructure. It is consistently ranked highly for liveability, healthcare quality and ease of doing business. Benefits include internationally recognised healthcare and education, clean and efficient public transport, strong rule of law and a multicultural, English-speaking environment. For British families it is especially attractive for its safety, international schools and family-friendly planning, and its location makes it an excellent hub for travel across Asia-Pacific.
The Financial Factor Most “Best Country” Lists Ignore: Your UK State Pension
If you rely on the UK State Pension in retirement, where you move can quietly cost you a fortune. The UK only increases (uprates) the State Pension each year for residents of countries with a qualifying reciprocal agreement. Everywhere else, it is frozen at the rate you first receive.
Uprated (your pension rises each year): Portugal, Spain, France, Ireland and the rest of the EU and EEA, plus Switzerland, Gibraltar, the USA and a handful of reciprocal-agreement countries.
Frozen (your pension never rises): Vietnam, Thailand, Malaysia, Singapore, the UAE, plus Australia, Canada, New Zealand and most of Asia.
The impact compounds. A pensioner in a frozen country can end up tens of thousands of pounds worse off over a long retirement compared with someone on the same record living in the UK or the EU. This does not rule out places like Vietnam or Thailand, where the low cost of living can more than absorb a static State Pension, but it does mean the maths has to be done deliberately. The right structure, using private pensions, offshore investments for UK expats and tax-efficient withdrawals, is what turns a frozen-pension destination into a financially sound one. This is exactly the kind of planning a specialist adviser exists to handle.
Choosing the Best Country for British Expats
The best countries for British expats are those that align lifestyle goals with sound financial planning.
Vietnam, particularly Ho Chi Minh City, continues to stand out as a compelling option for British expats seeking affordability, opportunity, and growth potential. From my own experience living and working here, Vietnam offers an exceptional balance between lifestyle enjoyment and financial progress.
If you are considering moving to Vietnam and are wondering about the financial side of it all, get in touch with Benjamin Sharvell IFA today to get a free consultation!
Frequently Asked Questions
1. What is the best country for British expats in 2026?
There is no single best country; it depends on your priorities. Vietnam leads for value, growth and lifestyle; Portugal, Spain and France lead for European retirees who want an uprated pension and public healthcare; Ireland is the easiest move under the Common Travel Area; and the UAE wins for tax-free income. The right choice is the one that fits your income, pension and long-term financial plan.
2. Which countries freeze the UK State Pension?
Your UK State Pension is frozen in countries without a qualifying reciprocal agreement, including Vietnam, Thailand, Malaysia, Singapore, the UAE, Australia, Canada and New Zealand. It is uprated in the EU and EEA (including Portugal, Spain, France and Ireland), Switzerland, Gibraltar, the USA and a small number of other countries. Always confirm your destination's status with the UK's International Pension Centre.
3. Can British expats still access the NHS or healthcare abroad?
You lose routine NHS access once you are no longer ordinarily resident in the UK. In the EU and EEA, UK State Pension recipients can use the S1 form to access the local public health system funded by the UK. Outside the EU, in places like Vietnam, Thailand, the UAE and Singapore, you rely on private medical insurance, which is essential to arrange before you move.
4. What is the cheapest country for British expats to live in?
Among these destinations, Malaysia, Vietnam and Thailand offer the lowest cost of living, with couples often comfortable on £1,300 to £1,800 per month. If budget is your main concern, our guides on the best countries to retire on a budget and the best Asian countries for expats compare the options in more detail.
5. Do I still pay UK tax if I move abroad?
It depends on your residency. Most British expats aim to become UK non-resident under the Statutory Residence Test, which changes how your income is taxed, though certain UK-sourced income (such as UK rental income) can remain taxable. Double Taxation Agreements prevent the same income being taxed twice. Getting your UK exit right, including notifying HMRC, is a key part of any move.
6. Which countries are easiest for Brits to move to after Brexit?
Ireland is the easiest by far: under the Common Travel Area, British citizens can live and work there without a visa. Within the EU, Portugal's D7 visa (for those with pension or passive income) and D8 digital nomad visa are among the more accessible routes, while Spain's Non-Lucrative Visa suits retirees with sufficient savings.